Inspired Entertainment's Halved Stock Tests Whether Q2 Really Was The Interactive Trough
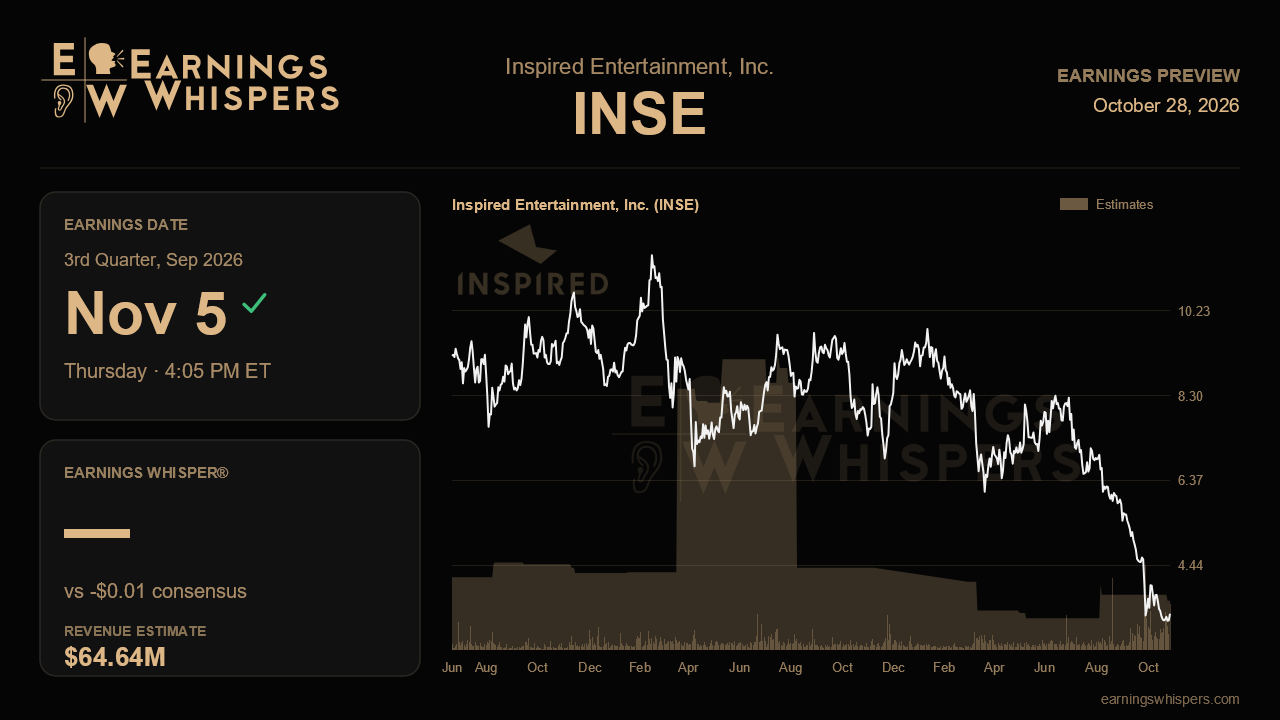
Inspired Entertainment heads into its third-quarter report with a striking disconnect. Three months ago management reaffirmed full-year EBITDA guidance, showed a record 45% company margin and argued that the near doubling of the UK remote gaming duty had simply masked strong underlying demand. The market has not bought it. Shares have fallen 52% since that report while the S&P 500 was essentially flat. The question for November 5 is no longer whether margins look good. It is whether this quarter shows the turn management promised, or confirms the market's suspicion that something is breaking.
The Street is braced for an ugly-looking quarter. Consensus calls for a loss of about a penny per share against earnings of $0.28 a year ago, and revenue of roughly $64.6 million, down about 25% from $86.2 million. Those year-over-year comparisons look like a collapse, but the sequential picture matters more. Revenue of $64.6 million would be a modest step up from the $60.8 million reported last quarter, consistent with a business stabilizing after a tax-driven reset rather than one still sliding. Management's full-year EBITDA range of $112 million to $118 million, unchanged across several calls, is the real anchor. With a seasonally stronger fourth quarter and custom game development payments already slated for that period, the third quarter does not need to carry the year, but it does need to keep the guidance math believable.
The interactive segment is the heart of the test. After ten straight quarters of 40%-plus EBITDA growth, interactive earnings grew only about 13% in the second quarter as the UK duty jumped from 21% to 40% on April 1, wiping out the benefit of 40% gross gaming revenue growth. Management called that quarter the trough and said the familiar pattern of EBITDA outgrowing revenue would return in the second half. The year-over-year comparison stays distorted until April, so the cleaner signal is sequential: interactive revenue and EBITDA rising from second-quarter levels would validate the trough argument, while another sequential decline would undercut it badly. Early contributions from the July Alberta iGaming launch and the Massachusetts Lottery rollout, which brings Inspired to four lottery states, should help show whether new markets can offset the UK tax drag.
Elsewhere, investors should look for confirmation that the margin story holds. Retail Solutions topped a 50% segment margin before corporate costs last quarter, and anything that keeps company margins in the mid-40s keeps the fiscal 2027 targets of $130 million in EBITDA and a 47% margin in play. Cash flow deserves equal attention. Management argued that conversion was running above 25% of EBITDA once a one-time $7 million pub restructuring outflow is excluded, and net leverage sat at 3.0x. Clean free cash flow without that drag and continued debt reduction would go a long way toward answering the balance sheet worries implicit in the share price. On the other side, any update on the floated UK machine duty increase, further slippage of Chicago VLTs into 2027, or more caution on the hybrid dealer product, which management already said may not grow as large as hoped, would feed the bear case.
Sentiment has soured noticeably, with bearish readings climbing to about 74% from roughly 49% ahead of the last report. The stock trades at $3.33, near the bottom of its post-earnings range of $3.10 to $6.99 and less than half its 200-day moving average of $6.82, a dramatic break from last quarter's $6.39 to $8.53 range. That leaves a low bar on sentiment but a high bar on credibility.
Ultimately, the report hinges on one thing: whether Inspired can reaffirm its full-year EBITDA range while showing interactive earnings climbing off the second-quarter low. Do that, and the selloff starts to look like an overreaction to a tax artifact. Trim guidance or show no sequential recovery, and the market's verdict will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Sep-29 | |
| Sep-24 | |
| Aug-18 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-30 | |
| Jul-21 | |
| Jul-13 | |
| Jun-22 | |
| May-19 | |
| May-18 |
