Indie Semiconductor's Promised Ramp Faces A Proof Test As Shares Sit Near Lows
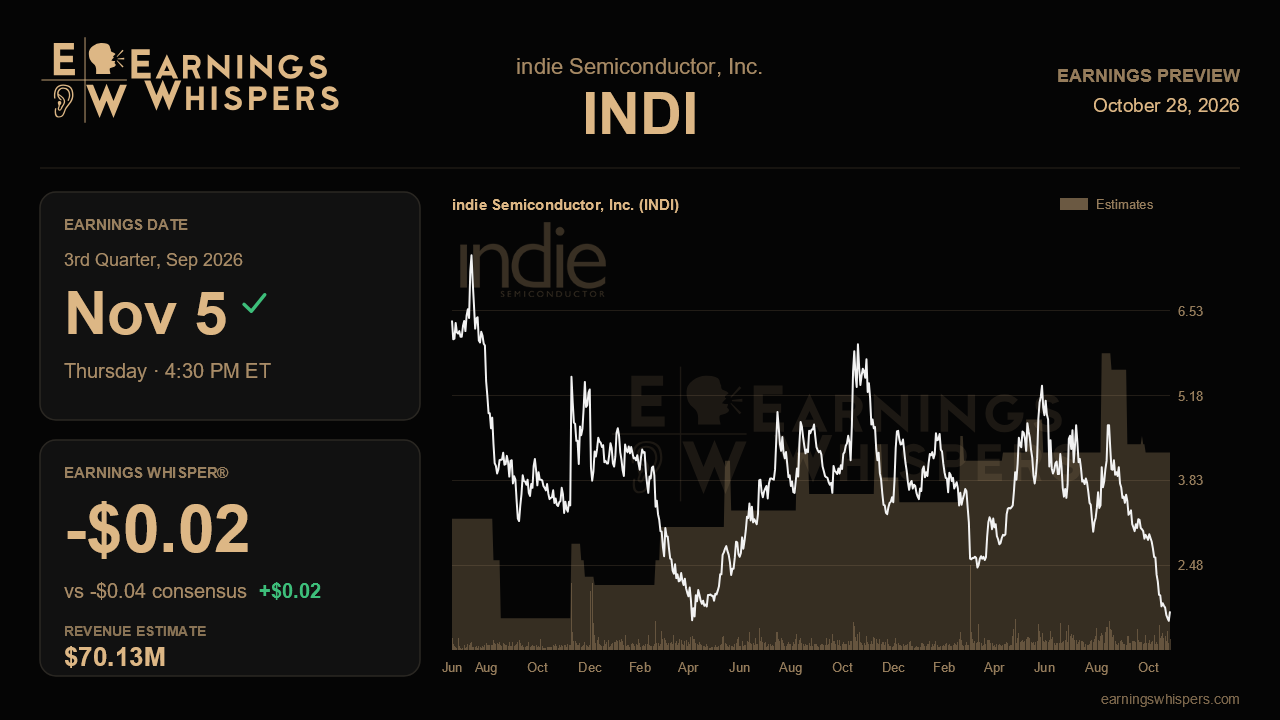
indie Semiconductor enters its third-quarter report with an unusual disconnect. Three months ago, management described a business reaching an inflection point, with revenue reaccelerating, losses narrowing and radar and vision design wins turning into production orders. Since then the stock has lost more than half its value, falling about 58% while the S&P 500 was essentially flat. The report after the close on November 5 needs to show whether the operating story is still intact, or whether the market correctly sensed that the ramp would be harder and more costly than management suggested.
The headline numbers are anchored to guidance. Analysts expect revenue of about $70.1 million, which is effectively the midpoint of management's $67 million to $73 million range. That would be roughly 31% growth from $53.7 million a year earlier and a solid step up from $64 million last quarter. Consensus calls for a non-GAAP loss of $0.04 per share, matching what management guided. The Earnings Whisper sits at a loss of $0.02, a bit better than consensus. The gap is small in dollar terms, but it suggests the more engaged investors expect at least a modest beat on profitability. Because the Street has not stretched beyond the guided range, an in-line quarter clears the bar without proving much. A result toward the top of the range, along with a fourth-quarter outlook that keeps the momentum going, would carry more weight.
The mix of that revenue matters as much as the total. Management guided the core business to about $40 million, up from $36 million in the second quarter. That figure is the cleanest read on whether radar, the IND880 DRAMless vision processor and other design wins are converting into shipments. The Wuxi subsidiary swung from $29.7 million to $21 million and back to $28 million over the past three quarters, so a total-revenue beat driven by China volatility would say less than a core-business beat. Commentary on the 77GHz radar ramp with Volvo's Tier 1 supplier, follow-on OEM wins in North America and China, and quantum photonics bookings after last quarter's record should show whether the catalysts introduced last quarter are developing or still mostly pipeline.
Cash is the counterweight. Cash fell $35.7 million in one quarter to $149 million as indie built inventory and spent on capital equipment ahead of the ramp. The market's selloff suggests investors are increasingly focused on how long that runway lasts. Evidence that the inventory is moving into rising revenue, that burn is easing, and that the operating loss keeps narrowing from last quarter's $8.9 million would ease much of that concern. Gross margin is another swing factor. Management has not given guidance but continues to point toward a 50% to 55% long-term target, so movement in that direction would support the operating leverage argument. Updates on the pending AMS Osram CMOS image sensor acquisition, which management expects to close before year end, and on the regulatory-gated Wuxi divestiture also matter because each changes the company's revenue base and capital needs.
Sentiment remains bearish but somewhat less so than ahead of last quarter, and the stock trades near $1.74. That is less than half its 200-day moving average of $3.59 and not far above the post-earnings low of $1.54, a sharp break from last quarter's range of roughly $3 to $5.50. Expectations are depressed, which lowers the bar for a relief move, but a weak quarter could still push the stock to new lows.
The key question is whether indie can show that last quarter's acceleration is now self-sustaining. A core business at or above $40 million, a narrower loss and slower cash burn would support management's confident tone. A miss on core revenue combined with another large drop in cash would suggest the market's skepticism was justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-21 | |
| Oct-19 | |
| Oct-14 | |
| Sep-04 | |
| Aug-06 | |
| Jul-07 | |
| Jun-22 | |
| Jun-10 | |
| May-29 | |
| May-11 | |
| May-07 | |
| Apr-21 | |
| Apr-09 | |
| Mar-27 |
