The Joint Needs Comps To Turn Positive To Make Its Pure-Play Franchisor Pitch Stick
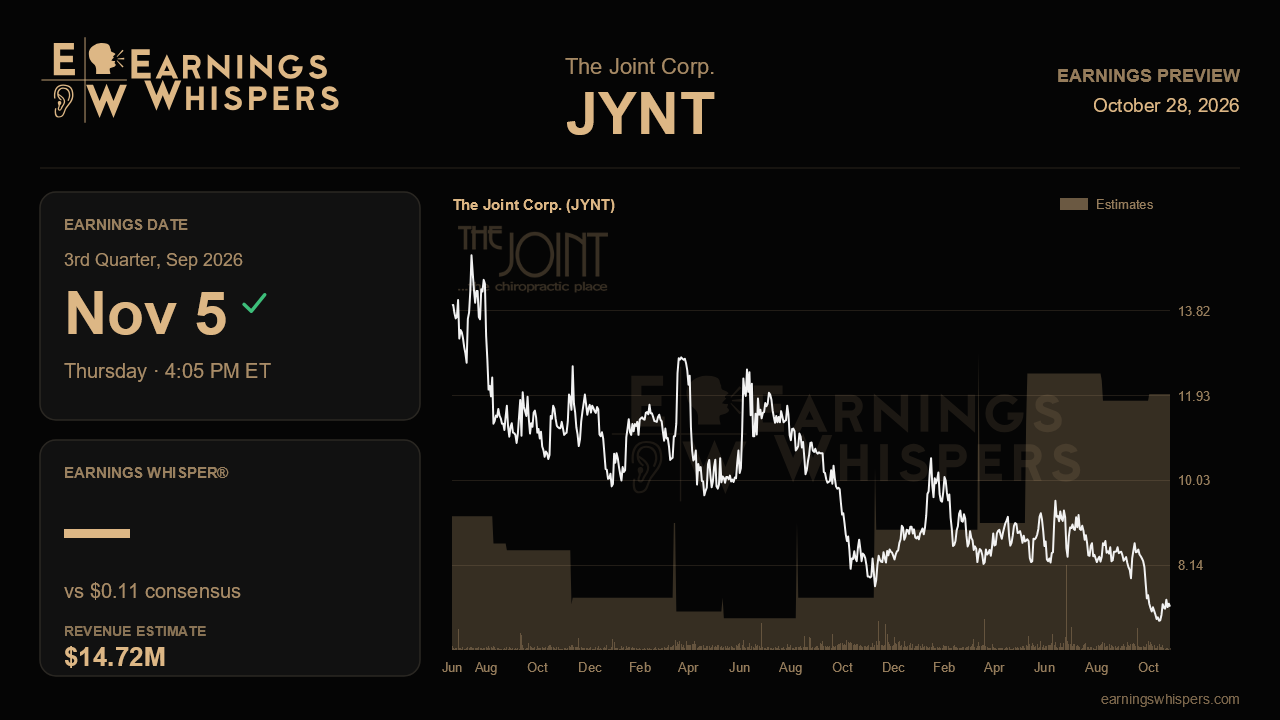
The Joint Corp. spent the past year dismantling its company-owned clinic portfolio so it could present itself as a lean, capital-light franchisor. When the chiropractic chain reports third-quarter results after the close on November 5, the question is whether that cleaner model is producing the profit lift management promised. The bigger question is whether the patient trends underneath it are finally strong enough to stop the shrinking of the royalty base.
Wall Street expects earnings of $0.11 per share on revenue of $14.7 million. That would be a sharp jump from $0.02 a year ago, about 450% growth, on a 10% rise in revenue. The revenue figure is actually a touch below last quarter's $15.2 million, and that matters. Analysts are not counting on a top-line surge. They are betting that the shift to franchising lets far more of each dollar reach the bottom line. With the company posting a penny loss per share last quarter, the leap to $0.11 is the real hurdle in this report.
Management reiterated its full-year outlook in August rather than raising it. That outlook calls for system-wide sales of $519 million to $552 million, comparable sales between a 3% decline and a 3% gain, and consolidated adjusted EBITDA of $12.5 million to $13.5 million. The math is less comfortable than the reiteration suggests. Second-quarter system-wide sales were $128 million, down 3.7% from a year earlier. Holding that pace for a full year would leave the company short of the low end of the range. Comps improved from negative 4.2% in the first quarter to negative 2.8% in the second, and management said July ran slightly better still. Even so, the year-to-date figure sits near the bottom of the guided band. To keep the guidance credible, third-quarter comps need to keep narrowing toward flat.
Several of the tools behind that recovery should show up in this report. Patient retention reached its best level in more than five years, helped by the flexible Align One and Align Two membership plans. Management said those plans lifted conversion of lapsed patients by several hundred basis points. The $5 and $10 price increases reached more than 500 clinics in July without meaningful pushback, which should add a low-single-digit tailwind to comps for a full quarter. Continued gains in retention, plus a pricing benefit that does not drive away visits, would validate the self-help story. Signs that higher prices are hurting new-patient acquisition would challenge it. The same is true if heavier national marketing spending, which pushed selling and marketing expense up 40% last quarter, fails to translate into traffic.
Clinic count is the other pressure point. Management cut its 2026 opening target to 22 to 26 clinics from 30 to 35, and the network shrank to 941 locations from 960 at year-end as closures outpaced openings. Clearer evidence that the pruning is ending, or signs of a healthier development pipeline, would help. Without them, the longer-term Joint 3.0 ambitions around new channels and international expansion will be harder to take seriously.
The market has not given the company much credit. The shares are down about 11% since the last report while the S&P 500 was roughly flat. At $7.22, the stock sits well below its 200-day moving average of $8.63 and near the bottom of its post-earnings range of $6.79 to $8.91. That entire range sits below the prior quarter's trading band. Sentiment has warmed from clearly bearish heading into the last report to roughly neutral, so expectations look tempered rather than euphoric. In the end, the margin story is largely mechanical now that refranchising is essentially complete. What will decide whether the narrative holds is whether comps and system-wide sales finally stop shrinking.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-30 | |
| Jul-23 | |
| Jul-01 | |
| May-21 | |
| May-07 | |
| May-06 | |
| Apr-27 | |
| Apr-23 | |
| Apr-14 |
