IRhythm's Q3 Report Tests Whether Its 20% Growth Streak Can Survive A Cautious Street
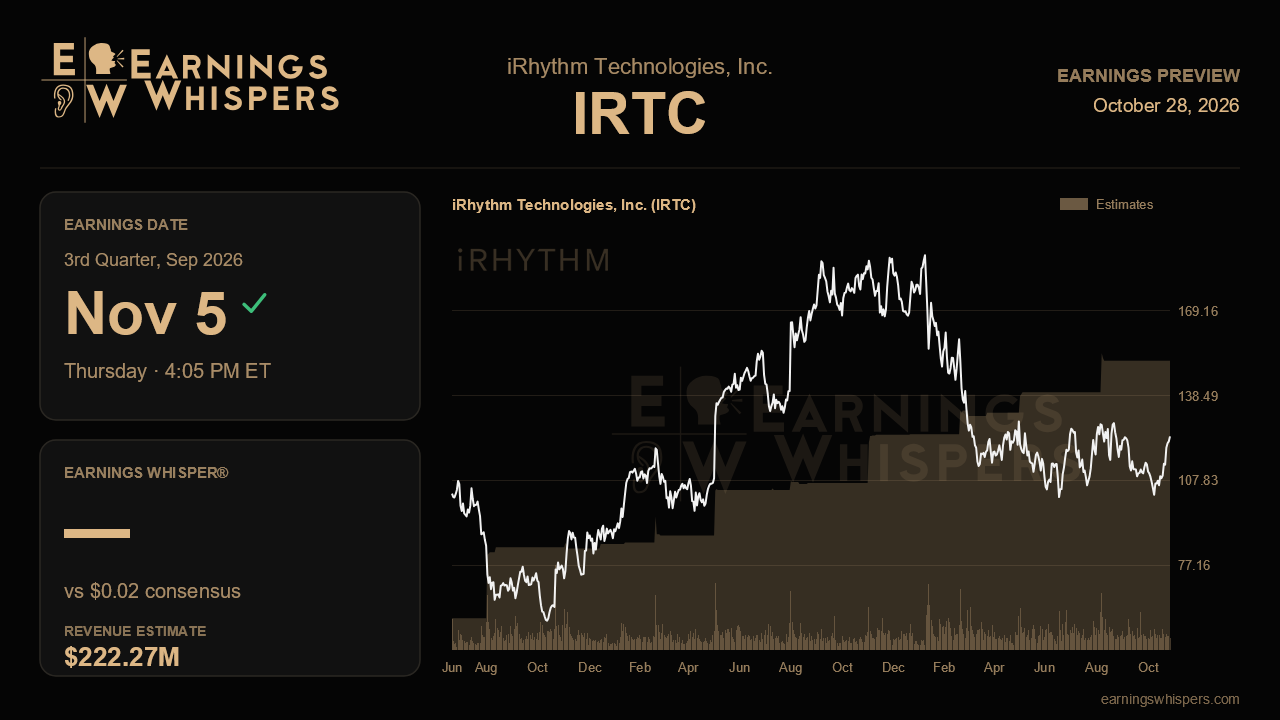
iRhythm Technologies heads into its third-quarter report with an odd mismatch. Management sounded more confident on its last call than at any point in the past year, raising profitability targets for a third straight time and announcing an expansion into the broader mobile cardiac telemetry market. The stock has not followed. Shares have slipped about 6% since that report while the S&P 500 was roughly flat, and the Street's numbers imply a noticeable slowdown. When the company reports after the close on November 5, the question is whether the momentum management described is real or whether consensus has correctly priced in a cooling quarter.
Analysts expect revenue of about $222.3 million, up 15.2% from a year ago. That would be solid growth for most medical device companies, but it would break a run of seven consecutive quarters above 20% and fall slightly below the $224.2 million posted in the second quarter. The earnings estimate sits at just $0.02 per share, compared with a $0.06 loss a year earlier. That is a big improvement in percentage terms, yet it looks modest next to the $0.58 adjusted figure from last quarter, which suggests either a less favorable cost picture or a different accounting basis behind the forecast. Either way, the bar on earnings does not look demanding. On revenue, management lifted its 2026 outlook to $880 million to $890 million from $875 million to $885 million, and the consensus of roughly $881.5 million sits near the bottom of that range. In other words, the Street has not fully bought into the raise.
That gap is the heart of the setup. A quarter that lands comfortably above $222 million, with growth closer to the 20% pace, would validate management's view that demand remains healthy. The key detail to examine is where volume growth comes from. New accounts drove roughly 45% of volume growth last quarter, down sharply from about 64% in the first quarter and 68% in the fourth quarter of 2025. Management attributed this to large customers signed in 2025 maturing into same-store volume, not to softer demand. If new-account contributions keep shrinking without strong same-store expansion, that explanation will start to look strained. Pricing is another swing factor, since management upgraded its view from roughly flat to a modest positive contribution for the year, and favorable final coverage decisions from several Medicare contractors plus a higher reimbursement rate in Japan should help support that.
Profitability is where the company has earned the most credibility. Adjusted EBITDA margin hit a record 19.3% in the second quarter with operating expenses essentially flat year over year, and full-year guidance now calls for 13% to 14%. Continued expense discipline would reinforce the path toward the 15% margin target management reaffirmed for 2027 on a combined basis. Investors should also look for updates on the Vital Connect acquisition, including regulatory review and integration planning, since combined 2027 guidance was deferred until the deal closes. Progress on the open FDA warning letter, any lingering effects from the June cybersecurity incident, and the rollout plan for the newly cleared third-generation algorithm, aimed at cutting technician review time roughly in half, round out the list.
Sentiment has improved, moving from about 21% bearish before the last report to roughly 7.5% bearish now, though it remains on the negative side. The stock trades at $123.75, just above its 200-day moving average and in the upper half of its post-earnings range of about $101 to $137, so it is neither breaking out nor breaking down. The deciding issue is whether iRhythm can show that growth is holding near 20% as its 2025 account wins mature. If it can, the conservative revenue consensus leaves room for upside; if growth fades toward the Street's 15%, the confident narrative from last quarter will need the Vital Connect story to carry more of the weight.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-15 | |
| Oct-13 | |
| Oct-05 | |
| Oct-02 | |
| Sep-24 | |
| Aug-26 | |
| Aug-17 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 |
iRhythm advances cardiac monitoring provision with $287.5m VitalConnect acquisition
IRTC
Medical Device Network
|
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-29 |
