Microchip's Upcycle Faces A Margin Test As Whisper Number Sits Above Its Own Guidance
Microchip Technology heads into its September-quarter report with a problem most chipmakers would gladly take: demand appears to be outrunning supply, and the bar for success has climbed as fast as the recovery itself. Three months ago management raised every major line of its outlook and guided gross margin above its long-term 65% model for the first time. It also warned that part of that margin came from items that will not repeat. That pairing of a confident guide and a caveat about margin quality is what makes this quarter worth close attention.
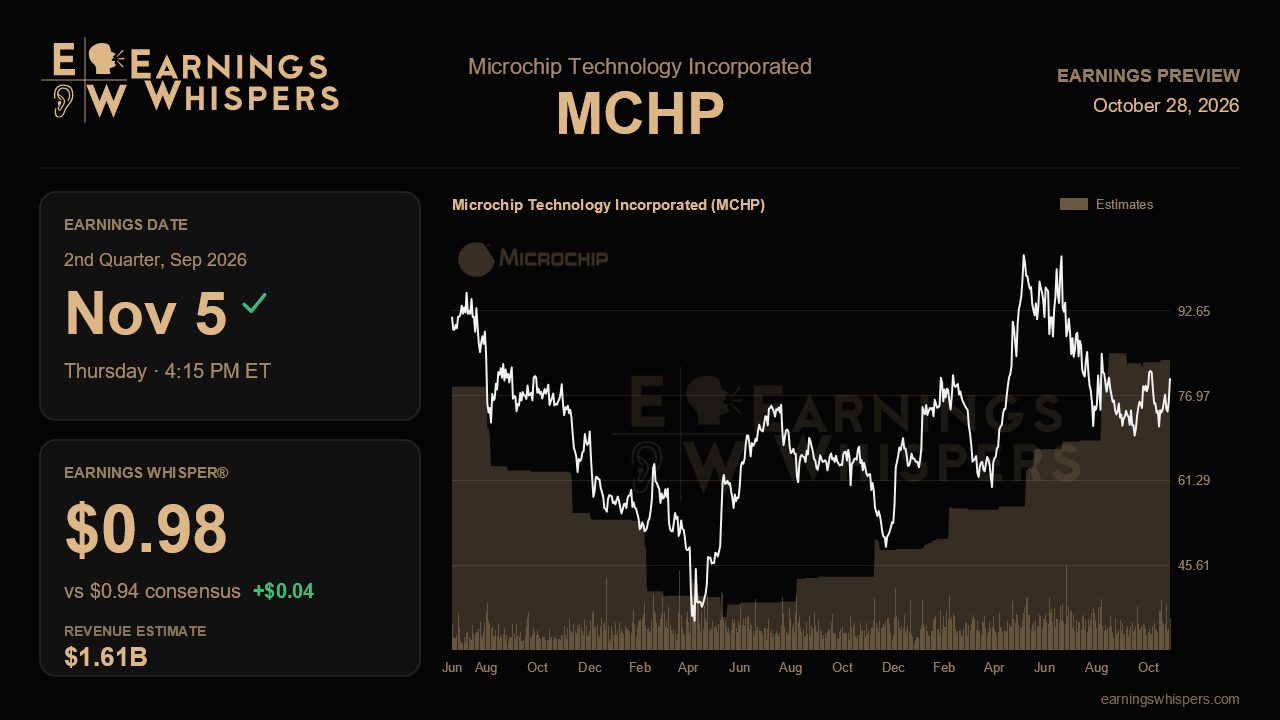
The Street expects non-GAAP earnings of $0.94 per share on revenue of about $1.61 billion. That would mean sales up roughly 41% from a year ago and earnings more than triple the $0.26 posted in the year-ago quarter. Management guided to $0.91 to $0.95 per share on revenue of $1.589 billion to $1.618 billion, so consensus sits near the top of both ranges. The Earnings Whisper of $0.98 goes further, landing above the high end of company guidance. In plain terms, simply hitting the midpoint would likely read as a disappointment. The market is looking for the kind of upside Microchip has delivered as guidance roughly doubled over three calls.
The most important operating test is gross margin. The guide of 66% to 67% compares with 63.8% in the June quarter, and management said a lumpy, very high-margin licensing quarter and a one-time distributor price-reserve benefit helped lift it. Executives also told analysts not to model further expansion. A print in the range would confirm the underlying improvement from mix, better factory utilization and lower inventory write-offs. Commentary on the December quarter matters even more. The broad price increase took effect in mid-August and early September, so its full benefit lands next quarter. That could offset the fading one-time items, but rising foundry and assembly costs are working against it. If management can guide December margins to hold near the mid-60s, the higher earnings base looks durable. A step down well below that would suggest the September quarter was a peak.
Demand looks less in doubt than supply. Last quarter brought the strongest bookings in about four years, a book-to-bill well above one and stretching lead times. Management also said capacity constraints had spread from isolated products to foundry nodes, substrates and test. Revenue upside is therefore capped by how much product Microchip can actually ship. Any update on the data center business is the other key signal. Management sized it at roughly $1 billion for calendar 2026, up 69%, and Gen6 switch and retimer design wins have climbed to 14. Progress toward that figure, along with early contributions from aerospace and defense, would show the growth story broadening beyond a cyclical rebound. Investors will also want to see continued debt reduction toward the sub-2.5 leverage target. Net debt still stands near $5.2 billion, and all excess cash is going to pay it down.
The stock has not priced in much enthusiasm. Shares are down 1.5% since the last report, slightly trailing the S&P 500. At about $80, they sit just above the 200-day moving average and roughly in the middle of the post-earnings range of $68.75 to $85.97, well below the prior quarter's high near $106. Sentiment has improved to modestly bullish from essentially neutral, a cautious shift rather than euphoria.
The main question is whether Microchip's margin gains reflect lasting earning power or a quarter flattered by one-time items. Earnings at or above the whisper, combined with a December outlook showing pricing and mix can replace those tailwinds despite supply limits, would keep the upcycle intact. A guide that leans heavily on caveats about capacity and costs would test it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 |
