Mobia Medical Faces A Proof Test: Can Losses Halve As Stroke-Recovery Sales Inch Higher?
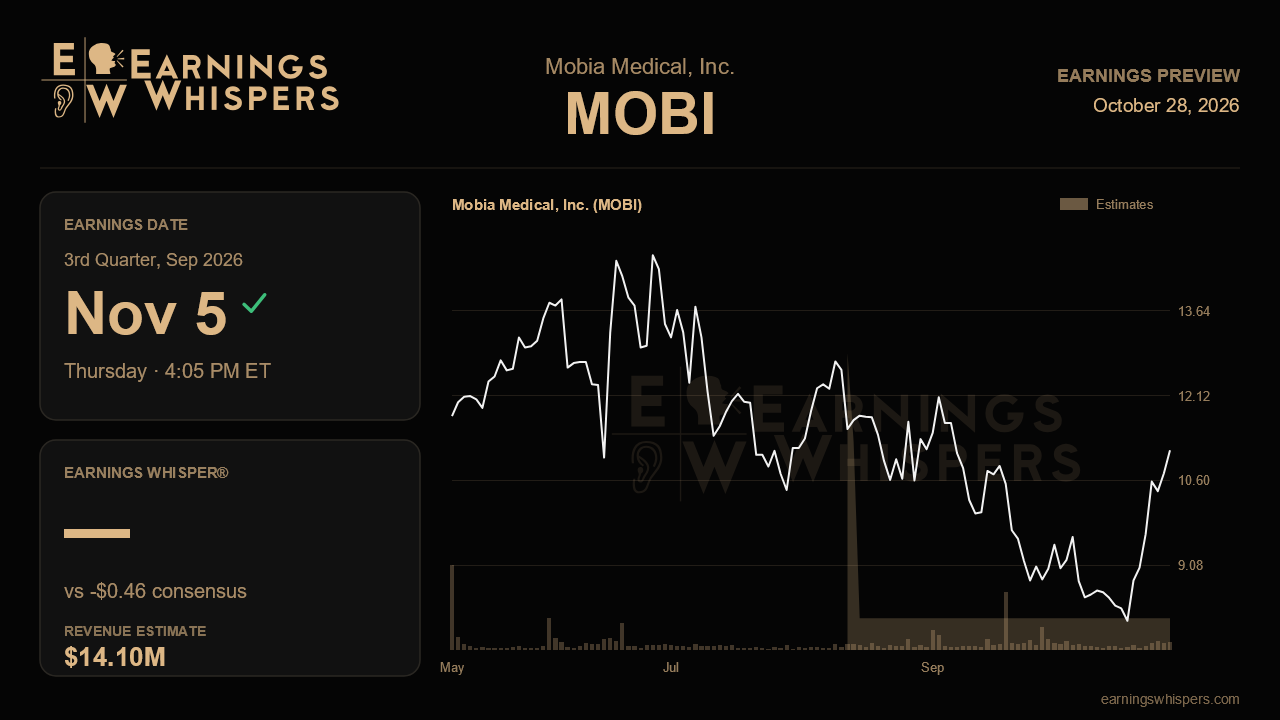
Mobia Medical heads into its September-quarter report with a striking gap between what Wall Street expects and what the stock market seems willing to believe. Analysts are penciling in a loss of $0.46 per share, roughly half the $0.88 loss the company posted last quarter, on revenue that is expected to rise only modestly. That combination puts the spotlight squarely on the cost side of the business. For a commercial-stage device maker selling stroke-recovery technology to survivors with serious motor impairments, the question is whether the path to sustainability is starting to come into view, or whether the Street is getting ahead of itself.
The revenue bar looks manageable on its face. Consensus calls for $14.1 million, up about 4% from the $13.5 million reported in the prior quarter. That is incremental progress rather than a breakout, and it suggests analysts are not counting on a sudden surge in adoption. Without a formal company outlook to anchor against, the sequential trend is the best yardstick available. A result comfortably above $14.1 million would hint that commercial traction is building faster than modeled. A figure that stalls near last quarter's level would raise doubts about how quickly the company can scale a product that depends on clinicians, patients and payers all getting comfortable with a newer approach to rehabilitation.
The earnings line carries more weight. Cutting the per-share loss nearly in half on just a few percent more revenue cannot come from top-line growth alone. Something else has to give, whether that is tighter operating expenses, better gross margins on each unit sold, a larger share count spreading losses more thinly, or the absence of costs that may have inflated last quarter's figure. Those explanations are not equally encouraging. Genuine operating leverage would validate the idea that the business model can work at scale. An improvement driven mainly by dilution or accounting timing would leave the underlying cash burn largely unchanged, and for a small company still building its commercial footprint, cash runway is never far from the conversation. The release and accompanying commentary should make clear which story is playing out.
The market has not been generous in the meantime. Shares have fallen 13.4% since the last report, trailing the broader S&P 500 by nearly 13 percentage points over a stretch when the index was essentially flat. Sentiment remains overwhelmingly negative at 86.3% bearish, though that is a modest thaw from the unanimous bearishness heading into the prior quarter. In other words, expectations are low but no longer universally so, which could give a solid print room to surprise while leaving little patience for another stumble.
The chart tells a more nuanced story than the headline decline. At $11.14, the stock sits well above its 200-day moving average of $7.60, a sign that the longer-term trend has improved substantially. It trades in the middle to upper portion of its post-earnings range of $8.03 to $13.52, having recovered meaningfully from that low without threatening the high. That range sits noticeably below the previous quarter's band of $10.34 to $15.29, underscoring that the stock has been repricing lower even as it holds well above its longer-term average.
Ultimately, this report hinges on whether the expected narrowing of losses reflects real operating discipline paired with steady commercial growth. If Mobia can show revenue edging past consensus while expenses and margins move in the right direction, the bullish case for a scalable stroke-recovery franchise gains credibility. If the loss improvement looks cosmetic or sales momentum flattens, the skeptics who have dominated sentiment will have fresh evidence on their side.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-15 | |
| Aug-28 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-03 | |
| Jul-21 | |
| Jul-15 | |
| Jul-14 | |
| Jul-02 | |
| Jun-02 |
