PAR Technology Faces An ARR Test After Two Guidance Raises Fail To Lift Shares
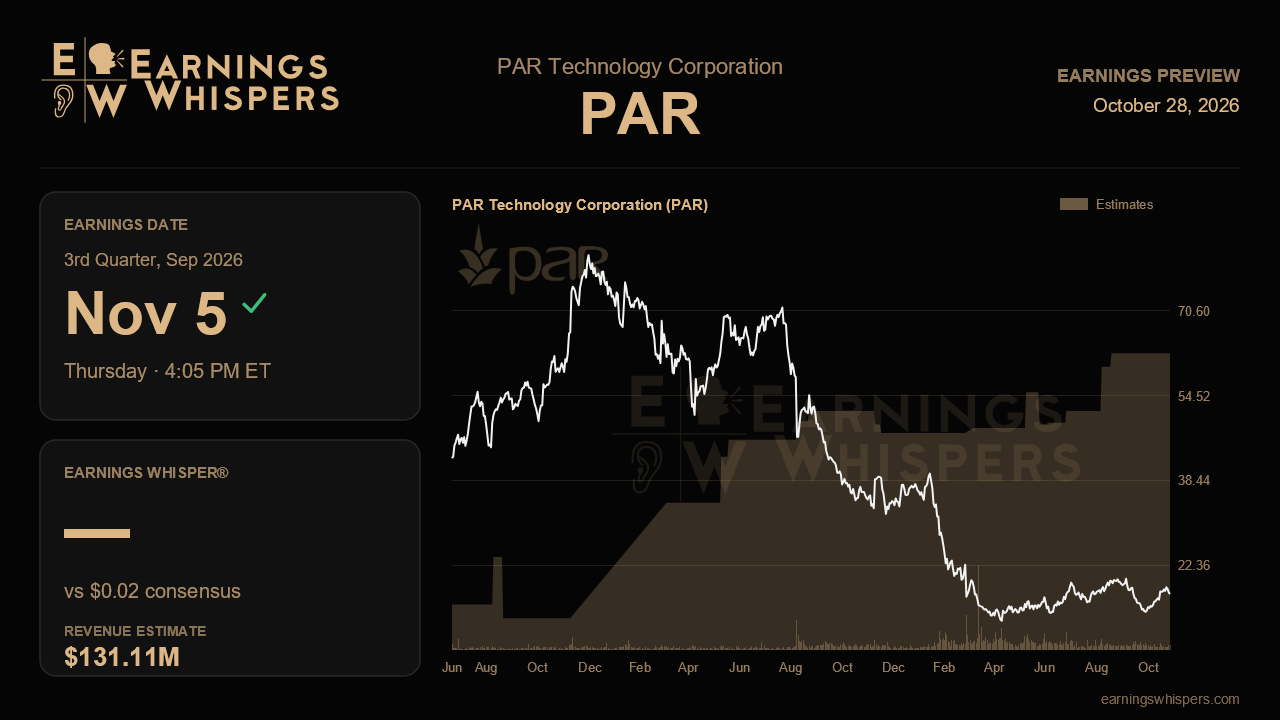
PAR Technology heads into its third-quarter report with an unusual disconnect. Management has raised its full-year outlook twice, profitability has climbed for six straight quarters, and free cash flow finally turned positive. Yet the stock has fallen 8.8% since the last report while the S&P 500 was essentially flat. The market appears to be asking whether a record hardware quarter flattered the second-quarter numbers. The question for November 5 is whether the recurring software engine can carry the story once that hardware boost fades.
Wall Street expects earnings of $0.02 per share, matching last quarter and a clear swing from the $0.13 loss a year ago. Consensus revenue of $131.1 million implies roughly 10% growth from $119.2 million. That is solid but not spectacular, and it would be a step down from the $133.4 million reported in the second quarter. Management guided to $128 million to $132 million, so analysts sit near the top of the range. A modest beat on the top line is therefore already priced in. Clearing the high end by a comfortable margin would say more about demand than simply landing inside it.
The sequential dip is by design. Hardware revenue hit $35 million last quarter, its best showing in more than a decade, helped by a tier-1 customer refresh that management said would not repeat. Hardware margins have also slid to about 20% because of tariffs and component costs, and the company now treats the low 20s as the norm, possibly into 2027. Softer hardware should ease the margin mix, but it puts more weight on subscription revenue and annual recurring revenue. ARR reached $338 million in the second quarter, up 17%, or about 12% organically. Management said second-half ARR additions should be meaningfully larger than the first half's gain of roughly $22 million. That makes the third-quarter ARR figure the single most important number in the release. A solid step-up toward the mid-$340s or higher would support the back-half thesis. A flat or sluggish print would raise doubts about the timing of the Burger King and Papa John's rollouts on which that acceleration depends.
Profitability is the second checkpoint. Adjusted EBITDA came in at $14.3 million last quarter, or about $13 million excluding a one-time hardware project. That compares with a guide of $9.5 million to $11.5 million. The raised full-year target of $50 million to $53 million implies the second half must roughly match the second-quarter pace without the hardware help. Holding operating expenses near the 38% of revenue achieved last quarter would show the reorganization savings are structural rather than seasonal. Subscription margin is another tell after it slipped to 65.1% on the Bridge acquisition mix. Management expects that drag to reverse, and confirmation would strengthen the operating leverage story.
On the product side, PAR Intelligence jumped to about 37,000 live restaurant and retail sites, against a 50,000-site target for the year. Monetization is not expected until 2027, so steady adoption matters more than revenue here. Progress on the three named tier-1 deals still being bid, and further ordering wins against the largest legacy provider, would add weight to the pipeline narrative.
Sentiment remains bearish, only slightly less so than before the last report. The shares, at $16.88, sit below their 200-day moving average and in the middle of a volatile $13.24 to $20.06 post-earnings range. That leaves room in either direction. Ultimately, the report hinges on one issue: whether ARR growth visibly accelerates as hardware normalizes. If it does, the two guidance raises look conservative rather than lucky. If it does not, the market's skepticism will have found its evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-07 | |
| Sep-30 | |
| Sep-16 | |
| Sep-15 | |
| Sep-02 | |
| Sep-01 | |
| Aug-18 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-22 | |
| Jul-15 |
