AVITA Medical's Q3 Must Justify A 168% Rally As Cash Breakeven Approaches
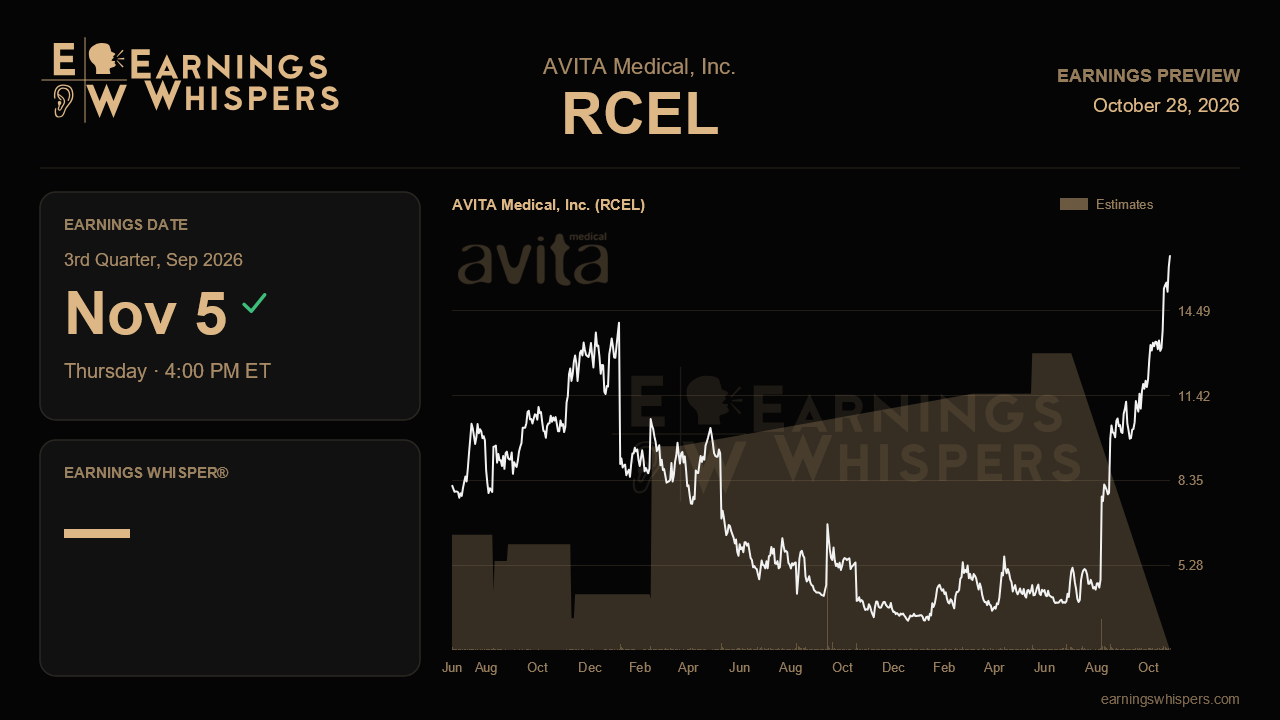
AVITA Medical enters its third-quarter report with a very different reputation than it had three months ago. The regenerative skin company raised its full-year revenue outlook for the first time, set its first cash flow breakeven target, and watched its stock more than double. The November 5 report, due after the close, is the first test of whether that turn into a growth-and-margin story holds up now that the market has paid for it.
The best yardstick is management's own math. AVITA now expects 2026 revenue of $86 million to $89 million, up from a prior range of $80 million to $85 million. That implies 20% to 24% growth. The first half produced about $41 million, so the second half needs roughly $45 million to $48 million, or about $22.5 million to $24 million per quarter. That is a clear step up from the second quarter's record $21.7 million, which was the company's first quarter above $20 million. The published full-year consensus of $81.25 million sits below even the low end of the new range, which suggests many estimates have not caught up. A third-quarter figure around $23 million, compared with $17.1 million a year ago, would keep the raised range credible. A figure close to the second quarter's level would push most of the burden onto the fourth quarter. On the bottom line, the year-ago loss of $0.46 per share and the latest quarter's loss of $0.25 show how quickly losses have narrowed.
The operating details matter more than the headline. U.S. ReCell volume topped 2,600 units last quarter as reimbursement steadied across all seven Medicare administrative contractors. Continued unit growth would confirm that pricing stability is turning into steady usage. COHELIX reached $1.7 million, with about 55 hospital value-analysis reviews in progress and 10 to 15 clearing each quarter. That pipeline should keep converting into revenue. International ReCell Go rose 26% sequentially and deserves a look as well. Gross margin firmed to 81.9%, helped by ReCell's roughly 86% margins. Holding near that level while lower-margin COHELIX and the still-tiny Permaderm grow would show the mix shift is manageable.
Cash is the biggest swing factor. Net cash use fell to $3.2 million in the second quarter from $9.9 million in the seasonally heavy first quarter. However, the cash balance ended at just $11.1 million. Management promised breakeven and positive cash generation starting in the fourth quarter, so the third quarter should show burn trending close to zero. A rebound in spending would quickly raise questions about funding. An additional $10 million debt tranche becomes available once trailing revenue reaches $85 million, a threshold the company likely approaches but probably does not clear this quarter.
Management may also be asked about January 2027. CMS proposed national values for the new Category 1 CPT codes, replacing regional pricing with a single national framework. That is a long-term positive, but moving from eight legacy codes to four new ones could cause a temporary dip in billing. Any guidance on 2027 timing or physician readiness will be closely parsed.
Sentiment has swung from essentially neutral to clearly bullish. The stock has gained roughly 168% since the last report, while the S&P 500 was flat over the same period. Shares at $16.08 sit far above the 200-day average of $6.30 and are pressing against the post-earnings high of $16.13, a level that dwarfs last quarter's $3.73 to $5.75 range. That positioning leaves little cushion. Meeting the raised outlook may not be enough on its own. The narrative stays intact if AVITA shows revenue tracking toward the upper part of its range and cash burn shrinking enough to make fourth-quarter breakeven look like a near-certainty rather than a hope.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-20 | |
| Sep-02 | |
| Aug-18 | |
| Aug-09 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Jul-14 | |
| Jun-18 | |
| May-17 | |
| May-15 | |
| May-14 | |
| Apr-30 |
