NuScale's Third-Quarter Report Hinges On TVA Clarity As Shares Sink Near Lows
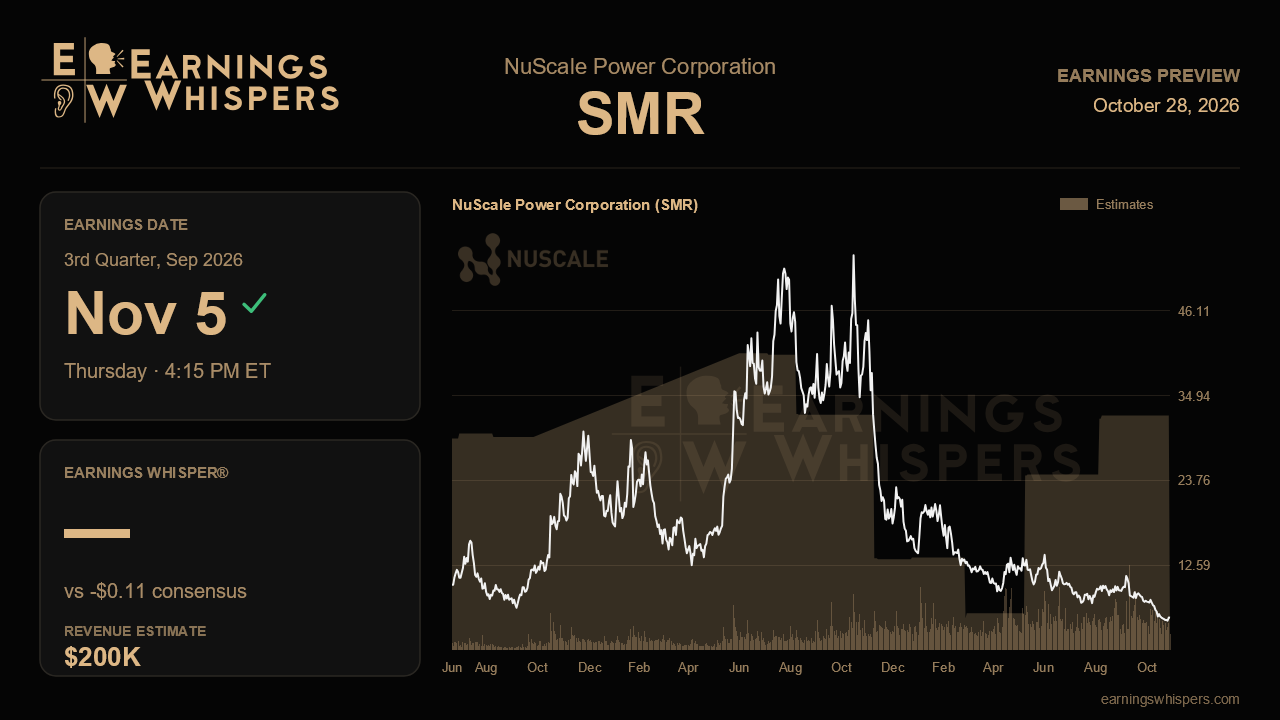
NuScale Power heads into its third-quarter report with a balance sheet that has never looked stronger and a share price that has rarely looked weaker. The company has built a cash cushion that management now discusses in terms of capital allocation rather than survival. Yet the stock has fallen about 39% since the last report while the S&P 500 barely moved. That gap reflects a simple frustration. The one event that turns NuScale from a well-funded engineering shop into a commercial reactor vendor, a definitive power purchase agreement with the Tennessee Valley Authority, still has not arrived.
The numbers themselves will say little about that question. Analysts expect a loss of 11 cents a share on revenue of roughly $200,000, when the report lands after the close on November 5. Revenue would be down about 98% from the $8.2 million booked a year ago, and that collapse is not a surprise. It is the predictable result of RoPower front-end engineering work rolling off, plus a Fluor pricing adjustment that pushed power-plant segment revenue negative last quarter. The expected 94% improvement in per-share loss from the year-ago figure of $1.85 looks dramatic, but the more relevant comparison is the 13-cent loss posted last quarter. On that basis, the Street is looking for a modestly narrower loss, not a turnaround. Management has offered no formal guidance to measure against, so the call commentary will carry more weight than the income statement.
The first thing to check is operating expenses. Last quarter, management acknowledged that engineers who had been charged to cost of sales on Romanian work were shifting into operating expenses, nudging spending above the historical band of roughly $41 million to $44 million a quarter. With almost no revenue to absorb costs, every dollar of opex flows straight to the loss line. A figure that stabilizes would suggest the company is managing the gap between projects. Continued creep would raise questions about how long NuScale intends to carry a fully staffed deployment team while waiting for an order. The liquidity figure matters too, both its size relative to the $1.9 billion cited in August and any sign of how management plans to deploy it.
The narrative test, though, is commercial. A binding TVA agreement was once targeted for the end of 2025, and on each call since then management has said the company is ready to move. Any concrete timetable, or better yet a signed contract, would validate the patience the company has asked for. Additional evidence could come from progress on the US-Japan and South Korea investment frameworks, where InterOne remains the only named developer. Updates on Romania, now dependent on a new government and Fluor's prime contract, would also help. Investors may also look for tangible follow-through on process heat and dry-cooling interest, particularly in water-constrained Texas. Supply-chain milestones would reinforce the readiness story. These include the 12 modules in production at Doosan, Framatome fuel work and instrumentation and controls running ahead of schedule. On their own, though, they cannot substitute for a customer.
Sentiment has softened from deeply negative to merely negative, improving from roughly 28% bearish to about 19% bearish, even as the stock slid. Shares now trade at $5.67, about half their 200-day moving average of $11.03. That leaves them just above the post-report low of $5.20 and well beneath the prior quarter's $7.21 floor. Expectations, in other words, are depressed, which lowers the bar for a positive reaction but also shows how little credit the market now gives to readiness without orders.
The central issue is whether NuScale can show that the TVA path is narrowing toward a signature rather than drifting further. A cleaner expense trajectory would help at the margin. But until management can point to a dated, binding commitment, the company's fortress balance sheet will keep being read as a waiting room rather than a launchpad.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 min | |
| 6 hours | |
| Oct-28 | |
| Oct-23 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-11 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 |
