BeautyHealth's Rental Program Gets Its First Test As Shrinking Revenue Meets Debt Payoff
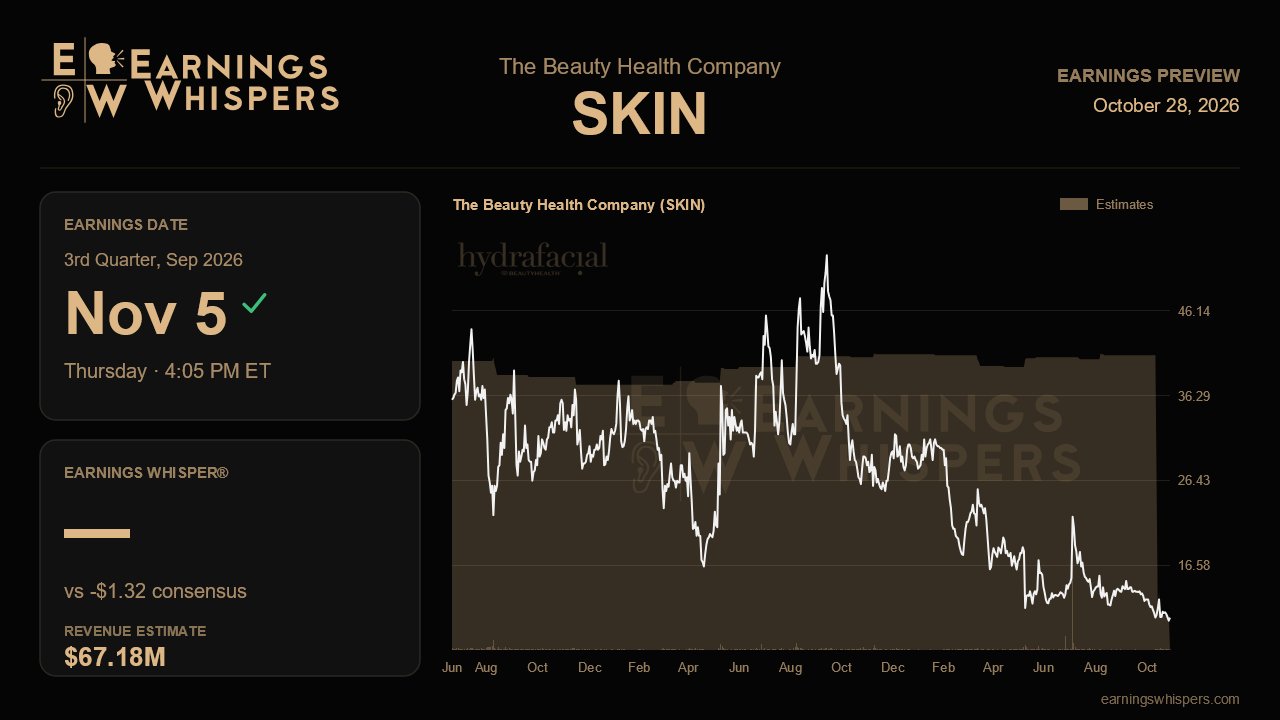
For several quarters, BeautyHealth has delivered the same split-screen result: tight cost control and better margins on one side, a slowly eroding top line on the other. The third-quarter report, due after the close on November 5, is the first look at whether management's newest fixes, led by a U.S. device rental program launched in early August, can start closing that gap. It also arrives just after the company was scheduled to repay roughly $103 million of convertible debt in October, so the balance sheet will look very different this time.
Wall Street expects revenue of about $67.2 million, a 5% decline from $70.7 million a year ago. That sits inside management's $65 million to $70 million guidance range, a touch below the midpoint, and well under the roughly $70.2 million analysts were penciling in when the guidance first came out. Analysts have already marked their models down toward the cautious end. A 5% drop would still be a contraction, but a slightly milder one than the 7.8% slide in the second quarter. The consensus loss of $1.32 per share, and the eye-popping implied year-over-year decline, should be treated carefully. The stock moved from a range of roughly 55 cents to $1.22 last quarter into double digits, which points to the reverse split shareholders were asked to approve in September. Per-share comparisons with prior periods are therefore distorted, and revenue, margins and cash are the cleaner measures.
The operating questions come straight from last quarter's call. Equipment sales were the weak spot, with delivery systems revenue down 18.4% and only 770 units placed against 957 a year earlier. Management blamed cautious capital spending by clinics and rising price competition at the low end. The rental program is meant to remove that upfront cost barrier. It had less than two months to contribute, so a dramatic turnaround is unlikely. Still, early signs of better placement trends or growth in the installed base, which reached 36,516 systems in June, would support the strategy. The bigger concern may be consumables. That recurring revenue stream fell for a second straight quarter on soft treatment activity. A third decline would suggest the problem is weak usage across the existing base, not just reluctance to buy new machines, and that is harder to fix with financing.
On profitability, the bar has been set deliberately low. Management raised full-year adjusted EBITDA guidance to $39 million to $46 million after a $17 million second quarter. It also warned that second-half EBITDA would come in around $17 million, compared with roughly $25 million in the first half. The reasons are higher R&D and commercial spending, plus adjusted gross margin easing from near 72% toward about 68% as lower-margin Cindeo devices make up more of the mix through rentals. Some margin slippage is expected. Margins falling faster than that, without matching sales progress, would be the warning sign. Updates on Skin Stylus, which grew about 50% last quarter, the June relaunch of HydroSculpt and KeraViv, and the booster slated for the fourth quarter will help show whether the product pipeline can offset weakness in the core HydraFacial business.
The market has not been patient. Shares are down about 19% since the last report while the S&P 500 was essentially flat. At $10.49, the stock trades near the bottom of its post-earnings range of $9.89 to $15. Sentiment remains modestly positive but has cooled from the prior quarter. Investors are paying for top-line proof, not more cost savings.
That is the central issue. With the convertible retired and cash expected to fall to about $100 million by year-end, BeautyHealth has less room for error. The full-year revenue range has already been trimmed twice, from $285 million to $305 million down to $280 million to $290 million. If the company holds that range and shows that placements and consumables are stabilizing, the turnaround story stays intact. A third cut would suggest the cost discipline is only buying time.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-09 | |
| Oct-06 | |
| Oct-01 | |
| Sep-15 | |
| Sep-08 | |
| Aug-26 | |
| Aug-07 | |
| Aug-06 | |
| Jul-21 | |
| Jul-07 | |
| Jun-02 | |
| May-07 | |
| Apr-29 |
