Savers Value Village Must Prove Its Margin Story As Stock Slides Toward Post-Earnings Lows
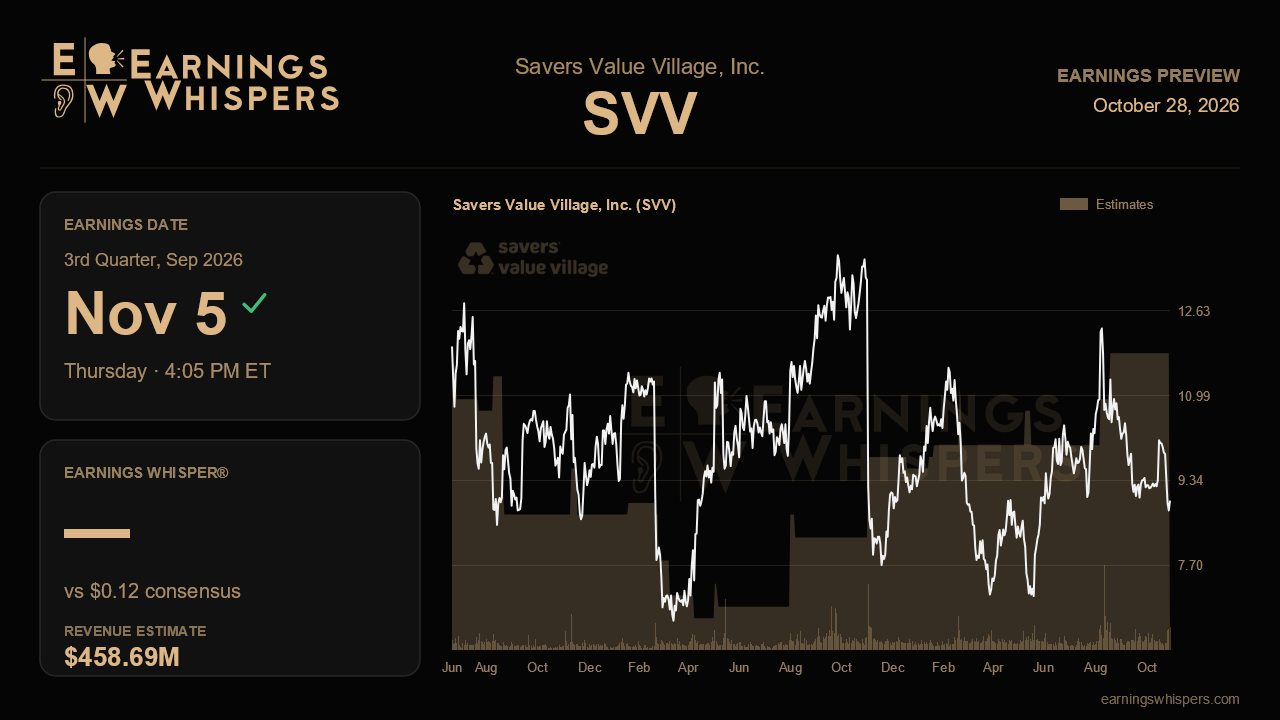
Three months ago, Savers Value Village gave investors almost everything they could reasonably ask for: a third straight quarter of year-over-year adjusted EBITDA growth, higher low ends across its full-year outlook, a new pricing platform called Thrift IQ, and a firm timeline for returning to high-teens EBITDA margins. The market briefly cheered, then reversed hard. The stock has fallen 21.5% since that report while the S&P 500 was essentially flat. That leaves the thrift operator heading into its third-quarter release on November 5 with an optimistic management narrative and a deeply skeptical tape.
The Street is not asking for much on the bottom line. Consensus calls for earnings of $0.12 per share, unchanged from a year ago, on revenue of $458.7 million, up 7.4%. That is respectable top-line growth paired with flat profits. It also reflects management's own warning that third-quarter adjusted EBITDA would land modestly below the second quarter's $75 million, because eight store openings pushed pre-opening costs into the period. For the full year, revenue consensus of $1.78 billion sits squarely in the middle of the $1.77 billion to $1.79 billion range. On earnings, the picture is murkier. The latest outlook has been framed as 42 to 47 cents per share, which would put the 49-cent consensus above it. Management's adjusted net income outlook from the last call, however, was 47 to 53 cents. Measured that way, the Street sits in the lower half of the range. Clarity on which bar the company is measuring itself against would help.
The operating question starts in the United States, where comparable sales rose 6.6% last quarter after 6.4% in the first quarter. The U.S. business has now posted seven straight quarters of mid-single-digit growth, driven by both bigger baskets and more transactions. Management already flagged that comps should moderate as comparisons toughen. A modest step down into the mid-single digits would be consistent with that message. A sharper slowdown would undercut the idea that demand is broad-based rather than borrowed from easy laps. Canada is the other half of the equation. Comps there were just 0.8% last quarter, including an Easter benefit, and management is planning around roughly flat results as lower-income shoppers stay stretched. Investors should look for whether segment margin, which expanded more than 300 basis points in each of the first two quarters, can keep rising without help from sales.
The margin story is where the narrative is either validated or exposed. Cost of goods as a share of sales fell 170 basis points last quarter, helped by onsite donations reaching nearly 85% of supply. Thrift IQ, live in 58 stores, was credited with roughly 100 basis points of faster gross profit dollar growth than non-pilot stores, along with halving grader training time. Evidence that the rollout is widening, and that the gross margin gains are holding, matters more than the headline EPS figure. The same goes for the 2025 store class, more than half of which was already four-wall profitable. That is the foundation for the promised 50 to 100 basis points of annual margin expansion starting in 2027. Lower interest expense, now guided to about $48 million after a term-loan repricing, offers a cushion below the operating line.
Sentiment has swung sharply. Bearish readings now stand at 65.5%, compared with 11.8% before the last report. At $8.95, the stock trades below its 200-day moving average of $9.43 and just above its post-earnings low of $8.75, far from the $12.69 peak. With an Innovation Day also slated for early November, management has a ready stage to make its case.
Ultimately, this report hinges on whether the company can absorb a softer quarter on paper while showing that the margin engine is intact. A reaffirmed full-year EBITDA range, stable U.S. comps and further Thrift IQ progress would suggest the selloff has run ahead of the fundamentals. Any trim to the outlook or slippage in gross margin would tell investors the market's doubts were justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-08 | |
| Sep-18 | |
| Aug-13 | |
| Aug-11 | |
| Aug-11 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| May-06 | |
| May-06 |
