Starling Oncology's Q3 Test: Can Onboarding Costs Stay Contained Ahead Of Its Fourth-Quarter Expansion?
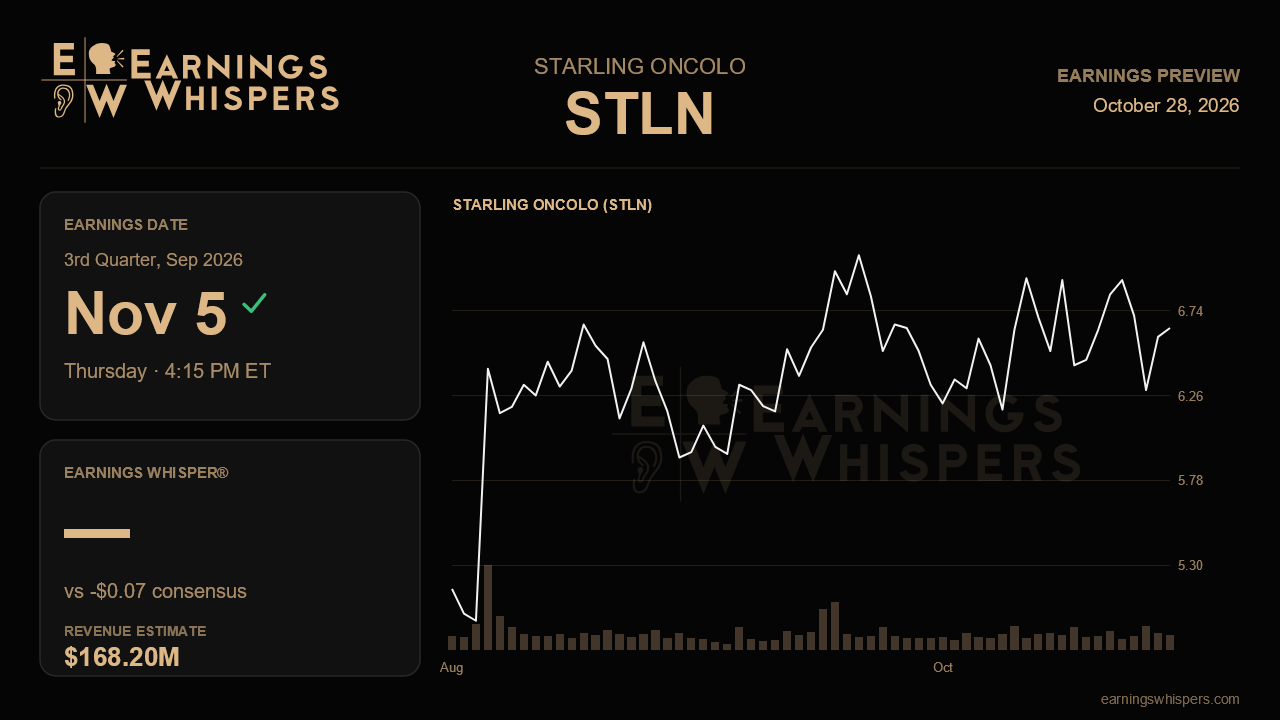
Starling Oncology heads into its third-quarter report with a story that looks better on paper than it may in the near-term numbers. Last quarter management raised full-year revenue and gross profit targets, completed a refinancing and announced its first delegated contracts outside Florida. It also told investors to expect a soft quarter now, guiding third-quarter adjusted EBITDA to just $0.5 million to $1.5 million while roughly 230,000 new California members come aboard. The report due after the close on November 5 is therefore less about a headline beat and more about whether the promised growth is arriving on schedule and at a manageable cost.
The Street expects a loss of 7 cents a share on revenue of about $168.2 million. That compares with a loss of 8 cents and revenue of $161.3 million in the second quarter, implying roughly 4% sequential growth. The more telling comparison is with the raised full-year revenue target of $650 million to $670 million. First-half revenue came to about $309 million, so the company needs roughly $341 million to $361 million in the back half. A $168 million third quarter would leave a fourth quarter of about $173 million to $193 million to reach the range. That looks achievable, especially since the Nevada and Oregon contracts, worth about $50 million in annualized capitated revenue, and the delayed Florida statewide payer contract are all set to start in the fourth quarter. Still, anything much below consensus would put more weight on a single quarter.
Margins are the main swing factor. Consolidated medical loss ratio jumped to 85.5% from 71% a year earlier, and management said it could range from 80% to 90% over the next year as delegated lives ramp. A reading near the low end would suggest the California onboarding is going smoothly. One drifting toward 90% would raise questions about whether the narrowed EBITDA range of $2 million to $7 million for the year is still realistic. Specialty pharmacy, which drove last quarter's upside with a 21.6% gross margin, is expected to slip back toward the high teens as temporary procurement benefits fade. A modest pullback would be fine. A sharper one would remove the cushion that made the gross profit raise possible. Patient services gross profit, which fell to $2.1 million as the company hired clinicians ahead of new launches, should start to show that this spending is being absorbed.
Cash flow is the other pillar. Free cash flow of $12.5 million in the second quarter brought the year-to-date total to $9.5 million, already inside the $5 million to $15 million full-year target. With the OrbiMed term loan pushing maturities out to 2031, the balance sheet is no longer the near-term concern. Another quarter of positive cash generation, even a small one, would show that the turnaround is not just an accounting improvement. Investors should also look for early signs that the Starling Nexus provider portal and Part D e-prescribing integration are helping pharmacy volume.
Sentiment has moved from neutral to clearly bullish since the last report, though the stock is up only 1.7% over that span, slightly ahead of the S&P 500. At $6.64 it sits above its 200-day moving average of $6.38 and in the middle of its post-earnings range of $5.76 to $7.13. That points to growing confidence rather than a crowded trade.
The central question is whether the third quarter looks like a planned pause or the start of margin slippage. If revenue lands near consensus, MLR holds inside guidance and management confirms that the fourth-quarter contracts and its roughly $300 million 2027 capitated revenue target remain on track, the expansion story stays intact. If onboarding costs run above plan, the cautious EBITDA guidance will look like a warning rather than a precaution.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-01 | |
| Aug-24 | |
| Aug-17 | |
| Aug-06 | |
| Aug-05 | |
| Aug-03 | |
| Jul-27 | |
| Jul-07 | |
| May-26 | |
| May-13 | |
| May-07 | |
| May-06 | |
| Apr-27 |
