Workiva's Margin Surge Lifted The Stock 37%; Now Growth Must Hold Up As Deals Slow
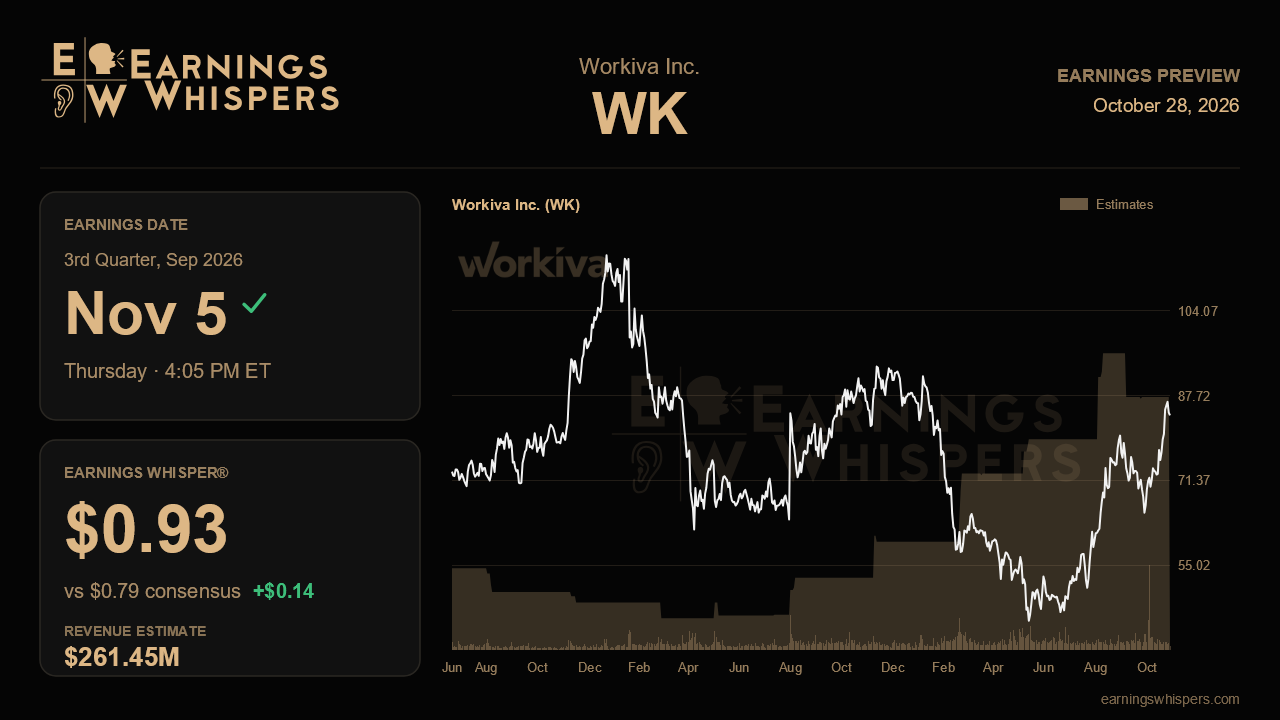
Workiva enters its third-quarter report with an unusual problem for a software company that spent years being told to show profits: it has already delivered them, ahead of schedule, and the stock has been richly rewarded. Shares are up about 37% since the last report while the S&P 500 slipped slightly. The open question is whether the company can keep proving that faster profitability is not costing it growth momentum, at a time when top-line growth is cooling and management has acknowledged that customers are taking longer to sign.
Wall Street expects non-GAAP earnings of $0.79 a share on revenue of about $261.5 million. That revenue figure sits inside management's $260 million to $262 million guidance, slightly above the midpoint, and implies growth of roughly 16.6% from the year-ago quarter's $224.2 million. Consensus EPS, however, lands right at the bottom of the company's $0.79 to $0.82 range, a cautious stance toward a management team that has beaten its own margin targets repeatedly. The Earnings Whisper of $0.93 sits well above both consensus and the top of guidance, which tells you the informal bar is considerably higher than the published one. A result at the high end of guidance may technically beat estimates and still feel ordinary.
That elevated bar is the product of a steady escalation. Workiva opened the year guiding to a 15.0% to 15.5% non-GAAP operating margin, lifted that to 16.0% to 16.5% after the first quarter, and then raised it to about 18% last quarter, reaching its 2027 target a year early. Free cash flow margin guidance climbed in step to roughly 21%. Full-year EPS guidance now stands at $3.38 to $3.39. Revenue guidance, by contrast, has only inched higher, to $1.040 billion to $1.044 billion. The pattern is clear: profitability is doing the heavy lifting, and another meaningful margin upgrade would validate the operational overhaul under the company's new sales leadership. A pause in those raises would not be alarming on its own, but it would shift the story back toward growth, where the evidence is more mixed.
On that front, the numbers to scrutinize are subscription growth and net revenue retention. Subscription growth slowed to 19% last quarter from 21% in the first quarter and 23% a year earlier, partly because a currency tailwind of one to two points faded. Net retention eased to 111%. Those trends are now unaided by foreign exchange, so another step down would be harder to explain away. Management also flagged, for the first time, more approvers and heavier legal review on deals. If that friction is spreading, it should show up in slower large-contract growth, which ran at a robust 33% to 34% last quarter for customers above $300,000 and $500,000. Continued strength there, alongside rising multi-solution adoption from 76% of revenue, would suggest the scrutiny is a speed bump rather than a wall.
The newer catalysts deserve attention, too. The MCP Gateway, purpose-built regulatory agents and premium tiers carrying price uplifts of more than 20% are early, but any color on attach rates would help investors judge whether AI can reaccelerate growth. Capital markets work tied to high-profile listings and the fast-scaling fund reporting business offer further evidence of new demand.
Sentiment has warmed modestly, with the bearish reading easing to 9.2% from 15.3% a quarter ago, and the stock trades about 33% above its 200-day moving average and roughly 3% below its post-earnings high, close to testing that level. That positioning leaves little cushion. The report ultimately hinges on whether Workiva can show that subscription growth and retention are stabilizing without currency help while margins keep expanding. Do both, and the profitability story graduates into a durable compounding story. Deliver margins alone, and a richly valued stock may find that efficiency is already priced in.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-06 | |
| Oct-01 | |
| Sep-15 | |
| Sep-14 | |
| Aug-25 | |
| Aug-25 | |
| Aug-17 | |
| Aug-11 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-29 | |
| Jul-06 |
