Westrock Coffee's Rally Puts Its Unraised EBITDA Guidance To The Test
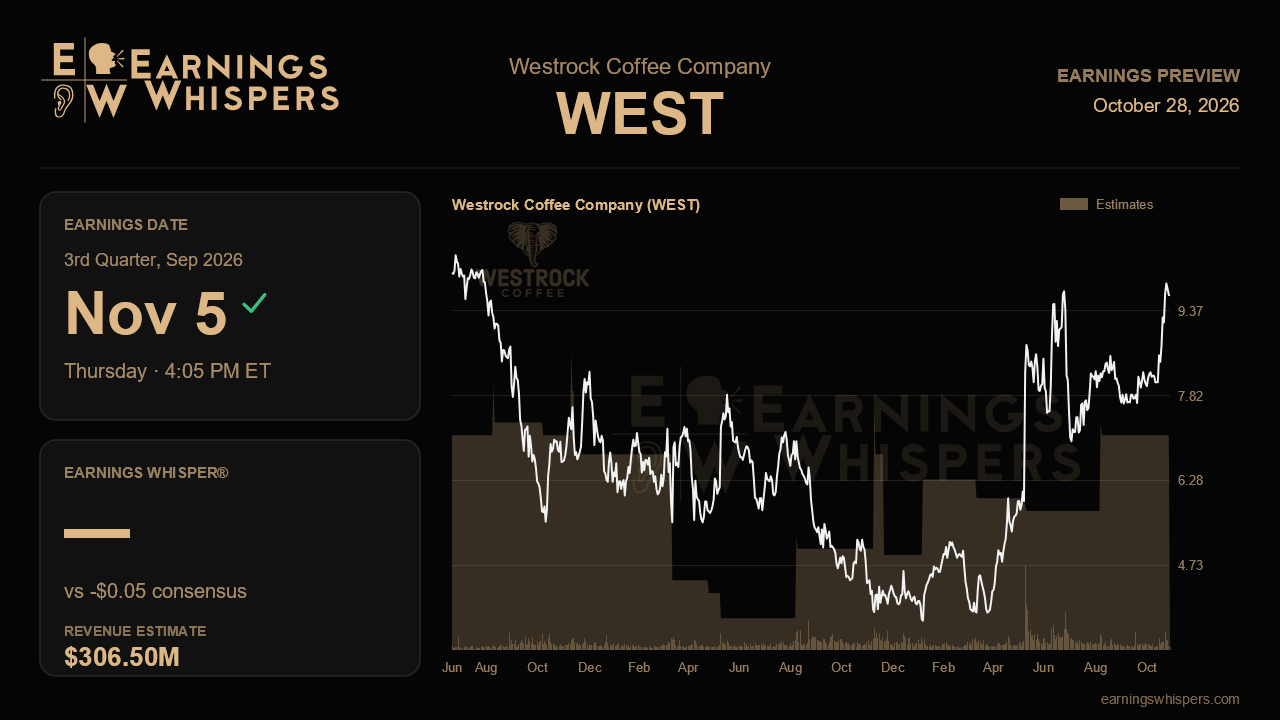
Westrock Coffee heads into its fiscal third-quarter report with a dynamic that rarely shows up in a turnaround story: management may have deliberately undersold its own year. Three months ago the company turned free cash flow positive a full quarter ahead of schedule, posted a fifth straight quarter of EBITDA growth and said it was running roughly 10% ahead of its internal plan. It still declined to raise its $90 million to $100 million adjusted EBITDA target for fiscal 2026, and executives signaled they intend to clear that range comfortably. The shares have climbed 38% since then, so the market has largely accepted that claim. The question on November 5 is whether the numbers match it.
The headline consensus figures are muted. Analysts expect a loss of $0.05 per share, unchanged from a year ago, on revenue of about $306.5 million. That would be roughly flat with the prior quarter's $305.7 million and down 13.6% from the $354.8 million reported a year earlier, a quarter that still included the single-serve cup customer Westrock later lost to industry consolidation. The top-line decline matters less than it looks. In this phase of the story, the main test is profit and cash conversion at the Conway plant, not sales growth.
The guidance math sets the bar. First-half adjusted EBITDA was $47.3 million, so the low end of the full-year range requires only about $21 million per quarter in the back half, roughly matching the record $21.3 million earned in the second quarter. To support the suggestion that it will beat the range by a wide margin, Westrock likely needs a third-quarter figure clearly above that run rate. A result in the mid-$20 millions would back up management's confidence and could lead to the guidance raise it held back last time. A result that is flat or lower would suggest the conservative stance was more cautious than strategic.
Several operating threads will show whether the improvement is broadening. Management described incremental canned-format volume from both existing and new customers at Conway, business that should add profit without new capital spending, so evidence of better utilization there is the cleanest proof of operating leverage. The single-serve business needs watching too. Growth excluding the departed customer slowed to 9% last quarter from 31% the quarter before, and a full replacement is not targeted until the end of 2027. Further deceleration would weaken the replacement story. The sourcing and trading segment should also rebound if last quarter's EBITDA dip really reflected shipment timing. Gross profit fell even as EBITDA rose, owing to Conway depreciation and a mark-to-market hit, so a cleaner gross line would help. Free cash flow staying positive and leverage moving below 3.36x would extend the deleveraging streak to six quarters. Those results would also give weight to management's early talk of capital returns and refinancing over the next year to 18 months.
Expectations have moved higher. Sentiment readings, while still only mildly bullish, have more than doubled since the last report. The stock, at $9.67, sits well above its 200-day moving average of $6.82 and within about 3% of its post-earnings high of $9.96, testing a breakout with last quarter's $10.19 peak just above. That positioning leaves less room for a merely in-line print than there was in August.
The central issue is whether Westrock can produce third-quarter EBITDA and cash flow strong enough to make its unraised guidance look conservative. If it does, the turnaround becomes a story about returning cash to shareholders. If it doesn't, a stock priced for upside will have to settle for a business that simply met its plan.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-21 | |
| Oct-15 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Jul-20 | |
| Jun-30 | |
| May-07 | |
| Apr-16 | |
| Mar-10 | |
| Mar-10 | |
| Mar-10 | |
| Feb-26 | |
| Feb-17 |
