TransMedics Faces A Margin Test As PAD Aviation And Kidney Spending Hit Results
TransMedics enters its third-quarter report with an odd mismatch. Revenue is still growing at a pace most medtech companies would envy, yet the stock trades as though something is broken. The business told investors last quarter that it would deliberately spend its way through 2026, and this report is the first full quarter to show what that choice costs.
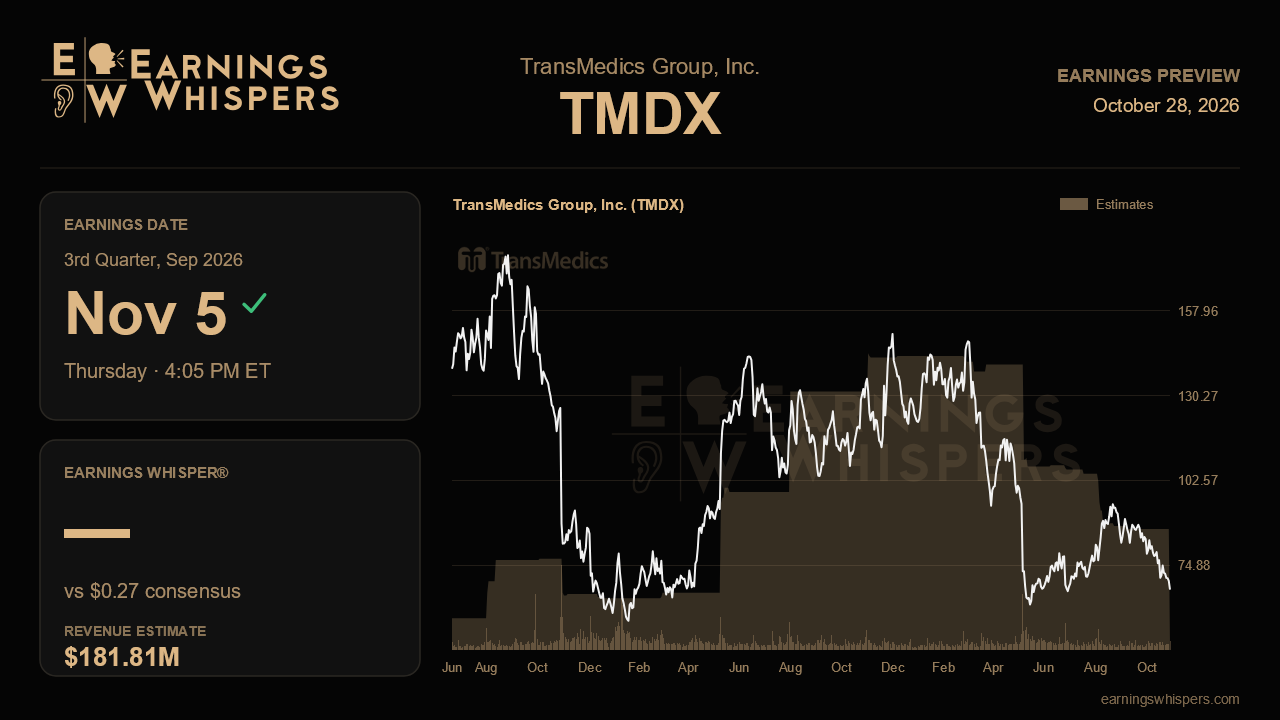
Wall Street expects earnings of $0.27 a share on revenue of $181.8 million when results arrive after the close on November 5. That revenue figure would be up about 26% from a year ago, but earnings are projected to fall roughly 59% from $0.66. Revenue is also expected to slip from the record $189.9 million posted in the second quarter. That sequential dip is not alarming by itself, since management flagged seasonal softness and an August vacation slowdown. The full-year math matters more. TransMedics reaffirmed 2026 revenue guidance of $737 million to $757 million, and the $745.7 million consensus sits comfortably inside that range, just under the midpoint. With roughly $364 million booked in the first half, the Street's numbers imply a fourth quarter near $200 million. A soft third quarter would make that ramp look steep, so the company's tone on the year-end exit rate may matter as much as the quarter itself.
The last call was a clear split decision. On the positive side, service revenue jumped 19% sequentially, logistics revenue rose 30% after a major account defected from a competitor, and double-shifting the aircraft fleet pushed service gross margin to about 35%. Management raised the bottom of its revenue range. On the other side, it cut its adjusted operating margin outlook to roughly 12.5% to 14%, down from about 16% and well below 2025's 18.5%. It blamed faster OCS Kidney spending and warned that the newly closed PAD Aviation deal in Germany would weigh on both gross and operating margins starting this quarter. Second-half gross margin was guided to about 59%, below the long-term target of 60%.
Validation would look like this. Logistics revenue holds near its new level, which would show the competitor win was sticky rather than a one-quarter bump. Service margin eases from 35% but stays well above the high 20s seen in the first quarter. Gross margin lands close to 59% even with PAD included, and operating expense growth looks like the planned investment rather than drift. A sharper margin decline, or vague answers about what PAD contributes and costs, would feed the bear argument that spending is outrunning returns. Product revenue growth, which lagged service last quarter, is also worth checking, especially in liver and heart.
The clinical calendar is the other credibility test. The heart and lung trials have produced only a handful of cases, and their revenue contribution has already slipped from late 2025 to late 2026 or 2027. Another delay would hurt. Management also expected approval of the CHOPS IDE supplement around late third quarter or early fourth quarter, so a firm update there, along with progress on Italian reimbursement and the Boston screening pilot, would help show the new catalysts are moving on schedule.
Sentiment has improved noticeably, with the bearish reading easing to about 13% from roughly 42% before the last report. The stock has not followed. Shares are down 7.5% since the prior release, trailing the S&P 500 by about seven points, and at $66.90 they sit below the $67.31 post-earnings low and roughly 30% under the 200-day moving average. That suggests investors are already braced for weak profits. The central question is whether TransMedics can show the margin reset is a controlled, temporary investment phase with growth still compounding underneath. If it can, the valuation discount looks overdone. If margins slip beyond the new guidance or catalysts slide again, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-07 | |
| Sep-26 | |
| Sep-10 | |
| Aug-31 | |
| Aug-17 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-28 | |
| Jul-24 | |
| Jul-21 | |
| Jul-06 |
