Miller Industries Must Prove Its Rebound Can Survive A Thinner Margin Mix
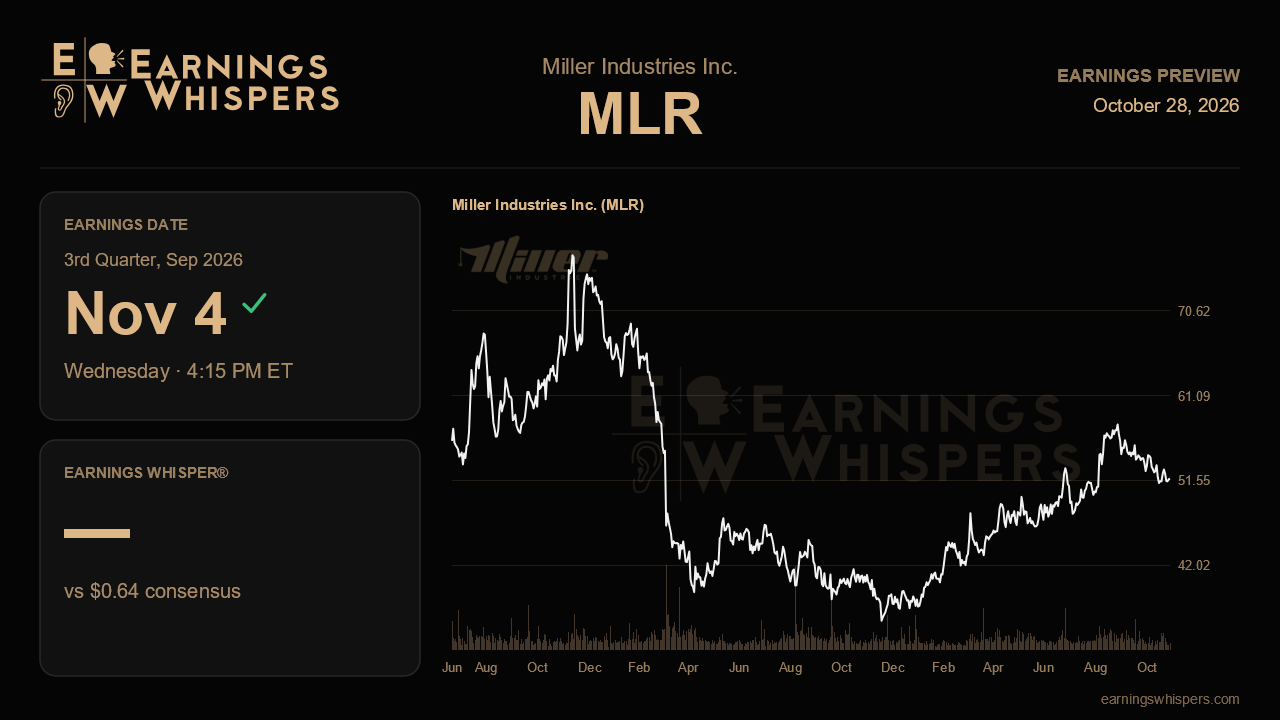
Miller Industries heads into its fiscal third-quarter report with a puzzle that the numbers alone make plain. Management told investors last quarter to expect gross margin to drift back toward the mid-13% range for the full year as chassis-heavy shipments dilute the richer mix of the first half. Yet Wall Street is asking for earnings of $0.64 a share, slightly above the $0.63 the company just delivered on a 15% gross margin. Squaring that circle is the central task of the November 4 release.
On a year-over-year basis, the bar looks generous. The September quarter of last year was one of Miller's trough periods, with revenue of $178.7 million and EPS of just $0.27, so the consensus implies growth of roughly 137%. That headline figure flatters the setup, however. The better comparison is sequential, because the company already staged a sharp recovery in the June quarter, lifting revenue to $240 million from $180.9 million in the prior three months. The real question is whether that level of activity holds, not whether Miller can beat a depressed base.
Management's reaffirmed full-year outlook calls for $850 million to $900 million in revenue with EPS roughly flat with 2025. With about $421 million booked in the first half, the back half needs to produce somewhere between roughly $430 million and $480 million, or about $215 million to $240 million per quarter. A third-quarter print near the top of that band would support the more confident tone executives struck last time, when they shifted from talking about managing uncertainty to positioning for a strong second half. A number closer to the low end, combined with the expected margin slippage, would make the $0.64 consensus look stretched.
Several swing factors could bridge the gap. One-time costs tied to the OMARs acquisition, which shaved 13 cents from Q1 and 11 cents from Q2, are nearly exhausted, with only 4 to 5 cents left to absorb. That tailwind alone could offset a meaningful portion of the mix pressure. The balance sheet also helps, after another $20 million of debt reduction last quarter trimmed interest expense. What would challenge the story is evidence that domestic retail demand is softening rather than merely flat. Management already walked back its earlier hope for a second-half retail pickup, describing production, retail activity and dealer inventory as steady, and citing consumer confidence, fuel prices and Middle East tensions as ongoing caps. Any further downgrade in that language would undercut the core towing business that still drives most of the revenue.
The military business offers the longer-term upside. Commitments topped $200 million last quarter, up from more than $150 million, helped by a larger heavy-duty contract. Production is not expected until 2027, with revenue landing in 2028 and 2029, so this quarter will not show it in the income statement. Still, further backlog additions or export wins would reinforce that Miller is building a growth leg less exposed to the flat domestic tow market.
The market has not given the company much credit since the last report. Shares have slipped 6.4% while the S&P 500 was essentially unchanged, and sentiment has swung from modestly bullish to mildly bearish. At $51.74, the stock sits above its 200-day average of $48.78 but only a few percent above its post-earnings low of $50.52, well off the $59.70 high reached after the June quarter. That retreat suggests investors have already priced in some margin disappointment, which lowers the hurdle for a relief move if execution holds up.
Ultimately, this report hinges on whether Miller can keep quarterly revenue near the $240 million level and let fading acquisition costs cushion a weaker product mix. If it does, the second-half recovery narrative stays intact and full-year guidance looks conservative. If revenue sags toward the low end of the implied range while margins compress, the June quarter will start to look like a peak rather than a new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Sep-22 | |
| Aug-25 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jun-03 | |
| May-06 | |
| May-06 | |
| Apr-29 | |
| Mar-06 | |
| Mar-05 | |
| Mar-04 |
