Relay Therapeutics Heads Into Q3 With A Rerated Stock And Burn Discipline In Focus
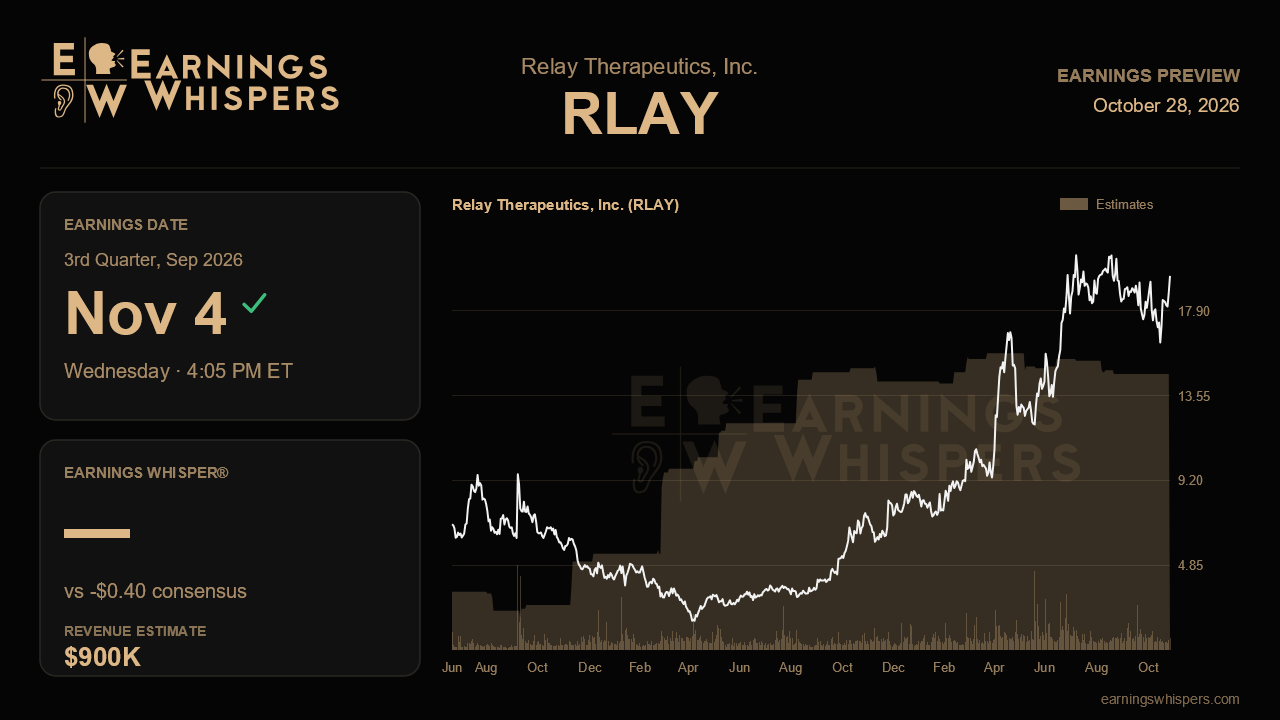
Relay Therapeutics arrives at its third-quarter report in a different position than it held three months ago. The stock has more than doubled off its low of the previous quarter, trades well above its long-term trend line, and sentiment has turned from mildly bearish to modestly bullish. For a clinical-stage oncology company with almost no revenue, the quarterly numbers will not explain that rerating. The real question is whether the report gives investors reason to keep paying up for the pipeline, or a reason to take some chips off the table.
The Street expects a loss of $0.40 per share for the September quarter. That is a touch better than the $0.41 loss in the prior quarter and about 7% better than the $0.43 loss a year earlier. That pattern points to gradual improvement rather than a sharp turn, which is consistent with a company managing its spending carefully while it advances its programs. Consensus revenue of roughly $900 thousand is more than double the $0.4 million booked last quarter. Even so, at these levels revenue is a rounding error relative to the expense base. It likely reflects collaboration or licensing income that can be lumpy from quarter to quarter, so a miss or beat on the top line says little about the underlying business.
With no formal financial guidance on the table, the per-share loss becomes the best available gauge of spending discipline, and that is where the report can add real information. A loss in line with or narrower than $0.40 would suggest research and administrative costs remain contained. That matters because for a company like Relay, every quarter of controlled burn extends the cash runway and reduces the risk of a dilutive equity raise. A materially wider loss would not necessarily be bad news if it reflects heavier investment in programs such as RLY-4008 or its PI3K-focused work. Investors would then want a clear explanation tying the higher spending to clinical progress rather than drift. The cash balance and any update on how long it can fund operations may matter more than the earnings line itself.
The pipeline commentary is the other half of the test. Relay's pitch rests on its computational approach to designing precision small-molecule drugs. A clinical-stage company earns a premium valuation only when that platform keeps producing assets that advance on schedule. This release and call should clarify whether development timelines are holding, whether any programs have been reprioritized, and what milestones lie ahead over the next several quarters. Steady progress would support the stock's recent strength. Vague timing or quiet deprioritization of a program would challenge it, especially after such a strong run.
The market backdrop raises the stakes somewhat. Since the last report, shares have gained about 3% while the S&P 500 was essentially flat, a modest edge layered on top of a much larger move in the prior quarter. At $19.69, the stock sits in the upper half of its post-earnings range of $16.13 to $21.27, roughly 7% below the top of that band. It is not yet testing a breakout, but it is comfortably above its 200-day moving average near $14.80. The trading range has also narrowed sharply from the prior quarter's wide swing between $11.62 and $20.79, which suggests the stock is consolidating gains rather than giving them back. The improvement in sentiment fits that picture, though it remains far from euphoric.
Ultimately, Relay's quarter will be judged less on whether it lands at a $0.40 loss than on whether it pairs disciplined spending with credible, on-time pipeline execution. If the burn rate stays in check and management offers concrete visibility into upcoming clinical milestones, the case for holding recent gains stays intact. If costs climb without a clear clinical payoff, or milestones begin to slip, a stock that has already been rerated has room to give some of that back.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-08 | |
| Oct-01 | |
| Sep-25 | |
| Sep-01 | |
| Aug-20 | |
| Aug-06 | |
| Jul-30 | |
| Jul-23 | |
| May-27 | |
| May-20 | |
| May-19 | |
| May-19 | |
| May-19 |
