Precigen's Papzimios Launch Faces A Slower-Growth Test As Cash Collections Take Center Stage
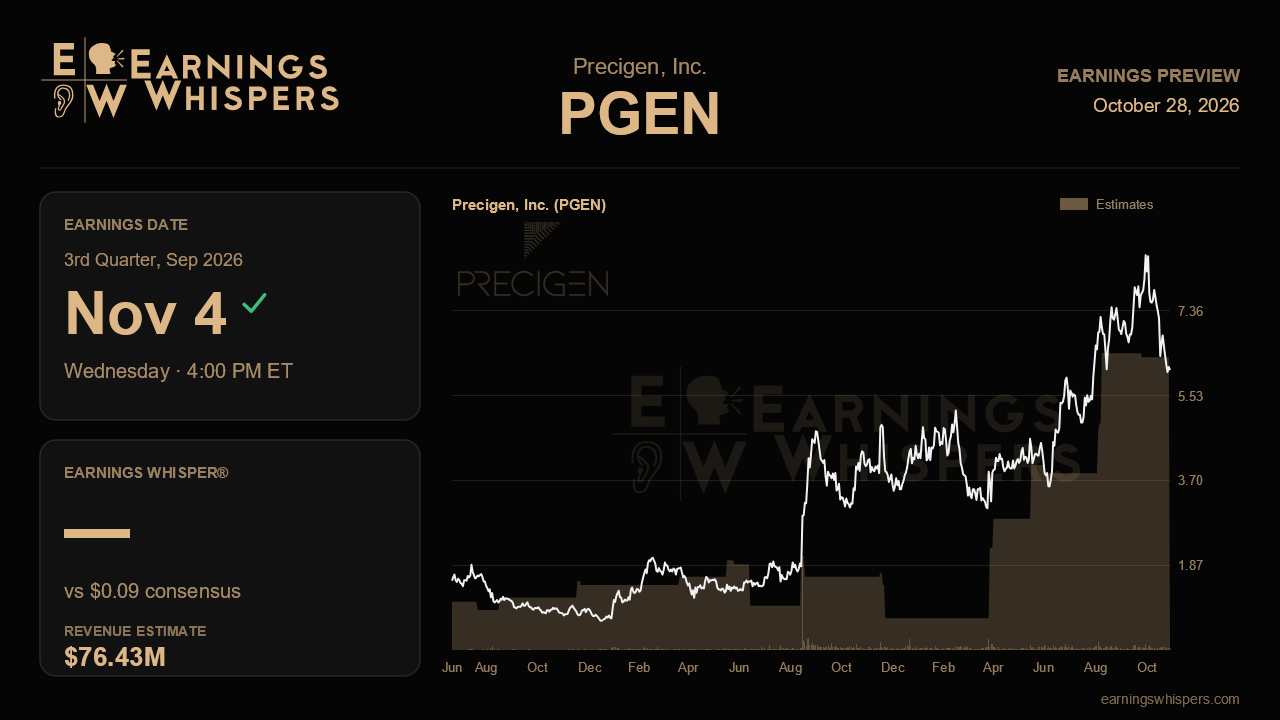
Precigen enters its third-quarter report with a strange mismatch. The Papzimios launch for recurrent respiratory papillomatosis has done almost everything management promised, and the company turned profitable before the drug's first approval anniversary. Yet the stock has given back nearly all of its post-earnings surge, and sentiment has soured noticeably. The question for November 4 is whether a maturing launch can still look like a growth story once the easy sequential comparisons are gone.
Wall Street expects earnings of $0.09 per share on revenue of $76.4 million, compared with a loss of $0.11 a share on just $2.9 million a year ago. That year-over-year comparison, more than 2,500% revenue growth, is mostly an artifact of the launch timing and says little about where the business is heading. The more useful lens is sequential. Last quarter brought $55.0 million in total revenue, including $53.1 million from Papzimios, which was up 145% from the prior quarter. Consensus now implies roughly 39% sequential growth. Management offered no formal revenue guidance and specifically declined to forecast third-quarter growth, warning that percentage gains naturally shrink as a launch matures. The Street has taken that message on board, but the bar is still meaningful: another $20 million-plus of incremental revenue in a single quarter.
The operating indicators from the last call give investors a framework for judging that number. Payer coverage reached roughly 315 million lives, essentially the entire covered market, so further gains must come from patient flow rather than access. Hub registrations topped 500, more than 200 patients had been dosed and over 100 had finished the full four-dose course. Validation this quarter would look like registrations continuing to climb at a healthy clip and a growing share of registered patients converting to treatment. Management credited the permanent J-code, effective April 1, with pulling in accounts that had been holding back; if that benefit was partly a one-time catch-up, a sharper deceleration would challenge the durable multi-year growth narrative management has been promoting.
Margins and cash are the second test. The 95% gross margin disclosed last quarter was flattered by pre-launch inventory previously expensed to R&D, and management has guided toward the high 80s to low 90s over time. Some slippage would be expected rather than alarming. Cash is the more pressing issue. The balance fell to $38.7 million from $100.4 million at the end of 2025, while receivables stood at $71.9 million, which management expected to collect within about four months. This report should show a large portion of that converting to cash. A rebuilt balance would strongly support the long-reiterated goal of cash-flow breakeven by the end of 2026, while a further drawdown, with $100 million of debt costing around $3 million a quarter, would raise uncomfortable questions.
The market's mood has clearly cooled. Sentiment has moved from slightly bearish going into the last report to considerably more bearish now, and shares are down 13.4% since the prior release against a roughly flat S&P 500. At $6.08, the stock sits just above its post-earnings low of $5.96, far below the $8.98 peak, though still above its 200-day moving average of $5.24. Pessimism of that sort can lower the hurdle for a positive reaction, but it also signals that investors want proof rather than promises. Updates on the newly granted exclusivity through August 2032 and the PRGN-2009 head and neck data expected by year end may add color, but they are secondary for now.
Ultimately, this report hinges on whether Papzimios demand is broadening on its own momentum after the J-code tailwind and whether profits are turning into cash. Steady patient growth plus meaningful receivable collections would keep the launch narrative intact; a stall in either would explain why the market has grown skeptical.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-30 | |
| Oct-28 | |
| Oct-28 | |
| Sep-25 | |
| Sep-21 | |
| Aug-25 | |
| Aug-05 | |
| Aug-04 | |
| Jul-21 | |
| Jun-15 | |
| Jun-11 | |
| May-30 | |
| May-27 | |
| May-26 |
