Mineralys Heads Into Final Pre-PDUFA Report With Launch Readiness And Cash Burn In Focus
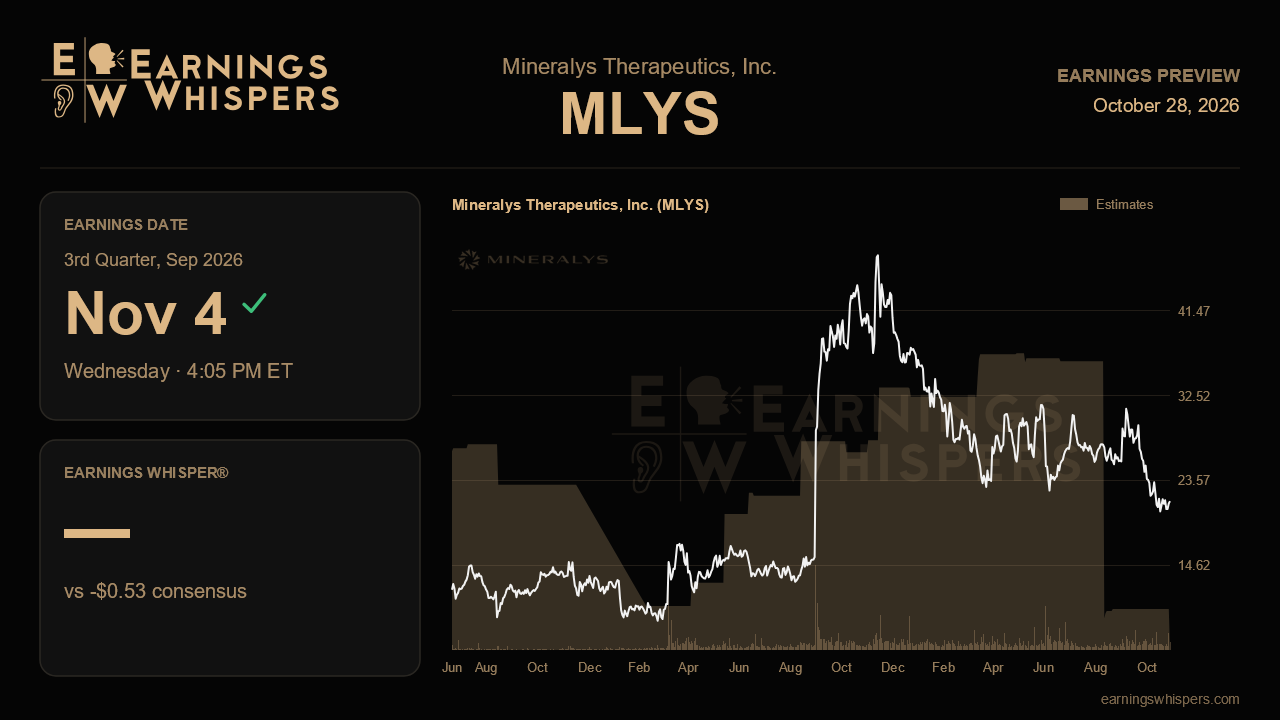
Mineralys Therapeutics reports third-quarter results after the close on November 4 with the most consequential date on its calendar just seven weeks away. The FDA decision on lorundrostat is due December 22, and this report is the last formal checkpoint before that verdict. For a company with no product revenue, the numbers themselves matter less than what they reveal about launch preparation, spending discipline and the balance sheet that has to carry a commercial rollout.
Wall Street expects a loss of $0.53 per share, roughly in line with the $0.52 loss in the same quarter a year ago, implying only a slight 1.9% deterioration. That is a far cry from the $2.85 loss posted last quarter, but the comparison is distorted. The second quarter absorbed a $200 million upfront payment to repurchase the Tanabe royalty, which pushed research and development spending to $221.4 million and the net loss to $241.1 million. With that one-time item gone, consensus is essentially betting that underlying costs settle back toward a more normal run rate. There is no formal guidance to measure against beyond management's statement that cash runway extends into 2028.
The real test is whether operating expenses behave the way that narrative implies. General and administrative costs have climbed steadily, from $9.7 million a year ago to $24.7 million last quarter, as the company built its commercial organization. Management said the sales force would be fully staffed ahead of the PDUFA date, so another step up in SG&A would be expected and even welcome as evidence of readiness. What would challenge the story is a jump in spending large enough to push the loss well beyond consensus without a clear launch rationale, or a cash balance that erodes faster than the 2028 runway suggests. Cash stood at $661.4 million at the end of June, a figure that barely moved despite a $150 million equity raise and access to a $500 million Pharmakon term loan. How much of that facility has been drawn, and what interest costs begin to look like, deserves scrutiny.
Beyond the income statement, last quarter's call shifted the tone from data generation to execution. Management described payer engagement covering the vast majority of covered lives, an established launch campaign, and new supportive data including a 52% placebo-adjusted reduction in urine albumin in a kidney disease subgroup and heart failure biomarker findings. The company also pointed to the live launch of rival baxdrostat as a useful read, saying rebate levels were consistent with its assumptions and that both aldosterone synthase inhibitors should reach parity access. Validation this quarter would come in the form of more concrete pricing signals, any confirmation that FDA review is proceeding without label surprises, and fresh color on how the competitor's uptake is shaping physician demand. Since Mineralys will arrive six to seven months behind its rival, and Medicare access will lag commercial coverage through 2027, any hint that the second-mover gap is widening would weigh on sentiment.
The market has not been generous. Shares have fallen about 14.9% since the last report while the S&P 500 was roughly flat, and at $21.38 the stock sits well below its 200-day moving average of $27.16 and near the bottom of its post-earnings range of $20.12 to $31.99. Sentiment has slipped from neutral to modestly bearish. That combination suggests investors are discounting either competitive pressure or financing overhang despite management's more confident posture, which lowers the bar for reassurance but also means a disappointment could test recent lows.
Ultimately, this report hinges on whether Mineralys can show that its spending is buying a credible, well-funded launch rather than simply a larger burn. Clear evidence of commercial readiness, a controlled loss and a stable runway would keep the pre-approval narrative intact heading into December.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-19 | |
| Oct-09 | |
| Oct-02 | |
| Oct-01 | |
| Sep-29 | |
| Sep-24 | |
| Sep-23 | |
| Sep-21 | |
| Sep-09 | |
| Aug-26 | |
| Aug-13 |
