Bull of the Day: Eni (E)
Italian energy giant Eni E) is emerging as a compelling oil and gas stock to consider as surging crude oil prices and improving earnings expectations fuel optimism across the energy sector.
With geopolitical tensions and supply disruptions pushing crude prices higher, Eni's Zacks Oil and Gas – Integrated – International Industry currently ranks in the top 3% of more than 240 Zacks industries, highlighting strong momentum across the energy sector.
Furthermore, Eni’s diversified portfolio spans oil and gas production, refining, liquefied natural gas (LNG), and renewable energy, offering investors multiple avenues for long-term growth.
Even after soaring nearly 70% year-to-date and trading near its 52-week high of $62 a share, Eni's valuation remains attractive, suggesting additional upside potential.
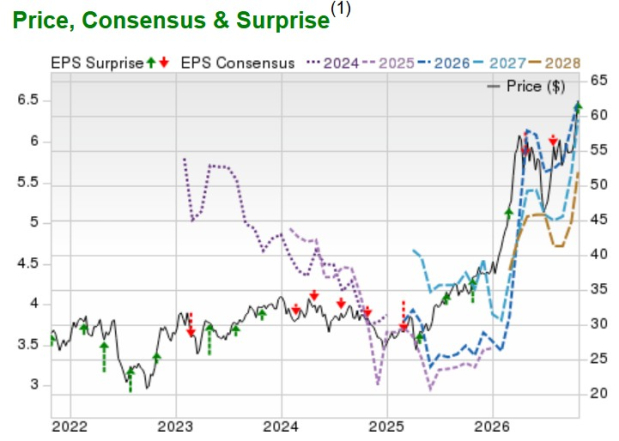
Image Source: Zacks Investment Research
Eni's Earnings Estimates Are Surging
Most appealing is the sharp upward trend in Eni's earnings estimates, with analysts becoming increasingly bullish on the company's profitability.
Over the last 60 days, fiscal 2026 EPS estimates have jumped 15% from $5.77 to $6.65 per share and would equate to 90% year-over-year growth, while FY27 EPS projections have surged 25% in the last two months from $5.08 to $6.38 per share.
Near-term expectations are even more encouraging, with earnings estimates for the next two quarters rising 43% and 59%, respectively.
These substantial upward revisions reflect growing confidence in Eni's earnings outlook and suggest that its recent rally has been supported by improving fundamentals.
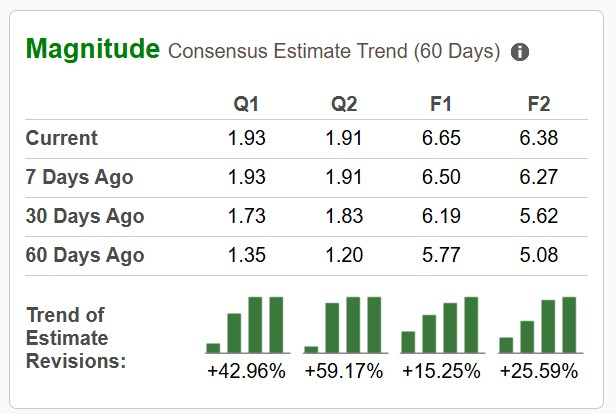
Image Source: Zacks Investment Research
Eni's Attractive Valuation & Revenue Base
Despite its impressive performance, Eni stock still trades at just 9X forward earnings and less than 1X annual sales, representing an appealing valuation for a global integrated energy company.
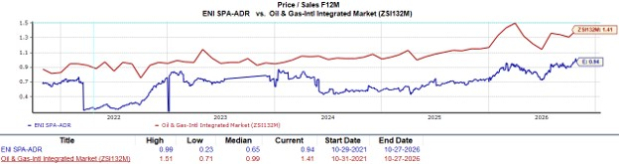
Image Source: Zacks Investment Research
Furthermore, Eni is expected to generate more than $100 billion in annual revenue for the foreseeable future, providing a substantial business foundation from which even modest margin improvements could translate into meaningful earnings growth.
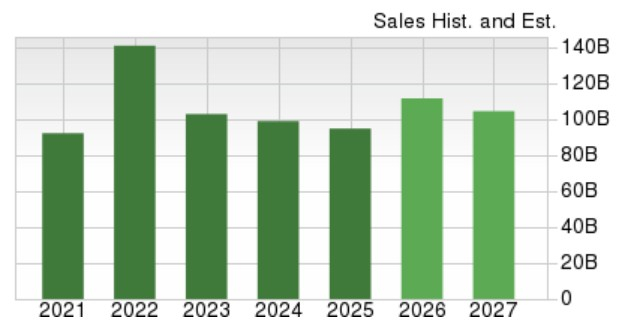
Image Source: Zacks Investment Research
Eni’s Generous Dividend Has Plenty of Room to Grow
Adding to its appeal, Eni offers an attractive annual dividend of $1.68 per share, yielding 2.85% at current levels.
Eni has also increased its dividend at an annualized rate of 6.31% over the last five years, demonstrating its commitment to rewarding shareholders.
More importantly, Eni's modest 30% payout ratio suggests there is plenty of room for future dividend hikes, especially as improving earnings expectations strengthen the company's profitability outlook.
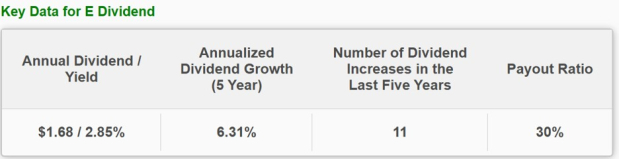
Image Source: Zacks Investment Research
Bottom Line
Sporting a Zacks Rank #1 (Strong Buy), Eni stands out as an attractive energy stock as rising earnings estimates and industry strength reinforce its bullish outlook.
Although shares have rallied considerably, Eni's reasonable valuation, substantial revenue base, and improving earnings potential suggest there could still be more upside ahead.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Eni SpA (E): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 11 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 |
