NewtekOne Misses As Gain-On-Sale Income Vanishes, Credit Stress Builds, And 'Strategic Alternatives' Takes Center Stage
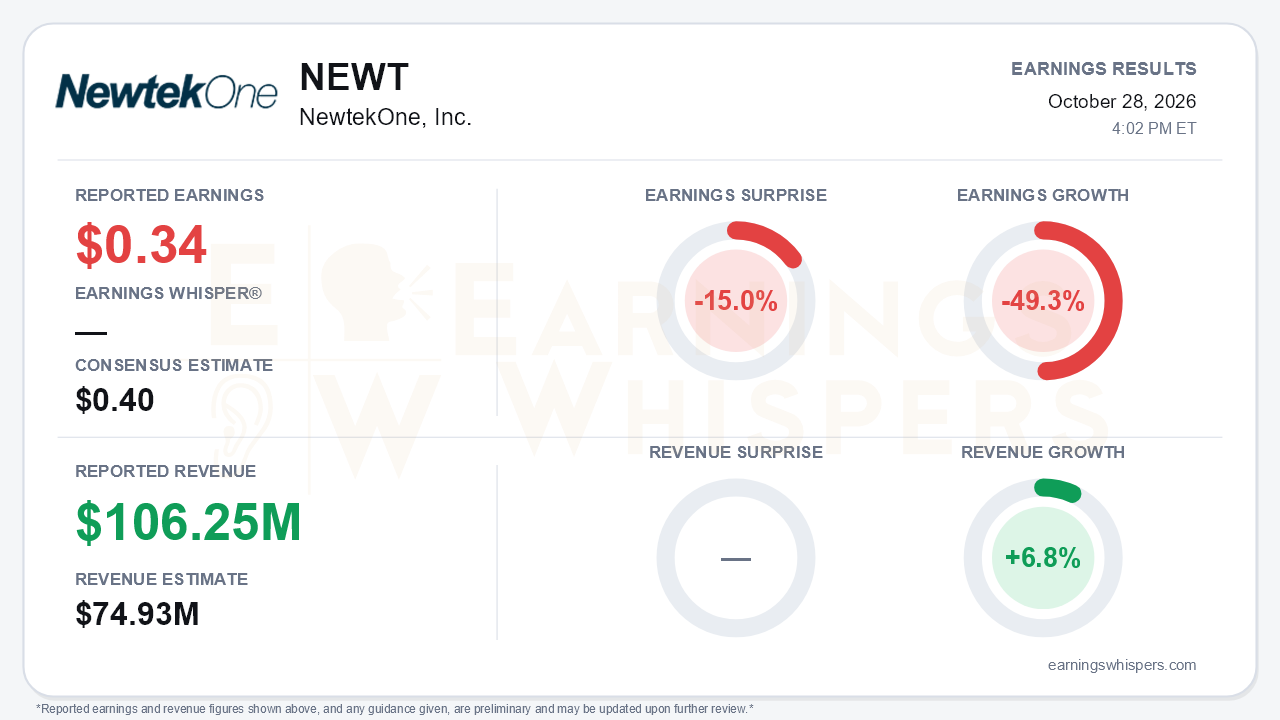
NewtekOne (NASDAQ: NEWT) reported third-quarter earnings of $0.34 per share, missing the $0.40 consensus by 15.0% and falling 49.3% from a year earlier. Reported revenue of $106.25 million beat the $74.93 million consensus by 41.8% and grew 6.8% year over year, but that beat does not reflect better operations. It is a measurement artifact. The central tension is that NewtekOne is deliberately trading volatile gain-on-sale income for recurring spread income. Rising credit costs, muted originations, and a delayed securitization are making the transition far more expensive than management signaled earlier in the year.
The quality of the revenue beat deserves scrutiny. The $106.25 million figure appears to capture gross interest income plus noninterest income. On the net basis the company uses in its efficiency ratio, total income was $71.8 million. That compares with $75.1 million in the second quarter and $74.9 million a year ago, so net revenue declined on both comparisons. The biggest swing came from net gains on sales of loans, which collapsed to just $32 thousand from $11.2 million in Q2 and $9.6 million a year earlier. That drop follows from the decision to hold more guaranteed SBA 7(a) balances rather than sell them. Net interest income did rise to a record $18.9 million, up 26% sequentially and 30% year over year. However, the provision for credit losses jumped to $15.4 million from $12.1 million in Q2 and $7.7 million a year ago. As a result, net interest income after provisions was only $3.5 million. Operating expenses were flat year over year despite 47% asset growth. Even so, the efficiency ratio slipped to 58.7% from 56.3%, and return on average equity was cut by more than half to 9.2% from 20.4%.
The funding side is the clear bright spot. Deposits more than doubled year over year to roughly $2.5 billion, according to the release. The call cited $2.6 billion of bank deposits, up from $2.2 billion in Q2. Accounts topped 47,000, compared with about 21,800 a year ago. Year-to-date originations of $1.2 billion were up 12%, and NewtekOne reclaimed the top spot in SBA 7(a) approvals by count for the SBA fiscal year. Tangible book value per common share rose to $12.30. Beneath those positives, the mix is less flattering. Management acknowledged that growth in low-cost core business deposits has stalled, calling it 'slower than I'd like.' The deposit surge is overwhelmingly rate-driven consumer money, and deposit interest expense roughly doubled year over year to $22.3 million.
Credit is where bears have the most legitimate ammunition. On the first-quarter call, management described stabilization. By Q3, non-performing loans in the longer-amortizing C&I (C&I LA) portfolio had jumped to $82 million from $46 million. Management cited stress in older vintages and said it is tightening underwriting. Non-accruals excluding government guarantees stood at 3.9%, and the allowance has climbed to $57.1 million from $45.2 million at year-end. Management also said it is intentionally muting origination volumes because of high rates and sticky inflation. Meanwhile, the C&I LA securitization keeps slipping. It was pegged at $400-500 million for Q4 on the Q1 call, then $300-400 million for Q4, and is now $350-400 million in January 2027. With capital ratios near normal levels, that delay could constrain balance-sheet growth until the deal closes.
Guidance tells the same story. Management said it is 'comfortable' with 2026 EPS of $1.70-$1.80, but that range sits well below the $2.15-$2.55 outlook from earlier in the year. Even the lower range implies a fourth quarter meaningfully stronger than the $0.34 just reported. The $2.60 midpoint target for 2027 was not reiterated. The tone has shifted from confident target-setting to valuation advocacy. CEO Barry Sloane cited Valley National's proposed $340 million Bluevine acquisition as evidence of value in digital small-business platforms and said the company is exploring 'all strategic alternatives.' That is a genuine potential catalyst, but it also reads as a pivot away from defending the earnings trajectory.
Investors were already skeptical heading in. Earnings Whispers sentiment remained negative and weakened moderately, falling from -0.165 to -0.239. Shares have dropped 22.0% since opening at $14.70 after the August report, to $11.46. The stock now trades about 11% below its 200-day moving average of $12.88. The Earnings Whispers trend signals are mostly negative, with price, momentum, and AVWAP all pointing lower, while sequential growth is neutral.
The bottom line is that NewtekOne's quarter was weaker than the revenue beat suggests. The shift to net interest income is real, and the deposit franchise is growing rapidly. But a near-total loss of gain-on-sale income, sharply higher provisions, rising C&I LA non-performers, and a repeatedly delayed securitization have left the earnings path well below earlier expectations. The strategic-alternatives process gives the stock a possible exit valve. Until credit stabilizes and the securitization closes, however, the burden of proof sits with management.
Read our earnings preview for NewtekOne, Inc.: https://www.earningswhispers.com/article/NEWT/20966
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Sep-28 | |
| Sep-14 | |
| Aug-28 | |
| Aug-18 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-27 | |
| Jun-23 |
