Teladoc Beats On Cost Discipline And BetterHelp Insurance Ramp, But Revenue Is Still Shrinking
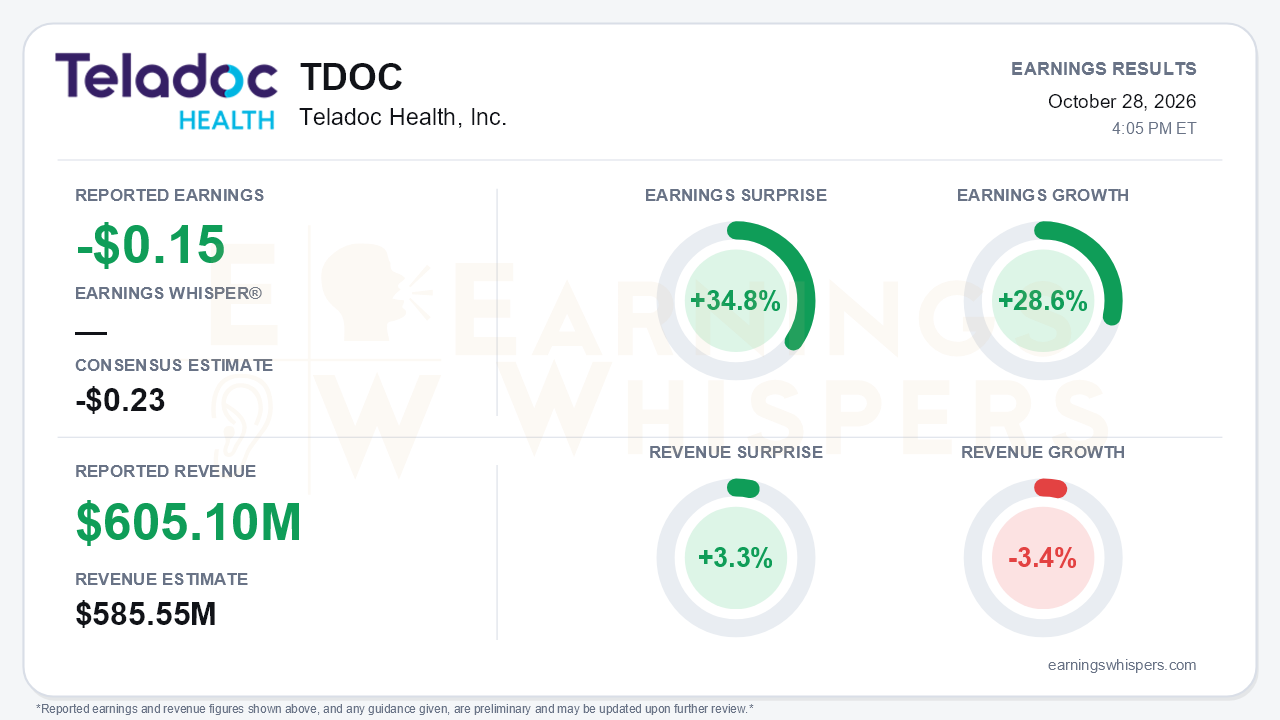
Teladoc Health delivered a clean third-quarter beat. It reported a loss of $0.15 per share against a consensus estimate of a $0.23 loss, a 34.8% surprise. Revenue of $605.1 million topped the $585.55 million consensus by 3.3%. Earnings improved 28.6% year over year as the net loss narrowed to $26.9 million from $49.5 million. Revenue, however, fell 3.4%, and that is the central tension. Teladoc is becoming more profitable and more efficient while its top line keeps contracting. The improvement comes from a deliberate shrinking of BetterHelp's cash-pay business and steady margin gains in Integrated Care, not from a return to growth.
The quality of the beat deserves scrutiny. Adjusted EBITDA rose 14% to $79.4 million, well above the company's $62 million to $74 million guidance range. A large part of the improvement traces to advertising and marketing, which fell to $124.0 million from $168.0 million a year earlier. The GAAP comparison also benefited from two other items:
- Stock-based compensation fell to $11.6 million from $17.0 million.
- The prior-year quarter carried a $12.6 million goodwill impairment that did not recur.
Under the surface, access-fee revenue fell 10% while other revenue rose 31%. Third-quarter free cash flow of $75.9 million was solid, but nine-month free cash flow of $85.4 million still trails last year's $113.5 million.
Integrated Care was the steadier engine. Segment revenue grew only 2%, and U.S. members slipped 2% to 100.1 million. Monetization improved, though:
- Average monthly revenue per member rose 5% to $1.33.
- Chronic care enrollment climbed 15% to 1.344 million.
- Segment adjusted EBITDA margin expanded to 18.8% from 17.0%, above management's 15.7% to 17.2% guide.
- Management raised the full-year segment margin outlook to 16.0% to 16.6%, its third consecutive increase.
BetterHelp tells a more complicated story. Segment revenue dropped 13%, consumer revenue fell 25% to $174.5 million, and paying users declined 12% to 336,000. Insurance-covered revenue, by contrast, reached $32.1 million. That compares with $3.7 million a year ago and $22 million last quarter, and it beat the company's own guide. Other insurance metrics are scaling quickly:
- The annualized insurance run rate now exceeds $140 million, up from more than $110 million last quarter.
- Credentialed therapists topped 11,000.
- Insurance accounted for 36% of newly acquired U.S. users.
Management lifted its full-year insurance revenue outlook to $99 million to $105 million. It also set a 2027 goal of at least a $200 million annualized insurance exit run rate.
The forward guidance is where bears have legitimate ammunition. Consolidated full-year revenue guidance rose about $13 million at the midpoint to $2.395 billion to $2.441 billion. Adjusted EBITDA guidance edged up to $277 million to $303 million. Free cash flow guidance was only narrowed. BetterHelp's full-year EBITDA margin outlook was cut to 2.7% to 4.3% on mix and insurance investment, and management acknowledged that insurance carries a lower gross margin than cash pay. The fourth-quarter BetterHelp revenue guide calls for a decline of 18.5% to 31.5% amid a steeper advertising pullback. Management also said 2027 ad spend will fall by a mid-to-high 20% rate, with cash-pay revenue expected to decline correspondingly. In short, BetterHelp remains in a managed decline toward an in-network model. The insurance ramp is impressive, but it is not yet large enough to offset the shrinking cash-pay base.
Other developments add both optionality and execution risk:
- Teladoc completed the Teledyne Health acquisition to build U.S. hybrid care.
- Teladoc One moved into execution with launch partners, with broad availability targeted for 2027.
- New AI features were added to the Solo platform.
- A new CFO, Mike Grasher, joined in late August.
The balance sheet also deserves attention. Nearly $1 billion of convertible notes is now classified as current. Management outlined a plan to repurchase a substantial portion, potentially before year end, backed by $850 million of cash and net leverage of about 0.5x. How that refinancing is executed is a near-term swing factor.
The market had grown cooler heading into the report. Investor sentiment remained slightly positive but weakened modestly, from 0.11 to 0.07. Shares closed at $6.88, down 10.2% since the opening after the July report. The stock still sits about 6.6% above its 200-day moving average of $6.46. Most Earnings Whispers trend readings, including price, sequential growth and momentum, remain negative, although AVWAP is positive. That backdrop suggests investors had already discounted much of the BetterHelp reset.
The bottom line is that Teladoc produced a credible beat-and-modest-raise quarter. Margin expansion in Integrated Care and a faster-than-planned insurance ramp at BetterHelp stabilized the story after last quarter's guidance reset. Still, the profit improvement leans heavily on reduced marketing spend, consolidated revenue continues to decline, and guidance points to further cash-pay erosion into 2027. Investors now have clearer milestones in the insurance run rate, Teladoc One adoption and the convertible refinancing. A durable rerating likely depends on evidence that those initiatives can return the top line to growth.
Read our earnings preview for Teladoc Health, Inc.: https://www.earningswhispers.com/article/TDOC/20990
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Sep-25 | |
| Sep-24 | |
| Sep-03 | |
| Aug-31 | |
| Aug-17 | |
| Aug-03 | |
| Jul-30 |
?? Under the Radar: Teladoc Shares Tumble on Therapist Shortage
TDOC -28.32%
The Wall Street Journal
|
| Jul-30 | |
| Jul-30 |
