Gen Digital Beats And Raises Again As Partner Growth Surges, But Mix-Driven Margin Pressure And A Sliding Stock Complicate The Story
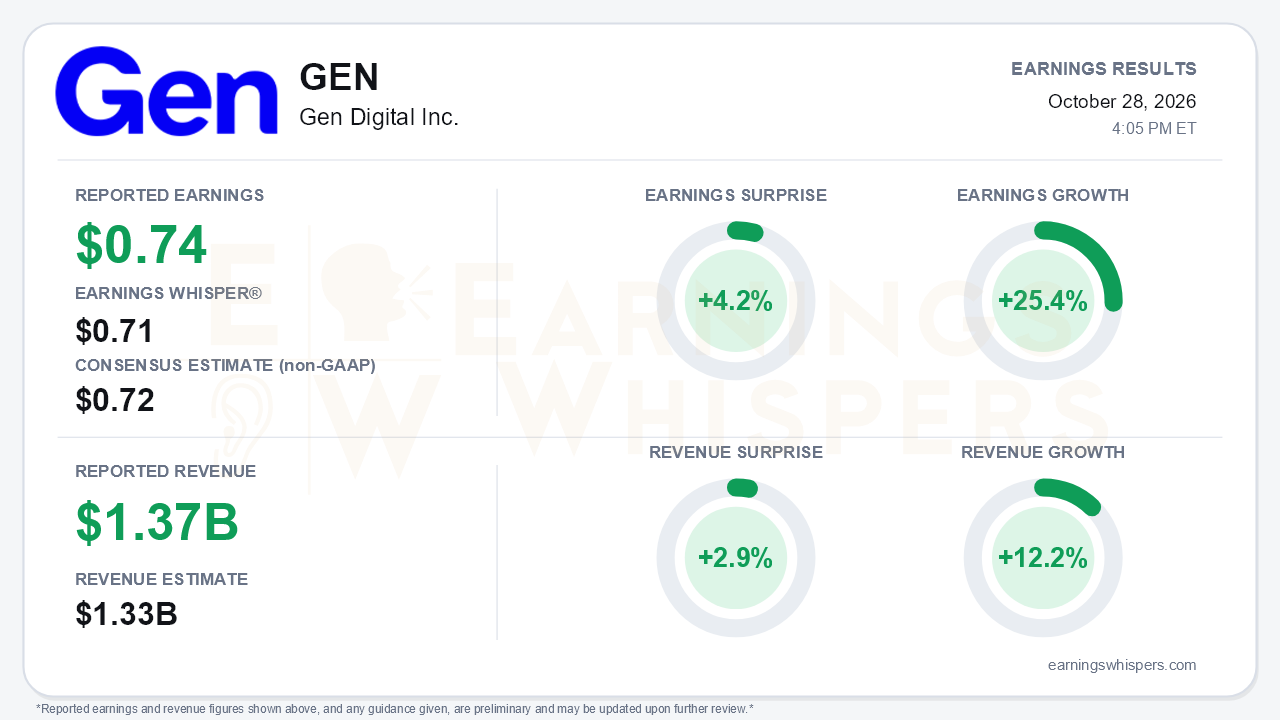
Gen Digital delivered its second consecutive beat-and-raise in fiscal Q2 2027, though the market setup is more complicated than the surprise implies. Non-GAAP EPS of $0.74 topped the $0.72 consensus by 4.2% and cleared the $0.71 Earnings Whisper number. Revenue of $1.369 billion beat the $1.33 billion consensus by 2.9% and grew 12.2% year over year. Earnings Whispers calculates earnings growth of 25.4%. The company's own non-GAAP comparison, against $0.62 a year ago, shows 19%, so investors will see both figures cited. Revenue growth has now accelerated for three straight quarters, from 9% pro forma in fiscal Q4 2026 to 11% in Q1 and 12% now. That top-line acceleration is the central positive. The central tension is that growth is increasingly coming from lower-margin businesses while the stock has moved sharply the other way.
The quality of the beat deserves some scrutiny. On a GAAP basis, diluted EPS more than doubled to $0.48 from $0.21. That comparison is flattered by the absence of a $69 million equity-investment impairment in the prior-year quarter and by interest expense falling to $123 million from $146 million. Share count also helped. Diluted shares fell to 603 million from 624 million, and Gen repurchased $171 million of stock in the quarter.
Operationally, there are signs of margin dilution. Cost of revenues rose about 24%, roughly double the pace of revenue, which compressed gross margin. The non-GAAP operating margin was 50.1%, down from 51.1% a year ago, and non-GAAP operating income grew 10%, slower than revenue. Management characterized margins as flat at roughly 50%, which is fair sequentially but generous year over year. Bookings, the forward demand indicator, grew 10% and eased from 11% in Q1. Trust-Based Solutions bookings slipped to 24% growth from 25%.
The call nonetheless preserved a credible growth story. Trust-Based Solutions revenue, which spans identity, reputation and financial wellness including MoneyLion, accelerated to 26% growth from 24%. The more mature Cyber Safety segment improved to 5% from 4%, with a record 62% segment margin. Partner revenue was the standout, jumping 40% to $295 million versus 31% growth in Q1. That was driven by employee-benefits growth that management called the strongest in more than five quarters. Norton Money Workplace enters enrollment season with a qualified pipeline above $30 million.
Several other operating metrics improved:
- Paid customers climbed to 83 million, up from 81 million in Q1 and 79 million in Q4.
- Norton cross-sell penetration neared 30%.
- Renewal rates reached a four-quarter high.
- AI-driven efficiencies pushed operating expenses down to 30% of sales.
The trade-off is structural. Management indicated Trust-Based Solutions margins are capped near 30% as mix shifts toward lower-gross-margin marketplace categories. The faster that segment grows, the harder it is to expand consolidated margins.
Guidance moved higher again, though the raise was in line with estimates rather than a step-change. Fiscal 2027 revenue guidance rose to $5.465-$5.515 billion from $5.375-$5.475 billion. Non-GAAP EPS guidance moved to $2.93-$2.98 from $2.87-$2.97, implying 16-18% growth and above the company's old 12-15% mid-term target. Q3 guidance calls for revenue of $1.365-$1.390 billion and EPS of $0.73-$0.75.
On the forward-looking side:
- **AI agents:** Engine launched an insurance-shopping experience built for AI agents, and skills scanned through Agent Trust Hub have been installed more than 100 million times. However, agentic revenue is not expected to be material this fiscal year, and MoneyLion One remains immaterial.
- **Renewal risk:** Management flagged the possibility that consumer AI agents auditing subscriptions could pressure renewals, though this has not yet been observed.
- **M&A rumors:** Gen had to address media reports of a large acquisition, stating no transformative deal is in the works.
- **Debt:** Net leverage improved to below 2.9x. Still, the current portion of long-term debt jumped to $1.08 billion from $181 million, a refinancing item worth watching.
Investors have not been rewarding the fundamental progress. Shares have fallen 16% since opening at $29.00 after the August report and now trade at $24.35, essentially sitting on the 200-day moving average of $24.31. Investor sentiment remained negative and deteriorated meaningfully, falling to -0.31 from -0.16. That suggests the M&A overhang and margin-mix concerns weighed more heavily than the raised outlook. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Gen is executing well on the top line, with accelerating revenue, surging partner sales, record customers and a twice-raised outlook. Bears still have legitimate ammunition in slowing bookings, mix-driven margin pressure and lingering deal anxiety. With the stock balanced on its 200-day average and sentiment souring, the next leg likely depends on whether bookings reaccelerate and margins hold as Trust-Based Solutions becomes a larger share of the business.
Read our earnings preview for Gen Digital Inc.: https://www.earningswhispers.com/article/GEN/20939
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 5 hours | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Sep-30 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 |
