Coastal Financial Returns To Profit But Misses EPS Estimates As Margin Compression And The Bluevine Exit Offset Fee Momentum
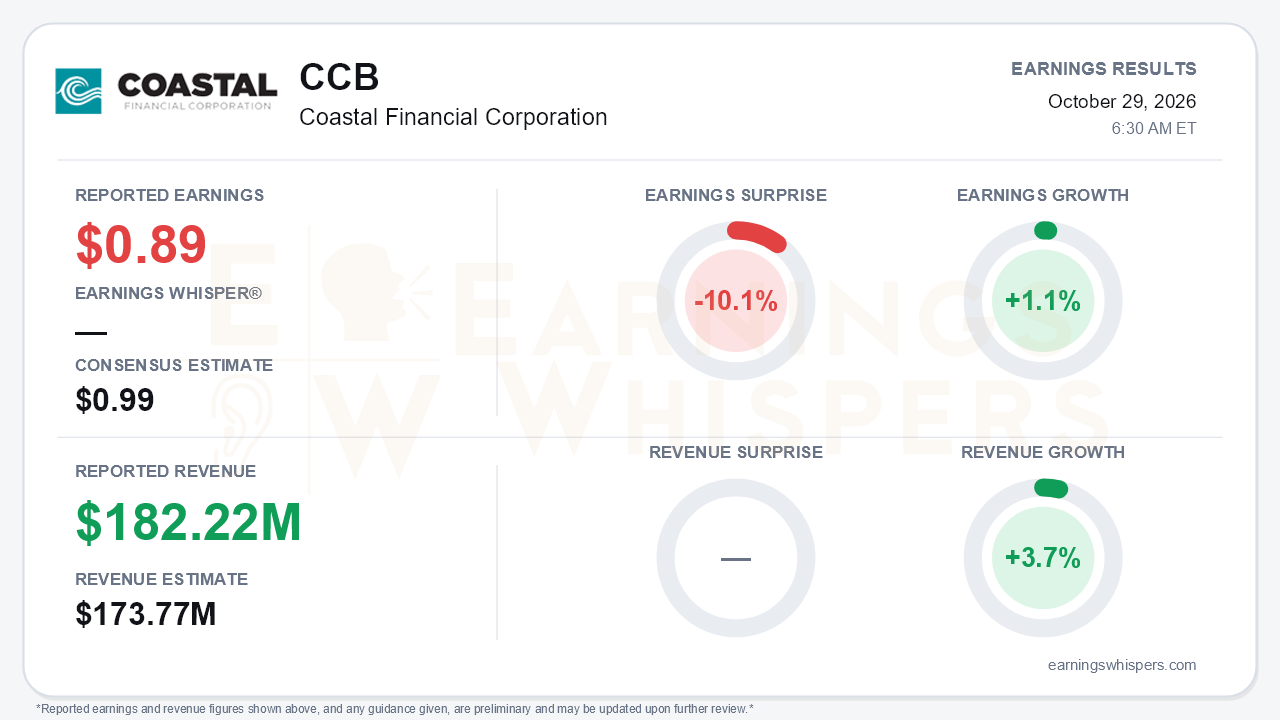
Coastal Financial Corporation (NASDAQ: CCB) returned to profitability in the third quarter, but the rebound fell short of what analysts had modeled. The bank earned $0.89 per diluted share, a swing from the $2.76 loss in the second quarter, which was dominated by partner-related charges. That result missed the $0.99 consensus by 10.1%. Revenue of $182.22 million beat expectations by 4.9%. Year over year, earnings grew just 1.1% and revenue 3.7%, so the growth story is close to flat. That is the central tension. Coastal showed that the second-quarter blowup has not broken the franchise, but it has not yet shown that the franchise can grow earnings faster than it did before the damage.
The quality of the quarter deserves scrutiny in both directions. Much of the sequential improvement reflects the absence of the $46.0 million credit enhancement valuation adjustment and a provision that halved to $46.0 million from $92.2 million. Underlying profitability is still weaker than a year ago:
- ROA was 1.01%, compared with 1.19% in the year-ago quarter.
- The efficiency ratio rose to 56.8% from 48.5%.
- Noninterest expense excluding BaaS loan and fraud costs climbed to $45.0 million from $35.2 million a year earlier.
- Legal and professional fees nearly doubled to $7.8 million, partly because of the troubled partner.
- FDIC assessments rose, in part because the second-quarter loss fed into the assessment calculation.
In other words, the Q2 problem is still levying a tax on the run-rate.
The margin is the clearest pressure point. Net interest margin fell to 6.59% from 7.27%, and net interest income slipped 1.2% to $88.3 million from the prior quarter's record. Management attributed the decline to a mix shift toward cash-secured and higher-quality loans under tighter underwriting. Reported CCBX loan yields dropped to 12.73% from 14.56%. Netting out BaaS loan expense softens the picture:
- Net BaaS loan income held at 7.02% of average CCBX loans, versus 7.07% in the prior quarter.
- Consolidated loan income net of BaaS expense edged up to 6.86%.
- Net interest margin net of BaaS loan expense still eased to 3.93% from 3.98%.
The de-risking is real, but it costs spread. The growth engine increasingly runs off the balance sheet. BaaS program fee income rose 17.6% sequentially and 79.6% year over year to $14.1 million. Loans sold jumped to $5.99 billion from $4.56 billion. Swept deposits reached $6.29 billion from $4.26 billion, and off-balance-sheet credit card accounts rose 51% to about 1.3 million.
Credit is stabilizing, though not resolved. Net charge-offs fell to 4.43% of average loans from 4.90%, and nonperforming assets declined $14.7 million. On the call, management said the troubled partner's charge-off and delinquency rates improved and that no comparable issue was found across the other 21 active partners. Bears still have legitimate ammunition:
- Charge-offs at the partner ran modestly above projections.
- $3.1 million of provision went unreimbursed.
- The $22.8 million specific allowance is expected to be charged off by year end.
- Bluevine's pending acquisition by Valley National, expected to close in the second quarter of 2027, will remove $452.4 million of on-balance-sheet deposits and $1.85 billion of swept balances. Management says it does not expect a material liquidity impact but has not quantified the earnings effect.
On the catalyst side, the vague second-quarter cost focus has become a concrete target of up to $20 million in annualized savings over four to six quarters. The CEO's roughly 43% base-salary cut signals seriousness. CET1 improved to 11.47%, the pipeline holds two partners onboarding and three signed LOIs, and eight active programs are expanding into new products. Leadership churn remains a soft spot. The CFO role is still filled on an interim basis, and the president has stepped down. The company again offered no formal financial guidance.
The market had already priced in considerable doubt. Shares closed at $47.13 ahead of the report, down 14.3% from the opening after the prior release. That leaves the stock nearly 32% below its 200-day moving average and 16.4% below the inter-earnings high of $56.40, set on the day of the Q2 report. The stock did rebound about 32.5% from its September 28 low of $35.56, which was also a 52-week low. Investor sentiment improved only marginally, from -0.453 to -0.439, and remains firmly negative. AVWAP readings have turned positive, consistent with that recovery off the lows, while broader price trends are neutral.
The bottom line is that Coastal delivered a credible stabilization quarter rather than a clean recovery. Fee income, capital-light volumes, credit trends, and a quantified cost plan argue that the franchise is intact. However, the EPS miss, the margin compression, elevated legal and regulatory costs, and the coming Bluevine deposit exit mean earnings power has not yet been restored. The next few quarters will test whether expense savings and off-balance-sheet fee growth can outrun spread pressure and the lingering partner overhang.
Read our earnings preview for Coastal Financial Corporation: https://www.earningswhispers.com/article/CCB/21321
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 |
