Bunge Beats On Crush Strength, But A Held Outlook And Swelling Balance Sheet Shift The Story To 2027
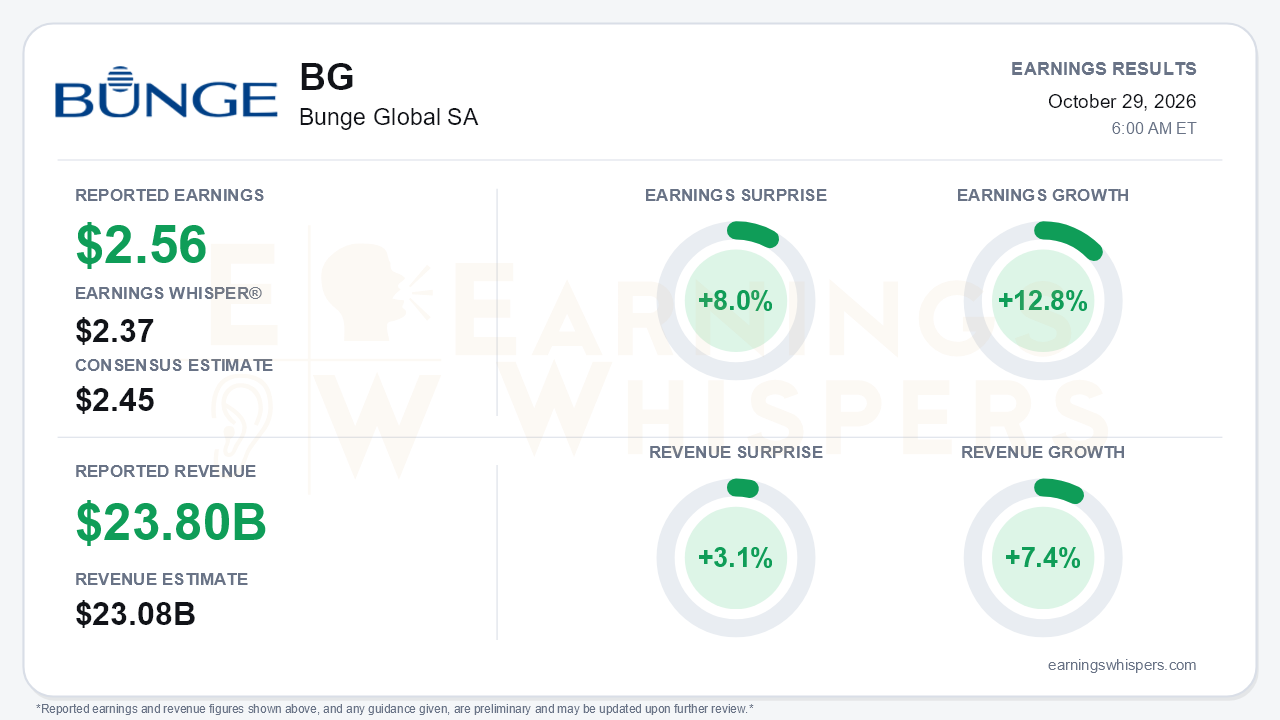
Bunge Global SA delivered a clean headline beat in the third quarter. Adjusted EPS of $2.56 topped the $2.45 consensus by 8.0% and cleared the more cautious $2.37 Earnings Whisper number. Revenue of $23.804 billion beat expectations by 3.1%. Earnings grew 12.8% year over year on 7.4% revenue growth, and GAAP diluted EPS from continuing operations nearly doubled to $1.64 from $0.86. The more consequential development came after the beat. Following two consecutive raises, management held full-year adjusted EPS guidance at $9.25 to $9.75. Bunge is still executing well, but the forward narrative is moving away from 2026 upside and toward a quantified 2027 self-help story. That is the central tension.
The quality of the quarter is concentrated in oilseed processing. Adjusted Soybean Processing and Refining EBIT rose to $565 million from $478 million, led by North American crush. Softseed adjusted EBIT climbed to $329 million from $275 million, with processing volumes up in every region. Those two segments carried the quarter.
Elsewhere, the picture was weaker:
- **Tropical Oils and Specialty Ingredients:** Adjusted EBIT fell to $16 million from $51 million, hit by trade disruptions and commissioning and ramp-up costs.
- **Grain Merchandising and Milling:** Adjusted EBIT slipped to $87 million from $120 million as ocean freight, sugar and wheat milling weakened.
- **Corporate costs:** Adjusted corporate expense improved partly because of lower performance-based compensation and favorable foreign exchange, which are not durable operating gains.
- **Excluded charges:** The gap between GAAP and adjusted results includes an $82 million ($0.43 per share) charge tied to the sale of two Brazilian sugar mills and $0.11 per share in Ukraine-Russia charges.
- **Soybean volumes:** Soybeans processed declined year over year on weakness in South America and Asia.
The call explains why the guidance stayed flat despite the beat. The segment outlook was reshuffled rather than lifted:
- Grain Merchandising and Milling was raised, reversing cuts made in the first and second quarters, helped by Black Sea disruption and large Australian and Canadian crops.
- Soybean Processing and Refining moved from "higher" in each prior quarter to "slightly lower," reflecting softer fourth-quarter crush curves.
- Tropical oils was cut again.
- Below the line, net interest guidance rose for a second time, to $640-$670 million from $620-$660 million (the original range was $575-$625 million).
- The tax-rate range narrowed to 23%-25% from 22%-26%, implying a higher fourth-quarter rate.
With $6.38 of adjusted EPS already banked through nine months, the reaffirmed range implies a fourth quarter weighed down by interest and tax. Management repeatedly described the environment as "as complicated as any" and said late-quarter conditions were worse than expected.
The balance sheet gives bears legitimate ammunition. Elevated commodity prices pushed inventories up $3.56 billion year to date, driving operating cash flow to an outflow of $2.30 billion. Short-term debt rose to $6.47 billion from $3.88 billion at year-end. Net debt now exceeds readily marketable inventories by $1.2 billion, compared with inventories exceeding net debt by roughly $400 million at the first quarter. Available commercial paper capacity has shrunk to about $900 million from roughly $2.4 billion. Adjusted funds from operations of $2.0 billion shows the underlying earnings power is intact. Still, financing that working capital is now a real drag on per-share results.
Against that, the call offered genuine catalysts:
- **Growth projects:** The Destrehan multi-seed crush plant with Chevron and its barge unloader started up in October. Morristown is in customer qualification, and the Westzaan refinery remains on track for the first quarter of 2027.
- **Synergies:** 2026 Viterra cost synergies are tracking above $200 million versus a $190 million plan.
- **2027 earnings bridge:** For the first time, management quantified about $1.50 per share of potential tailwinds. That breaks down to roughly $0.50 each from in-flight projects, incremental cost synergies and commercial synergies.
- **Policy support:** The U.S. small refinery exemption reallocation decision and Brazil's move beyond B15 biodiesel support oil demand.
- **Returns:** Trailing adjusted ROIC improved to 8.8% from 8.4% in the second quarter.
Key risks include:
- the timing of the exemption reallocation;
- U.S.-China soybean purchase commitments, with roughly 17 of 25 million tons completed;
- EU deforestation rules taking effect at year-end;
- farm economics and weather.
The market had already turned skeptical heading into the print. Shares closed at $100.80 the day before the report, down 10.7% since the open after the July release. The stock sat 14.0% below its 200-day moving average and 20.9% below its September 10 inter-earnings high of $127.47. It traded just 0.8% above the period low of $99.99 set on October 28. Earnings Whispers investor sentiment slipped from modestly positive (0.14) to slightly negative (-0.04), a meaningful but not dramatic cooling. The trend readings were mixed, with price and AVWAP negative while momentum held positive. A beat against lowered expectations gives the stock some room. However, the absence of a raise removes the catalyst that drove earlier quarters.
The bottom line is that Bunge's operating engine, particularly North American crush, outperformed, and the 2027 bridge offers a credible, specific path to higher earnings. However, the full-year outlook stalled, segment mix is deteriorating outside oilseeds, and rising interest costs and tighter liquidity are eroding per-share leverage. Investors now have to underwrite next year's self-help story rather than this year's upside. With shares pinned near their lows and sentiment cooling, execution on Destrehan, synergies and working-capital normalization will matter more than the beat itself.
Read our earnings preview for Bunge Global SA: https://www.earningswhispers.com/article/BG/21038
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| 6 hours | |
| Oct-21 | |
| Oct-16 | |
| Oct-09 | |
| Oct-01 | |
| Oct-01 | |
| Sep-14 | |
| Sep-01 | |
| Aug-20 | |
| Aug-17 | |
| Aug-13 | |
| Jul-30 | |
| Jul-29 |
