Novocure Beats And Raises For A Third Straight Quarter, But A Stalled Optune Pax Launch Clouds The Growth Story
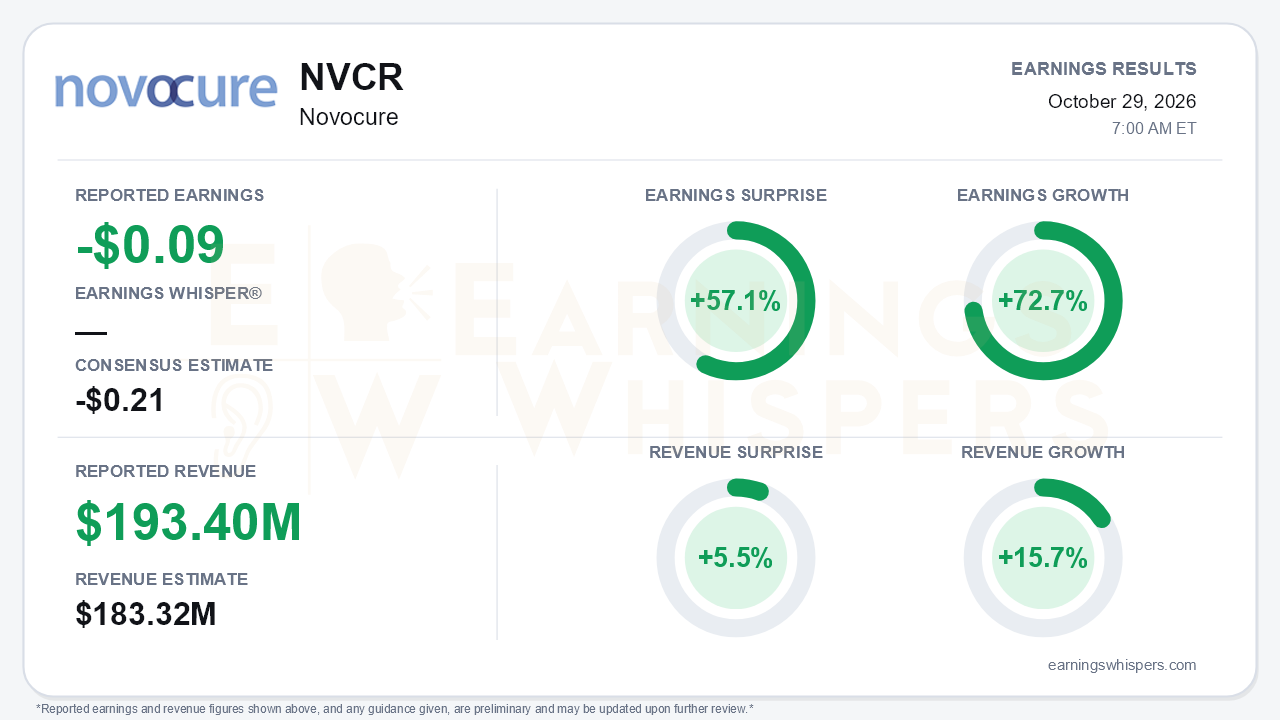
Novocure delivered the kind of quarter that usually resets a stock's narrative. The loss of $0.09 per share beat the -$0.21 consensus by 57.1%. Revenue of $193.4 million, a company record, topped the $183.32 million estimate by 5.5%. Earnings improved 72.7% year over year as the net loss narrowed from $37.3 million to $10.4 million. Revenue grew 15.7%, matching the second quarter's pace and building on 12% growth in the first quarter. Management raised full-year 2026 revenue guidance to $736 million to $743 million, from $710 million to $725 million. It also lifted adjusted EBITDA guidance to $24 million to $34 million, from $0 to $15 million. That is the third consecutive increase for both measures. The central tension is that the newest growth leg, Optune Pax in pancreatic cancer, went backward just as the core business hit its stride.
The quality of the beat deserves some scrutiny, though it largely holds up. Revenue included $4.4 million of one-time benefits tied to higher claims approval rates in the U.S. and Germany. Even without that benefit, the quarter would have cleared consensus comfortably. Gross margin expanded to 77% from 73%, driven by better array utilization and manufacturing efficiencies, and cost of revenues was flat despite 19% active-patient growth. That is a genuine operating improvement. The expense side is less clean. Sales and marketing fell 9% and G&A fell 5%, but share-based compensation dropped 40% to $17.5 million and accounted for much of those declines. Adjusted EBITDA swung to $15.7 million from a $3.0 million loss. Unadjusted EBITDA was still a $1.8 million loss, though that compares with a $32.4 million loss a year earlier.
The operating trends beneath the headline are mostly encouraging:
- **Glioblastoma:** Optune Gio active patients reached a record 4,729, up 11% year over year and up from 4,636 in the second quarter.
- **Lung cancer:** Optune Lua jumped to 255 active patients from 207 sequentially. Japan nearly doubled to 110 patients from 64 and generated $4.1 million in Lua revenue. Management expects Japan to become the company's second-largest market.
- **Pancreatic cancer:** Optune Pax active patients slipped to 276 from 285 in the second quarter, and the product produced only $3.7 million in revenue. Management attributed the stall to practices overwhelmed by the launch of daraxonrasib, a RAS inhibitor, whose appeals burden and skin toxicity have sharply limited sales-rep access. In the second quarter, management had pointed to 50% repeat prescribers. That tone has given way to acknowledged "significant challenges," and the return to growth has been pushed to "coming quarters." U.S. Pax payer coverage also remains limited to Elevance pending inclusion in the NCCN guidelines.
The forward setup offers real catalysts, but also some softness built into the guidance. The raised full-year range implies fourth-quarter revenue of $185 million to $192 million, below the third quarter's $193.4 million. Management also cautioned that adjusted EBITDA will not improve in a straight line, with fourth-quarter launch-preparation spending ahead. On the positive side, the catalysts include:
- an FDA decision on Optune Maya for brain metastases from non-small cell lung cancer, still expected by year-end;
- completion of enrollment in the KEYNOTE D58 glioblastoma trial;
- Japanese approval of Optune Pax, with reimbursement expected in the first quarter of 2027 at potentially favorable pricing;
- two new pancreatic studies starting in the first half of 2027, one pairing Pax with Verastem's KRAS G12D inhibitor and one pairing it with daraxonrasib.
The daraxonrasib trial is notable because it reframes the competitive threat as a potential combination opportunity. That thesis remains unproven.
The market was clearly not positioned for a clean beat-and-raise. Investor sentiment deteriorated meaningfully heading into the report, falling from roughly neutral at -0.08 to -0.34. Shares closed at $14.17 the day before earnings, down 21.3% from the $18.00 open after the July report. They sat about 34% below the $21.45 52-week high set on July 24 and just 3% above the October 14 low of $13.76. The stock also traded 4.4% below its 200-day moving average of $14.82. The Earnings Whispers trend signals are mixed, with price and AVWAP readings negative while momentum is positive. That fits a stock where fundamentals have been improving faster than the share price.
Bears still have legitimate ammunition. Pax was supposed to be the next growth driver, and its U.S. launch is stalled by a competitor's disruption that Novocure cannot control. Fourth-quarter guidance also implies a sequential step down. Bulls can counter that the business no longer depends on Pax in the near term: Gio volumes are at records, Lua in Japan is accelerating, margins are expanding, and the cash position stands at $463.5 million.
The bottom line is that Novocure's core franchise and its path to profitability looked stronger than the market had priced in, while the Pax launch looked weaker than management had signaled three months ago. With sentiment depressed and shares near their inter-earnings lows, the upcoming catalysts carry more weight: the Maya decision, NCCN inclusion for Pax, and evidence that Pax patient additions can resume. Those will likely determine whether this beat-and-raise translates into a durable change in how investors value the company.
Read our earnings preview for Novocure: https://www.earningswhispers.com/article/NVCR/21111
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 12 hours | |
| 14 hours | |
| 15 hours | |
| Oct-28 | |
| Oct-21 | |
| Oct-01 | |
| Oct-01 | |
| Sep-02 | |
| Aug-14 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 |
Novocure Flashes A Bullish Signal As It Breaks Out; Have Shares 'Turned A Corner?'
NVCR +28.39%
Investor's Business Daily
|
