LKQ Edges Past Consensus But Misses The Whisper As Europe Deteriorates, Guidance Is Pulled And Leadership Is Reset
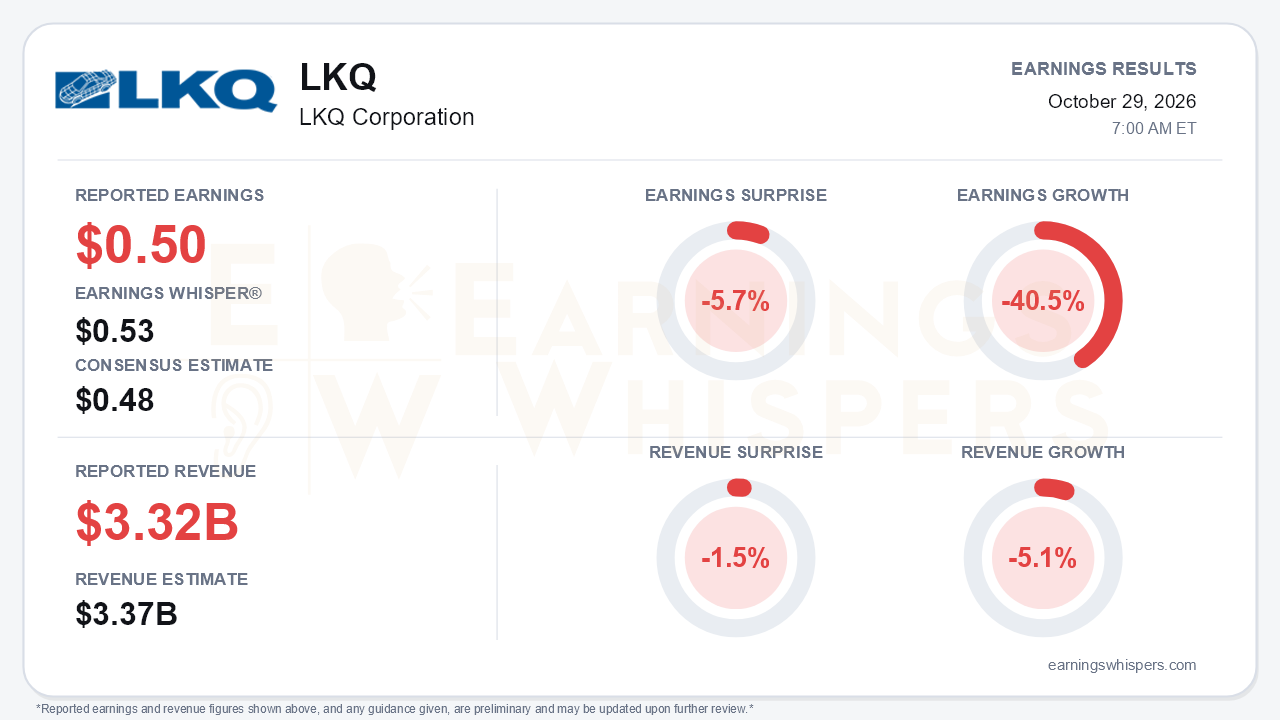
LKQ Corporation's third quarter was less about the $0.50 of adjusted EPS than about what surrounded it: an ousted CEO, withdrawn full-year guidance, a suspended strategic review and a European business that got worse. Adjusted earnings topped the $0.48 consensus but fell short of the $0.53 Earnings Whisper number, a 5.7% miss against the expectation that mattered most. Revenue of $3.319 billion missed the $3.37 billion consensus by 1.5% and fell 5.1% from a year ago, while adjusted EPS dropped 40.5%. Adjusted EPS has now declined from $0.67 in each of the first two quarters to $0.50, so the downturn is accelerating rather than bottoming. Management had called Q2 the low-water mark.
The quality of the quarter deserves scrutiny. On a GAAP basis, LKQ swung from $0.69 of diluted EPS from continuing operations to a $0.09 loss. That included $111 million of pre-tax impairments: $88 million of goodwill in Specialty and $23 million tied to the planned Romania divestiture. Gross margin slipped 110 basis points to 37.2%, while SG&A was flat in dollars on lower sales. Operating income fell 80.7% to $53 million. Total segment EBITDA dropped to $296 million, or 8.9% of revenue, from $395 million and 11.3%. Organic parts and services revenue declined 5.4%. The one clean positive was cash. Free cash flow reached $372 million, up from $60 million in Q2, and leverage held at 2.8x. Even so, nine-month free cash flow of $336 million trails last year's $573 million, which included about $50 million from the since-divested Self Service business.
Europe is the core of the problem. Segment revenue fell 10.2%, organic sales were down 9.8% and EBITDA margin collapsed to 4.6%. That compares with 7.5% in Q2, 7.8% in Q1 and 10.0% a year ago. The German ERP implementation cost roughly $43 million of EBITDA and about $95 million of revenue in the quarter. There was some operational progress, with Germany's on-time-in-full delivery rate improving to about 95% from below 80% in Q2. The commercial recovery has not followed, however. German revenue remains stuck near 85% of prior-year levels against a goal of returning to 100% by year-end, and share losses in the UK and Benelux worsened. Management signaled that more aggressive fourth-quarter pricing may be needed to win back customers, which puts pressure on volume and margin at the same time.
North America kept the story from being worse, though its growth slipped. Segment EBITDA rose to $203 million and margin expanded 40 basis points to 14.4%. A new pricing model pushed gross margin to 42.3%, and alternative parts utilization reached a record of roughly 41%. Organic revenue, however, swung to a 2.4% decline from 0.5% growth in Q2. Management attributed the drop to a large multi-shop operator changing its sourcing approach and to delivery issues outside the collision business. Specialty also lost momentum. Organic growth slowed to 0.9% from 4.5% in Q2, and margin fell to 5.5% from 6.7%, with management citing Canadian tariff tensions and pressure from fuel costs and interest rates.
The forward catalysts are now almost entirely about governance and execution. Sal Abbate, who led Veritiv through a turnaround and sale, becomes CEO on December 15. Alvarez & Marsal has been engaged, and European leadership has changed. The Board suspended the strategic review, including the Specialty sale process, so the new team can conduct its own assessment. That preserves optionality but removes a near-term value-unlock catalyst. Guidance has followed a telling path. It was reaffirmed at $2.90-$3.20 in adjusted EPS in Q1, cut to $2.60-$2.90 in Q2 and has now been withdrawn entirely. Investors have no official earnings anchor going into 2027. The Board did extend the buyback authorization and maintained the $0.30 quarterly dividend.
The market had already priced in much of this deterioration. Shares closed at $17.19 the day before the report, down 24.2% from the open after the July release. That left the stock 37.1% below its 200-day moving average and about 2% above a 52-week low of $16.85, set on October 28. The stock has fallen roughly 35% from its August 19 high of $26.28. Investor sentiment, already negative at -0.34 after the prior report, fell sharply to -0.76. The Earnings Whispers trend signals are broadly negative, consistent with deteriorating sequential growth and price momentum.
The bottom line is that LKQ's narrow beat against consensus is close to irrelevant next to a quarter that showed management lost control of the European turnaround. The company also lost its CEO and its guidance. North American margins, strong free cash flow and early operational gains in Germany give the incoming CEO something to work with. But bears have legitimate ammunition: share losses in Europe, softening North American volumes and no earnings framework. Until the new leadership team defines a credible path, the depressed share price reflects a credibility discount rather than an obvious mispricing.
Read our earnings preview for LKQ Corporation: https://www.earningswhispers.com/article/LKQ/21097
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-25 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-05 | |
| Oct-02 | |
| Sep-25 |
