Incyte's Vega Charge Drives A Smaller-Than-Feared Loss, But Jakafi Pricing Pressure Is The Real Story
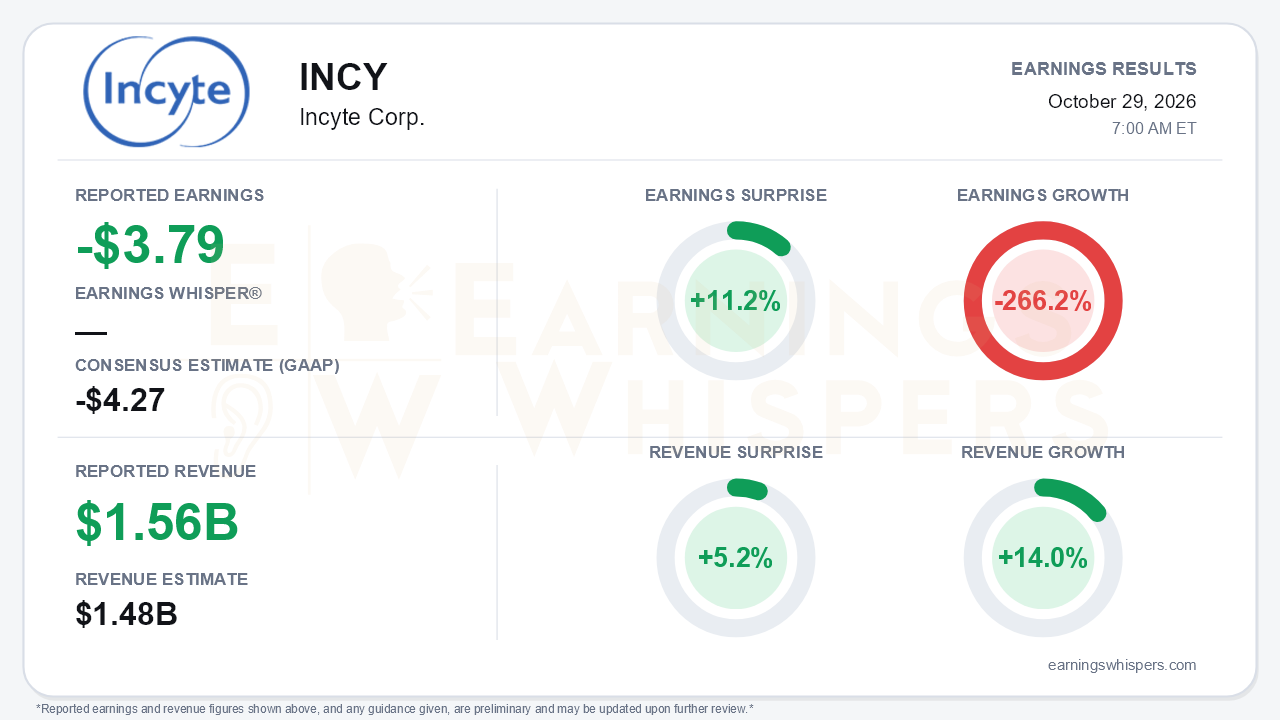
Incyte reported a third-quarter loss of $3.79 per share, which was 11.2% better than the -$4.27 consensus. Revenue of $1.557 billion rose 14.0% year over year and topped the $1.48 billion estimate by 5.2%. Earnings fell 266.2% from a year ago. That decline is almost entirely an accounting event: a one-time $1.23 billion IPR&D charge tied to the Vega Therapeutics acquisition, which closed in July and added the Phase 3 von Willebrand disease antibody latarcibart. Investors should note that the company's own figures differ from the normalized number. Incyte reported a GAAP diluted loss of $3.86 and a non-GAAP loss of $3.60, so the Earnings Whispers figure falls between the two. Either way, the headline loss says little about the operating business. The more important development is that growth kept decelerating, and Incyte's largest product is now growing in the low single digits even as demand strengthens.
Strip out Vega and the quarter looks solid. GAAP operating income excluding the upfront charge rose 18%. GAAP R&D excluding Vega grew 11%, and SG&A grew 11% on pre-launch spending, both below the 14% top-line growth rate. Cost of sales held at 8% of net sales. Cash and marketable securities rose to $3.9 billion from $3.6 billion at year-end, even after the $1.25 billion Vega payment. Incyte also raised full-year guidance:
- **Total net sales:** $5.21-$5.30 billion, up from $5.13-$5.26 billion.
- **Opzelura:** $1.10-$1.12 billion.
- **Hematology and Oncology:** $890-$910 million.
- **Jakafi and operating expenses:** unchanged.
The raise looks more like a move toward Street expectations than a reset above them.
The central tension sits inside Jakafi. Net sales of $827 million grew just 4%, down from 7% in each of the first two quarters. Paid demand actually accelerated, rising 12% versus 9% in Q2 and 6% in Q1. Management attributed the gap to pricing dynamics, including the CMS GENEROUS model. Separately, Incyte agreed in August to give state Medicaid programs access to Jakafi at prices aligned with other industrialized nations, in exchange for expected exemption from proposed GUARD and GLOBE pricing models. That trade buys policy visibility but caps realized price on the franchise that still produces most of the profit. The broader trend is also slowing:
- **Total net sales growth:** 20% in Q1, 17% in Q2 excluding one-time items, and 14% in Q3.
- **Ex-Jakafi growth:** 63%, then 44%, then roughly 30% on $490 million of sales.
The diversification story is intact, but the steep part of the curve is behind it.
The quality of the Opzelura beat also deserves scrutiny. Reported growth of 36% to $255 million benefited from improved gross-to-net following the CMS Medicaid rebate settlement, and pro forma growth was about 21%. U.S. Opzelura still grew 45%, and the EU launch in moderate atopic dermatitis adds a new leg. Hematology and Oncology rose 38%, led by:
- Zynyz, up 157%.
- Niktimvo, up 47%.
- Monjuvi/Minjuvi, up 30%.
Not everything grew, despite the upbeat framing on the call. Iclusig fell 11% and Pemazyre fell 7%. Jakafi XR offered a genuine positive. It posted $15 million, reached roughly 3% of the franchise in September, and is now expected to exceed 80% formulary coverage by year-end, up from the prior 50-70% goal. Management is targeting about $50 million in XR sales for the year, the top of the earlier range.
The catalyst calendar is dense and front-loaded:
- **Fourth quarter:**
- Phase 3 readouts for povorcitinib in prurigo nodularis and ruxolitinib cream in hidradenitis suppurativa.
- First-line myelofibrosis data for the mutant-CALR antibody INCA033989.
- An asthma proof-of-concept readout.
- An EC decision on povorcitinib in HS.
- **First quarter of 2027:** potential U.S. approvals for povorcitinib in HS and Monjuvi in first-line DLBCL.
The GI oncology push, built on the KRAS G12D inhibitor and the TGFβR2×PD-1 bispecific, is more distant, with pivotal data in 2028-2029. Bears have legitimate ammunition here. Management has flagged possible margin compression into 2029, and the company discontinued the CDK2 inhibitor's Phase 3 in platinum-resistant ovarian cancer in favor of a first-line maintenance study. Incyte is spending heavily to bridge to the post-Jakafi era while Jakafi's pricing erodes.
Investors entered the report with noticeably cooler expectations. Earnings Whispers sentiment fell from 0.28 at the prior report to -0.06, a meaningful shift from modestly positive to slightly negative. The stock has gone round-trip. It set a 52-week high of $132.60 on the day of the July report, slid to $107.78 in mid-October, right at its 200-day moving average, and recovered to $116.87 ahead of this release. That price is 1.8% below the post-July opening and 11.9% below the high, but still 8.3% above the 200-day average. Trend readings are mixed: momentum has turned positive while the AVWAP trend remains negative, consistent with a stock that is rebounding without having reclaimed its summer enthusiasm.
The bottom line is that Incyte's headline loss is an acquisition artifact and the beat on both lines is real. The quarter's actual message is a business with accelerating demand but decelerating revenue growth, as pricing pressure dilutes Jakafi and the ex-Jakafi engine matures. The modest guidance raise and Jakafi XR traction help. The near-term investment case now rests heavily on a cluster of year-end Phase 3 readouts and early-2027 approvals that must prove the pipeline can outrun Jakafi's slowing net growth.
Read our earnings preview for Incyte Corp.: https://www.earningswhispers.com/article/INCY/21088
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| 6 hours | |
| Oct-26 | |
| Oct-25 | |
| Oct-24 | |
| Oct-24 | |
| Oct-22 | |
| Oct-21 | |
| Oct-18 | |
| Oct-09 | |
| Oct-08 | |
| Sep-28 | |
| Sep-25 | |
| Sep-25 |
