Hippo Beats And Raises Again, But Mix Shift Is Pushing Underlying Losses Higher
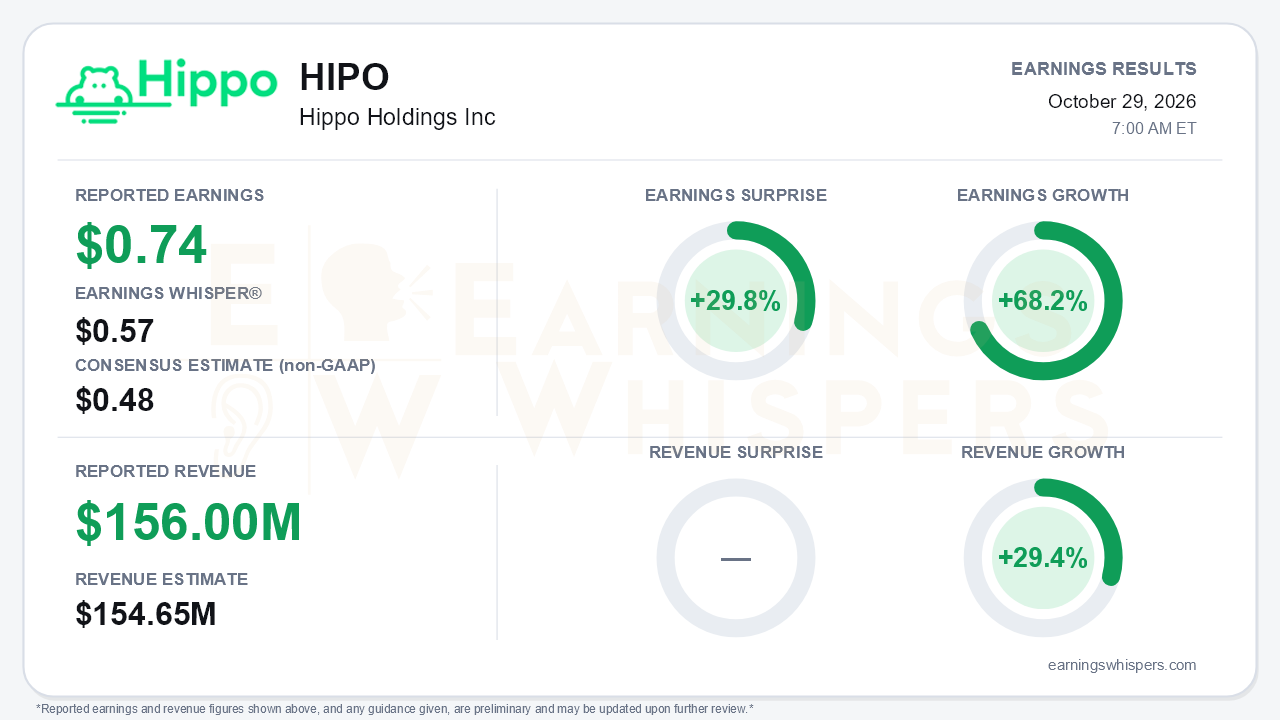
Hippo Holdings delivered its third straight beat-and-raise quarter, reporting adjusted earnings of $0.74 per share against a $0.48 consensus and a $0.57 Earnings Whisper number. That was a 29.8% surprise. Revenue of $156.0 million rose 29.4% year over year and edged past the $154.65 million consensus by 0.9%. The more important number may be guidance. Management lifted full-year adjusted net income guidance to $77-80 million from $62-70 million and tightened the combined ratio outlook to 97-98% from 99-101%. The central tension is that the bottom-line outlook keeps rising while the underlying loss trend is moving in the wrong direction.
The quality of the beat deserves scrutiny on several fronts. Earnings Whispers' normalized figures show earnings growth of 68.2%. On the company's own adjusted basis, however, the gain was more modest: adjusted net income rose 9.3% to $20 million, and adjusted EPS increased from $0.70 to $0.74. Adjusted net income also slipped slightly from $21 million in the second quarter. On a GAAP basis, net income fell to $9 million, or $0.33 per share, from $98 million, or $3.77. That decline is mostly noise, because the prior-year quarter included a $91 million net gain on the sale of the homebuilder distribution network.
The operating story is real but uneven. Gross written premium jumped 60% to $498 million. Casualty grew 146% to $188 million and commercial multi-peril rose 63% to $108 million. Homeowners growth accelerated to 11% from 7% in the second quarter. Revenue growth has also stepped up, from 10% in the first quarter to 23% in the second and 29% now. The expense ratio did most of the heavy lifting. It fell to 41.7% from 52.0% a year ago and 45.4% last quarter, as net earned premium grew 29% against 12% growth in the expense base.
Beneath that, the loss picture deteriorated. The accident-year loss ratio excluding catastrophes rose to 49.9% from 45.8% in the second quarter and roughly 44% in the first. Management tied the increase to mix shift toward casualty and CMP and to normalizing business-owner-policy losses. The combined ratio of 98.4% improved only one point year over year and was worse than the second quarter's 95.8%. That came despite a reasonable 6.5% catastrophe loss ratio.
The net premium trend is also cooling:
- Net written premium growth slowed to 26% from 71% in the second quarter.
- Retention dropped to 30%, below the full-year guide of roughly the mid-30s.
- Management now expects blended retention near 30% in 2027.
Lower retention is a deliberate trade, since it means less volatility and more fee income; commission and fee income rose 45% to $19.7 million. But it caps how much of the gross growth reaches the income statement. The full-year revenue guide rose only $5 million, while gross written premium guidance moved up to $1.70-1.75 billion.
The guidance raise also leans partly on a lower catastrophe assumption. The full-year cat load was cut to 8% from 10%, which is defensible given a 6.0% year-to-date cat ratio. Still, it means some of the combined ratio improvement reflects benign weather rather than better underwriting. The new adjusted net income range, set against $58.2 million earned through nine months, implies a fourth quarter roughly in line with the third.
The forward catalysts are strategic rather than near-term:
- A Greenlight Re partnership positions Hippo as a preferred program carrier for emerging MGAs, with co-investment.
- A broader services suite covers claims administration, customer support and technology for program partners.
- Homeowners distribution is expanding into 14 more states with far less engineering effort per state.
- The Clara AI claims-intake agent now handles 9 of 10 first notices of loss.
Management reiterated its 2028 targets of more than $2.5 billion in gross written premium and over $140 million in adjusted net income, and said capital is sufficient to reach them. Bears have legitimate ammunition, though:
- The property market is softening, with plentiful reinsurance capacity.
- Casualty competition is rising.
- A slower housing market is weighing on the builder channel.
- Book value per share of $17.62 is up 3.8% from year-end but was flat on the call's comparison, because $12.5 million of unrealized investment losses produced a comprehensive loss in the quarter.
The market had already moved toward the bullish case. Shares stood at $37.71 before the report, up 17.8% from the opening price after the July release and 28.3% above the 200-day moving average. The stock rallied roughly 28% off a late-September low of $29.56 and set a 52-week high of $39.39 on October 22, finishing 4.3% below it. Investor sentiment improved from -0.18 to +0.02, moving from mildly skeptical to roughly neutral rather than euphoric. The Earnings Whispers trend signals are uniformly positive, consistent with that run.
The bottom line is that Hippo cleared expectations comfortably and raised its profit outlook again, and the expense leverage and diversification story remains credible. However, the improvement is increasingly coming from operating leverage, fee income and a lighter catastrophe assumption. Core loss ratios are drifting higher as the book shifts toward casualty and commercial lines in a softening market. With the stock trading near its highs, the next leg depends on proving that mix-driven loss pressure stabilizes before expense gains run out.
Read our earnings preview for Hippo Holdings Inc: https://www.earningswhispers.com/article/HIPO/21081
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-21 | |
| Oct-14 | |
| Oct-06 | |
| Sep-24 | |
| Sep-21 | |
| Aug-27 | |
| Jul-30 | |
| Jul-29 | |
| Jul-23 | |
| Jul-07 | |
| Jun-30 | |
| Jun-25 |
