APi Group Raises Guidance Again As Organic Growth Hits 15.7%, But Margin And Cash Conversion Lag The Top Line
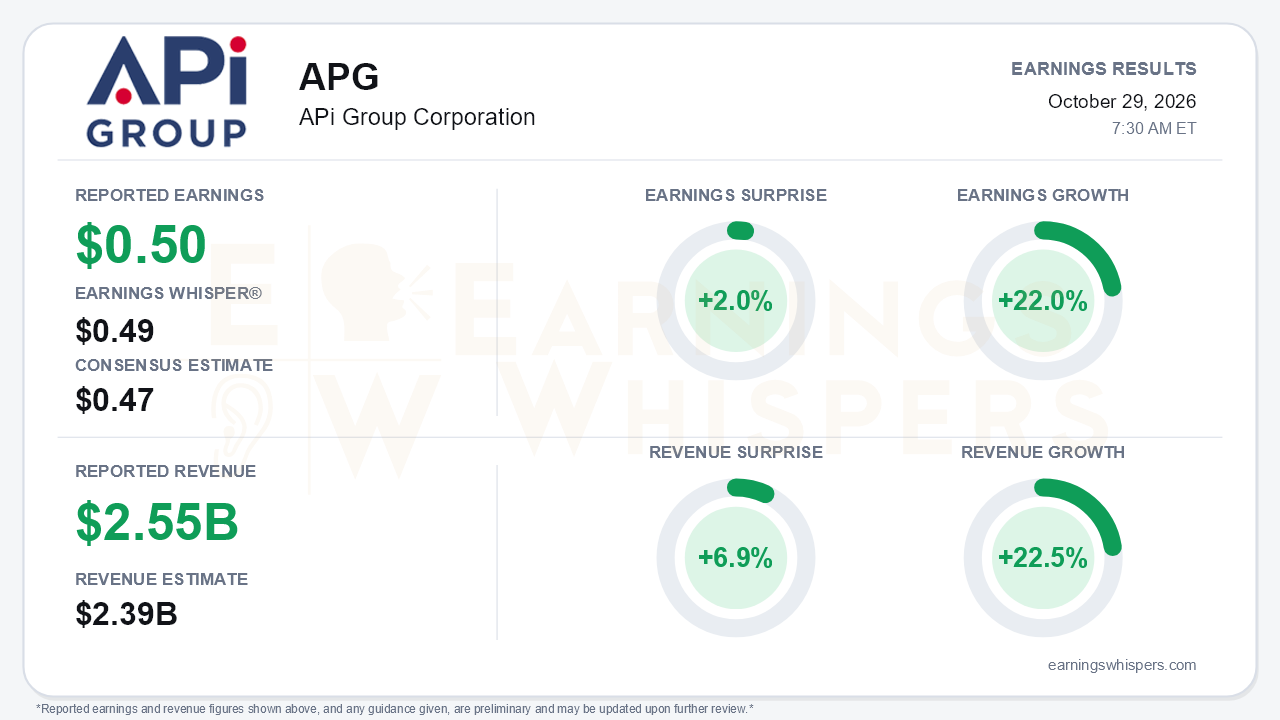
APi Group delivered a quarter defined by top-line strength. Adjusted EPS of $0.50 topped the $0.47 consensus and the $0.49 Earnings Whisper number by 2.0%, while revenue of $2.554 billion beat the $2.39 billion consensus by 6.9%. Earnings grew 22.0% year over year and revenue grew 22.5%, with organic growth accelerating to 15.7% from 10.1% in the second quarter and 10.4% in the first. Management raised full-year guidance for the third time this year. The central tension is that the 6.9% revenue beat translated into only a 2.0% EPS beat. APi is growing faster than expected, but less of each incremental dollar is reaching the bottom line than the revenue line alone would suggest.
The quality of the beat deserves scrutiny. Adjusted gross margin fell 120 basis points to 30.3%. The company attributed the decline to project and business mix and to rising material, fuel and other costs, an inflation headwind now explicitly called out. Safety Services, the higher-margin franchise, saw adjusted gross margin slip 110 basis points to 36.2%. Adjusted EBITDA margin still expanded 20 basis points to 13.7%, but that came entirely from SG&A leverage: adjusted SG&A fell to 17.6% of revenue from 19.3%. Below the operating line, net interest expense rose to $45 million from $34 million, and adjusted diluted shares increased to 438 million from 424 million, both diluting the per-share result. On a GAAP basis, diluted EPS rose to $0.24 from $0.20. Acquisitions contributed 6.9 points of reported growth.
The operating trends beneath those margins are genuinely improving:
- **Specialty Services:** Organic growth reached 29.9%, up from 22% in Q2. Segment earnings margin widened 60 basis points to 12.5% on disciplined project selection and pricing.
- **Safety Services:** Organic growth nearly doubled to 8.8% from 4.7% in Q2, well above the mid-single-digit pace management had framed earlier in the year.
- **International Safety:** The business returned to organic growth after a flat Q2, and management is targeting mid-single-digit growth in 2027.
- **Backlog and data centers:** Backlog sits above $5 billion, a record. Data centers are now expected to represent 12% or more of 2026 revenue, up from about 10% in February. Completed facilities are converting into recurring inspection, service and monitoring work.
On the call, management struck its most confident tone of the year, describing a "position of strength" heading into 2027.
The guidance progression captures both sides of the story. Full-year revenue guidance is now $9.20 to $9.25 billion, up from $8.4 to $8.6 billion in February. Organic growth guidance has climbed from 5% to roughly 11%, and adjusted EBITDA guidance rose to $1.235 to $1.255 billion. Yet the implied full-year EBITDA margin has drifted to 13.5% from 13.8% in the original outlook, short of the 60 to 70 basis points of expansion targeted earlier. Free cash flow conversion guidance was trimmed to about 110% from 115%, and the interest expense outlook rose to $155 million from $130 million.
The balance sheet has also changed materially. Net leverage climbed to 2.4x from 1.6x after roughly $1.7 billion of capital deployed. That total includes $1.36 billion of acquisitions and $252 million of buybacks through the third quarter, plus another $143 million repurchased so far in Q4. More than $500 million of annualized acquired revenue from CertiSight, Onyx, WTech and Evergreen rolls into full-year contribution in 2027. Management expects higher-margin project pricing now entering backlog to support margin expansion next year.
There are offsetting risks. Management flagged data center moratoria and local opposition as a watch item. It also pushed back on an analyst's suggestion that double-digit organic growth in 2027 had been committed, saying no 2027 guide will come until February.
Investor sentiment entered the report modestly positive but softened, slipping to 0.0553 from 0.0908 since the July report. Shares had gone essentially nowhere, up 1.2% from the post-July open to $41.34. In between, the stock swung from a mid-August high of $44.95 to a September low of $35.57. It entered earnings 1.4% below its 200-day moving average and about 8% below the quarter high. That is a stock the market has not been rewarding for repeated guidance raises. Momentum and AVWAP trend readings are positive, while the price trend remains neutral.
The bottom line is that APi's growth story strengthened meaningfully this quarter. Accelerating organic growth in both segments, a recovering International business and a record backlog justify the third guidance raise. Bears still have legitimate ammunition, however: gross margin is compressing, the full-year margin target keeps edging lower, cash conversion was cut and leverage has risen sharply. Until the margin expansion management expects from new backlog pricing actually shows up, the stock's range-bound behavior suggests investors want proof that faster growth can also be more profitable growth.
Read our earnings preview for APi Group Corporation: https://www.earningswhispers.com/article/APG/21024
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 11 hours | |
| 11 hours | |
| Oct-21 | |
| Oct-15 | |
| Sep-30 | |
| Sep-22 | |
| Sep-01 | |
| Aug-26 | |
| Aug-13 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jul-02 |
