Albany International Beats As CH-53K Reset Clears The Deck, But One-Offs Inflate The Quarter And Core Margins Stall
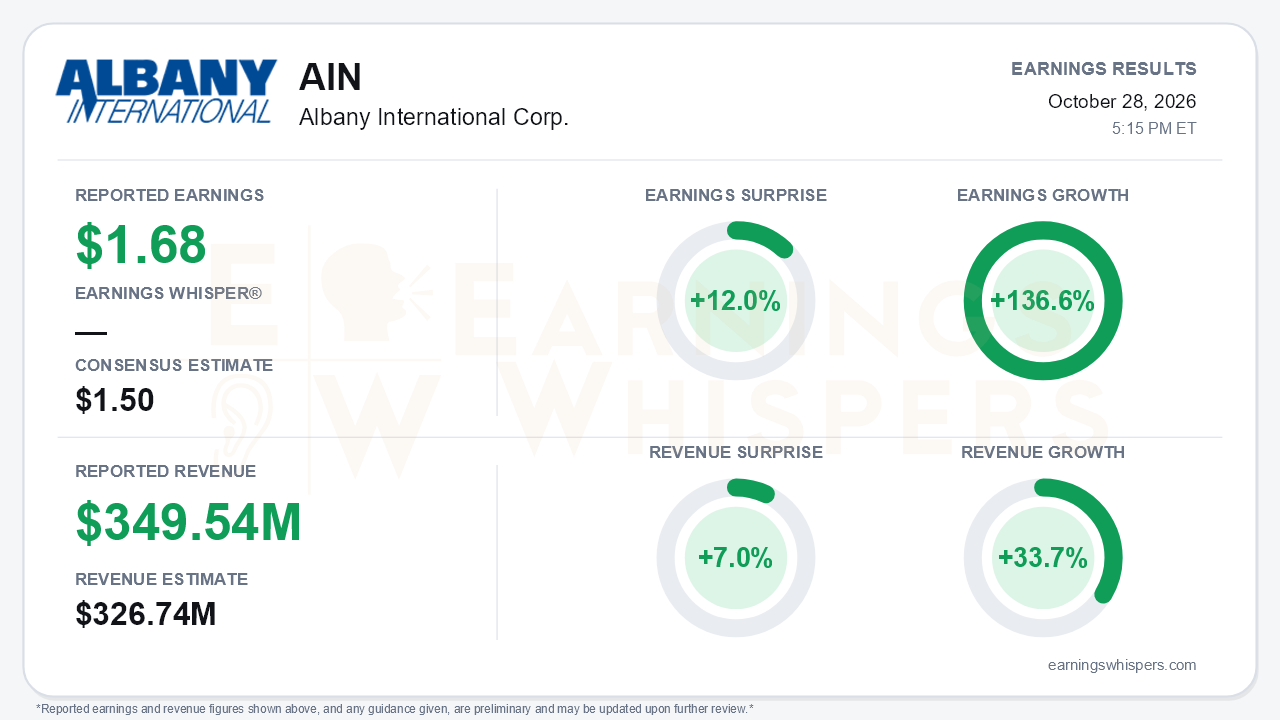
Albany International (NYSE: AIN) delivered a headline beat that looks emphatic: adjusted EPS of $1.68 topped the $1.50 consensus by 12.0%, and revenue of $349.54 million beat the $326.74 million estimate by 7.0%. Revenue grew 33.7% year over year to a company record, and earnings grew 136.6% from a year-ago adjusted loss of $(3.29) per share. The more important development, however, is not the size of the beat. Albany concluded the strategic review of its Amelia Earhart Drive (Salt Lake City) facility and renegotiated the Sikorsky CH-53K contract. That moves the story from managing a legacy problem to pursuing growth. Much of the quarter's upside came from that resolution rather than from the run-rate business, and that is the central tension.
The quality of the beat deserves scrutiny. The company disclosed that the Amelia Earhart Drive adjustments contributed $11.6 million of revenue, $44.4 million of EBITDA and $0.88 of diluted EPS, net of an $11.0 million depreciation catch-up. That is more than half of the $1.68 adjusted figure. The adjusted EPS definition does not strip out the benefit, because management now treats CH-53K reserve changes as part of the program's operating performance. Adjusted EBITDA of $100.1 million (28.6% margin) and Engineered Composites' 36.5% segment margin are therefore heavily flattered. Free cash flow of $36.5 million was a sharp swing from negative readings in the first two quarters, but the call noted help from tariff refunds and a vendor credit. Nine-month free cash flow of $18.3 million still trails last year's $30.0 million.
Beneath the one-offs, the operating picture is mixed:
- **Engineered Composites revenue (positive):** Revenue reached a record $179.7 million, up 107% in constant currency. It rose sequentially from $150.8 million in Q2 and $145.4 million in Q1, driven by LEAP, CH-53K and missile programs.
- **Engineered Composites margin (flat to slightly lower):** Management put the underlying segment margin at roughly 12.5%, slightly below the 13.3% cited for Q2. Part of the revenue strength came from a pull-forward of defense-prime tooling that may borrow from the fourth quarter.
- **Machine Clothing (weaker):** Revenue fell 3.0% in constant currency to $169.8 million, down from $178.7 million in Q2. Adjusted EBITDA margin compressed to 27.2% from 31.0% a year ago on lower volume and unfavorable geographic mix. Management cited softness in South America, customer consolidation in the Americas and limited visibility in China. The full-year Machine Clothing outlook remains slightly down, after the company called demand stable earlier in the year.
The forward narrative is where the call earned credibility. Management laid out an explicit Engineered Composites margin path: about 12.5% in Q4 and early 2027, rising to the mid-teens exiting 2027 as the CH-53K contract modifications take effect. Notably, earlier guidance had tied mid-teens margins to divesting the Salt Lake site, which Albany is now keeping. New catalysts include:
- a $21.2 million IBAS award to vertically integrate ceramic matrix composites;
- a hypersonic teaming agreement with Lockheed Martin;
- inclusion in the Wing of Tomorrow program;
- a missile and hypersonic revenue timeline pulled in to 2027-2028;
- greater openness to acquisitions;
- a December investor day that will set 2030-plus targets.
The risks are also clear. Retaining Salt Lake keeps structures exposure on the books. An acting CFO is now in the seat. The fourth-quarter tax rate rises to about 29.5%. Fourth-quarter guidance of $325-335 million in revenue and $0.65-0.75 in adjusted EPS is in line, a step above the prior quarter's revenue range but a reminder of how far normalized earnings sit below the Q3 headline.
The market setup is more complicated than the surprise implies. Shares closed at $62.47 on the report date, down 11.1% from the $70.25 opening after the August report. That leaves the stock just 1.3% above its 200-day moving average of $61.66, so investors had been discounting the story rather than chasing it. Investor sentiment remains negative at -0.44 but improved modestly from -0.49 ahead of the prior report. That reads as slightly less skepticism, not a change of heart. The trend readings are mixed: price trend negative, AVWAP trend positive.
The bottom line is that Albany's quarter matters more for what it removed than for what it earned. The CH-53K renegotiation eliminates the biggest overhang and gives management room to sell an aerospace and defense growth story. However, the record EPS was built substantially on a one-time program reset. Underlying composite margins are flat, and Machine Clothing is still drifting lower. Bulls now have a cleaner narrative and a concrete margin roadmap. Bears can fairly point out that the run-rate business has yet to show the improvement the headline suggests. The December investor day will need to bridge that gap.
Read our earnings preview for Albany International Corp.: https://www.earningswhispers.com/article/AIN/20895
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-14 | |
| Oct-05 |
Bayer plans $2.2bn pharmaceutical manufacturing facility in Ohio, US
AIN
Pharmaceutical Business Review
|
| Sep-29 | |
| Sep-03 | |
| Sep-01 | |
| Aug-31 | |
| Aug-24 | |
| Aug-24 |
