Adamas Trust Holds EAD At $0.30 And Raises Its Dividend, But A 20% Book Value Hit Overshadows The Quarter
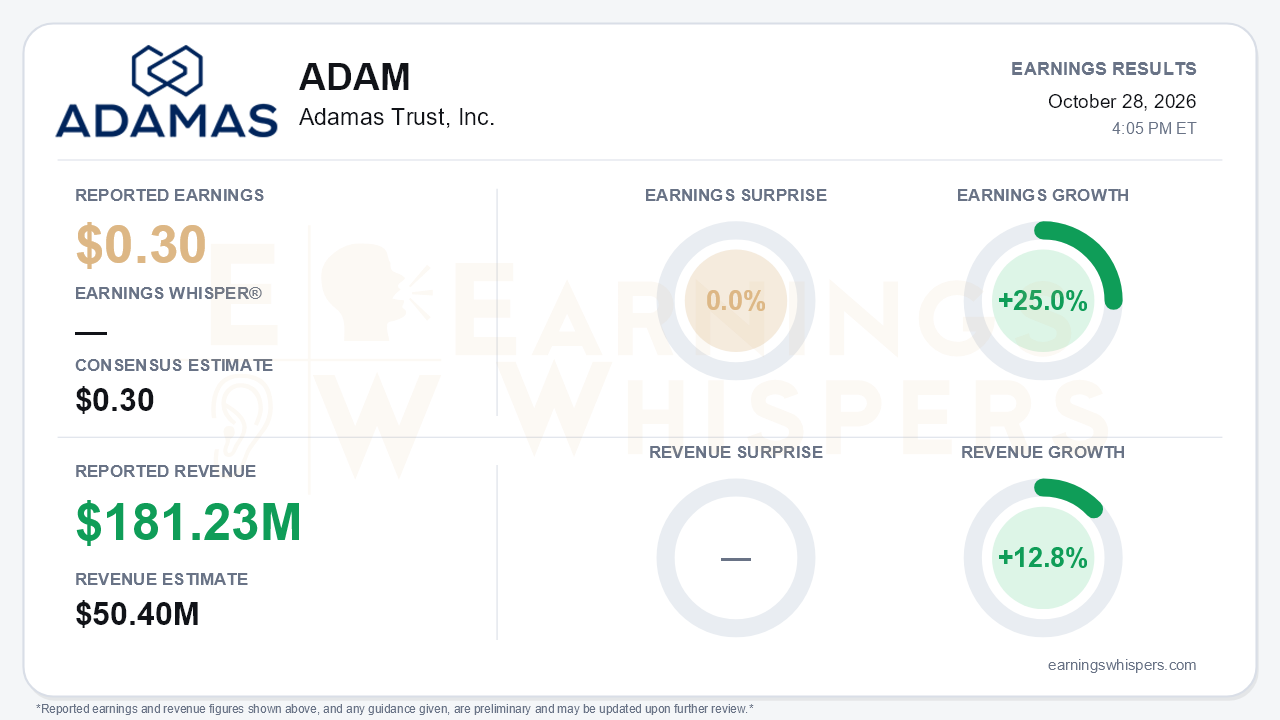
Adamas Trust delivered exactly what consensus expected on recurring earnings: earnings available for distribution (EAD) of $0.30 per share, matching the $0.30 estimate and up 25.0% from a year ago. That headline obscures the real story of the quarter. Under GAAP, the company lost $1.89 per share. Adjusted book value fell 19.6% to $8.88 from $11.05, and GAAP book value dropped to $7.93 from $10.16. The economic return on adjusted book value was -16.9%. Recurring income held up and the dividend went up, yet the balance sheet absorbed its worst hit in at least five quarters. That gap between earnings power and capital erosion is the central tension.
The revenue comparison needs context. Reported revenue of $181.23 million beat the $50.4 million consensus by 259.6% and grew 12.8% year over year. The reported figure, however, is gross interest income. The consensus appears to be built on a net basis that more closely resembles adjusted net interest income, which came in at $51.5 million. Investors should not read the surprise as an operating blowout. Adjusted net interest income did inch higher, from $50.3 million in Q2 and $48.2 million in Q1. Agency adjusted net interest income rose about 7% sequentially. EAD has now covered the dividend for seven straight quarters, including the newly raised $0.30 payout, up from $0.27. Beneath that stability, however, profitability per dollar of assets is slipping:
- Net interest spread narrowed to 1.40% from 1.48% in Q2 and 1.53% in Q4 2025.
- Asset yields drifted down to 5.95%.
- GAAP net interest income actually declined 2.8% sequentially.
The book value damage came from the Agency portfolio. According to the call, Agency positioning drove roughly 78% of the decline. The company carried a high-coupon specified-pool book, averaging about a 5.5% coupon, alongside a 1.4-year duration gap. When the Fed hiked 25 basis points in September and the 10-year Treasury pushed above 5%, convexity and duration losses compounded. Management acknowledged a severity it did not anticipate. The response was defensive:
- The company added short TBA positions late in the quarter.
- Agency leverage was cut to 5.9x from 8.3x.
- Company recourse leverage fell to 4.8x from 5.5x.
The tone shift from Q2 is stark. Last quarter's celebratory messaging about peer outperformance and record issuance gave way to explanation and repositioning. The prior path toward a 15% ROE target went unmentioned.
The Constructive origination platform added a second source of disappointment:
- Mortgage banking income fell to $10.9 million from $16.2 million.
- The unit swung to a $1.7 million standalone loss from a $2.0 million profit in Q2.
- Originations slipped to $406 million.
That loss included a $2.6 million legacy repurchase reserve, the second such build after Q4 2025. Management again characterized it as one-off, a claim that gets harder to accept the second time. Management also flagged BPL-rental origination volumes as potentially challenged in Q4. Financing costs are moving the wrong way as well. The October BPL securitization priced 67 basis points wider than the Q3 deal, and new senior notes carry a 9.6% coupon.
The constructive case rests on repricing and liquidity:
- **Returns on new capital:** Management now sees mid-to-high-teens returns on new investments, up from the 15%+ target cited in Q2.
- **Book value recovery:** Adjusted book value was up roughly 4% quarter-to-date as of October 26, after the TBA short was cut 76%.
- **Liquidity:** Cash rose to $259 million and excess capacity to $447 million, leaving room to re-lever into wider spreads.
- **Credit and financing:** BPL-rental credit remains clean, with 60+ day delinquencies at 1.4%. Roughly 98% of that book is now in non-recourse term financing.
Bears still have legitimate ammunition. Rates remain volatile, more Fed hikes are being priced into 2027, and spread compression is likely to continue as higher-yielding bridge and multifamily assets run off.
The market has already been pricing this pain. Shares closed at $7.78 on report day, 14.7% below the $9.12 opening price after the July report. The stock sits about 9% below its 200-day moving average of $8.55, and the AVWAP trend remains negative. The stock now trades below even the reduced GAAP book value and well beneath adjusted book value of $8.88. Investor sentiment was essentially unchanged and firmly negative, edging from -0.61 to -0.59. Investors entered the report expecting trouble and did not meaningfully revise that view.
The bottom line is that Adamas protected its recurring earnings and dividend while losing a fifth of its adjusted book value to a rate-and-convexity shock that management admits it underestimated. The in-line EAD and the oversized revenue surprise say little about the quarter's real outcome. What matters now is whether the early Q4 book value rebound and redeployment into mid-to-high-teens opportunities can offset narrowing spreads, a soft Constructive platform and rising financing costs. Until that becomes visible, a discount to book and skeptical sentiment look like a reasonable reflection of the risk.
Read our earnings preview for Adamas Trust, Inc.: https://www.earningswhispers.com/article/ADAM/20892
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-19 | |
| Sep-22 | |
| Sep-17 | |
| Sep-10 | |
| Aug-12 | |
| Aug-11 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-14 | |
| Jun-11 |
