Arxis Beats And Raises A Third Time, But Its Early 2027 Outlook Tells Investors Q3 Was A Peak, Not A Run Rate
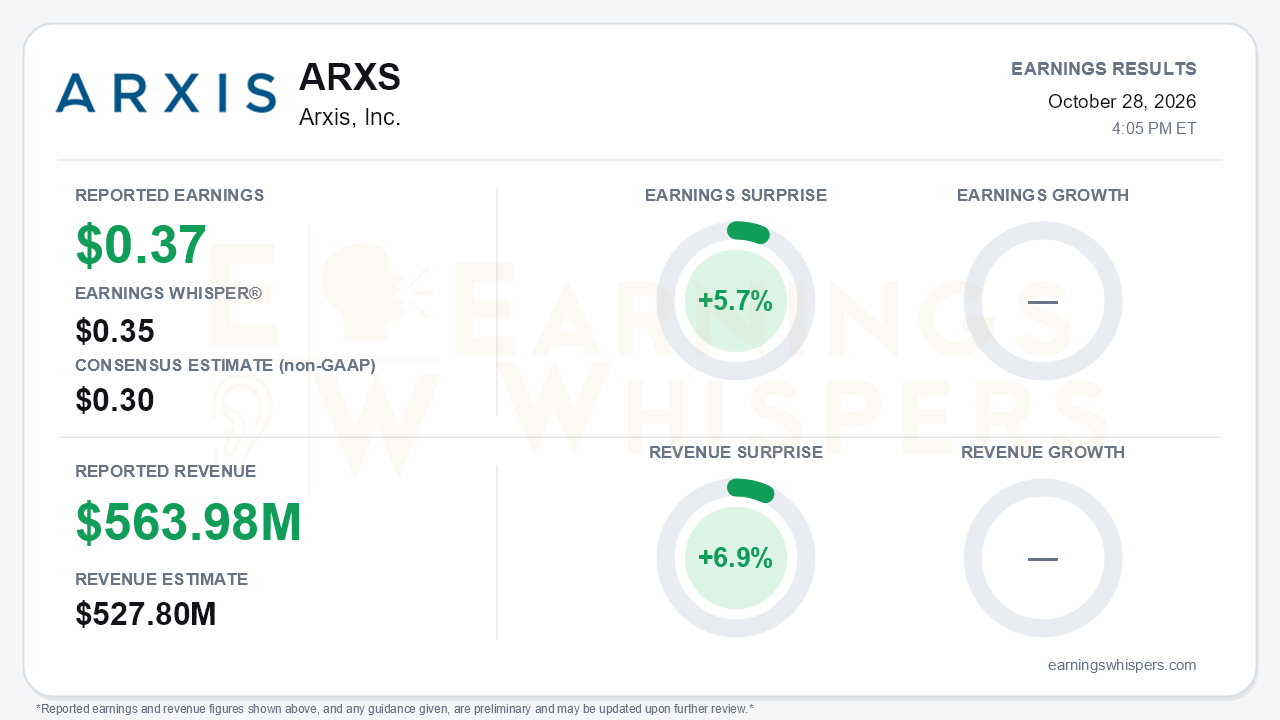
Arxis delivered another clean beat-and-raise, and then told investors not to extrapolate it. Adjusted earnings of $0.37 per share topped the $0.30 consensus and the $0.35 Earnings Whisper number, a 5.7% beat. Revenue of $563.98 million exceeded the $527.8 million consensus by 6.9%. Sales rose 36%, including 29% organic growth. Full-year 2026 guidance went up for the third consecutive quarter, and management issued 2027 targets earlier than it had signaled in July. The central tension is that the same guidance confirming Arxis's earnings power also marks 2026 as the high-water mark for growth and margins. Management guided 2027 organic growth to 10% to 15%, down from roughly 22% this year.
The beat came from the operating line, not just financial engineering, though the GAAP and adjusted figures diverge sharply. GAAP diluted EPS was $0.20. Net income of $84 million compares with a $10 million loss a year ago. Part of that swing came below the operating line:
- **Interest expense** fell to $17.9 million from $48.3 million after the company repaid debt with IPO proceeds.
- **Tax expense** was lower.
Operating income still rose 45% to $133 million. Gross profit grew far faster than revenue, so the operating leverage is real.
The gap to adjusted earnings is wide and worth scrutiny. Adjusted net income of $160 million excludes:
- $31 million of share-based compensation;
- $41 million of intangible amortization;
- $11 million of deal expenses;
- $12.8 million of other items, including a $12.0 million charge tied to a Jacksonville business matter.
Cash flow supports the quality argument. Free cash flow more than doubled to $150 million, and net leverage dropped to 1.6x from 1.8x in June and 4.2x at year-end 2025.
The quarter-to-quarter trajectory explains why expectations have chased the stock higher:
| Metric | Q1 | Q2 | Q3 |
|---|---|---|---|
| Organic growth | 17% | 21% | 29% |
| Adjusted EBITDA margin | 38.2% | 42.2% | 45.4% |
The full-year revenue guidance midpoint has climbed from $1.87 billion to $1.97 billion and now $2.06 billion. Adjusted EBITDA guidance has moved from $725 million to $860 million, and the implied margin has risen to roughly 41.7% despite 30 to 40 basis points of acquisition dilution. Management attributed the outsized growth to "ramp capture." That means simultaneous production ramps on Patriot and other missile programs, F-35 electronic warfare, the 737, and industrial platforms. All three end markets are now growing about 20% or more. Pricing also ran at a high-single-digit rate in Q3, above the company's normal mid-single-digit level.
That pricing detail is where the bear case begins. Management explicitly said the 45.4% margin is not a new standard. The guidance implies Q4 margin roughly 500 basis points lower sequentially, for three reasons:
- pricing reverts to mid-single digits;
- fewer working days and planned maintenance reduce leverage;
- acquisition dilution reaches about 100 basis points.
Incremental conversion margins, which had been elevated by 2024-25 acquisitions, are expected to revert toward 50%. Management's 2027 framework is built from mid-single-digit price, mid-single-digit new business and 0% to 5% from ramps. It produces revenue of $2.4 billion to $2.5 billion and adjusted EBITDA of $1.01 billion to $1.06 billion at a 42.1% to 42.4% margin. That is still healthy growth and modest margin expansion versus 2026. But it is a clear deceleration from the pace that drove three straight raises. The early missile long-term agreement talks that could extend the defense ramp remain conversations, with nothing signed.
Acquisitions are the other lever. Arxis closed Omnetics, Schatz Bearing and StratEdge during the quarter, bringing the year-to-date total to six deals. Schatz and StratEdge cost a combined $151 million, which management said was under 10 times 2027 estimated EBITDA. With $494 million of cash, falling leverage and Arcline's backing, M&A should keep adding to reported growth even as organic growth slows. The 2027 guide already assumes 17% to 21% reported growth against 10% to 15% organic. Investors should note that Arcline-affiliated Class B shares heavily outnumber the public Class A float, which shapes governance and capital-allocation decisions.
The market has rewarded the trajectory. Shares have gained 20.9% since the open after the July report, to $54.13, and sit about 17.8% above the 200-day moving average of $45.97. Investor sentiment improved substantially, moving from roughly neutral at -0.06 to a moderately positive 0.36. Price trend measures anchored to recent volume are also positive. That leaves the stock entering the post-report period with considerably higher expectations than it carried three months ago. That matters because the forward message is about normalization rather than further acceleration.
The bottom line is that Arxis posted an excellent quarter on every operating measure: accelerating organic growth, record margins, surging free cash flow and rapid deleveraging. Raised guidance and a credible 2027 outlook reinforce that the business can compound. But management itself framed Q3 as a peak, with pricing, margins and growth all set to step down. With sentiment and the share price now well ahead of where they stood after the last report, the debate shifts from whether Arxis can beat to how the market prices a slower, still-solid growth algorithm supplemented by acquisitions.
Read our earnings preview for Arxis, Inc.: https://www.earningswhispers.com/article/ARXS/21007
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-15 | |
| Sep-03 | |
| Aug-18 | |
| Aug-10 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jun-02 | |
| May-27 | |
| May-14 |
