Butterfly Network Beats And Raises Again, But Its Record Quarter Rests Heavily On Embedded Licensing While The Core Business Grows Slowly
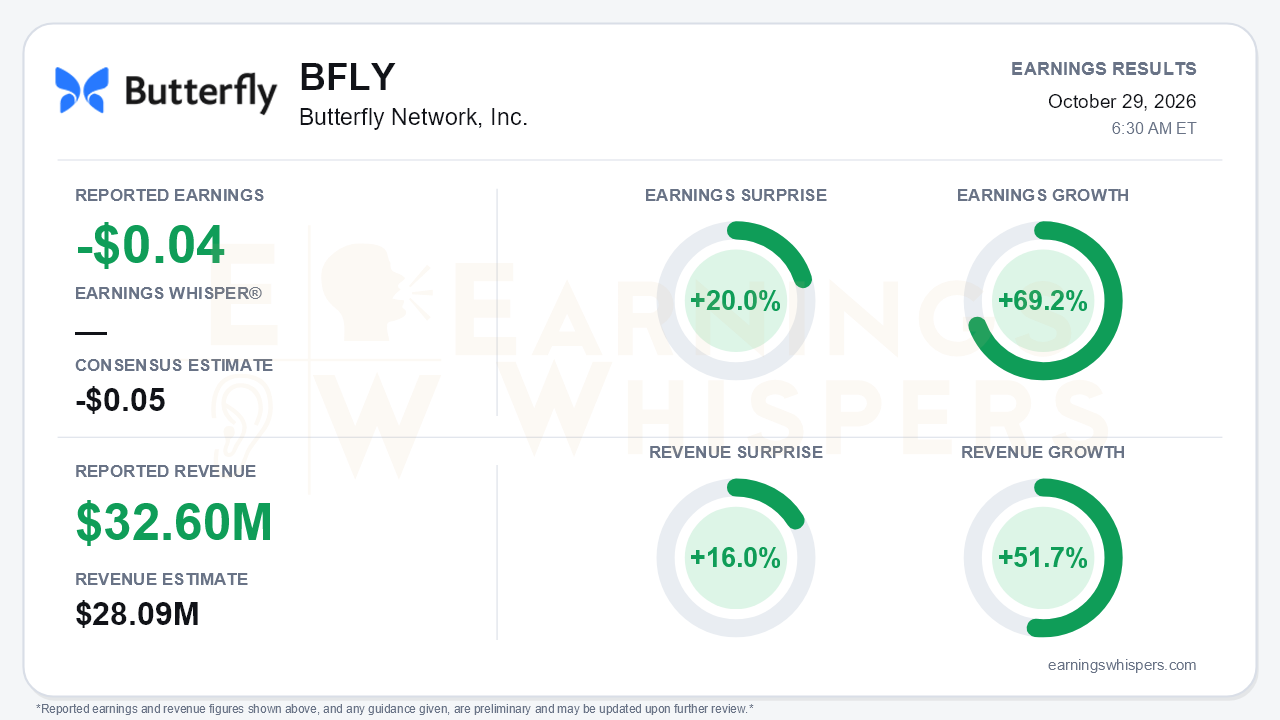
Butterfly Network (NYSE: BFLY) delivered a second straight beat-and-raise quarter. Revenue of $32.6 million rose 51.7% year over year and topped the $28.09 million consensus by 16.0%. On Earnings Whispers' normalized basis, the company lost $0.04 per share, beating the -$0.05 consensus by 20.0% and improving 69.2% from a year ago. The company's own figures were a GAAP loss of $0.05 per share and an adjusted loss of $0.01, against $(0.13) and $(0.04) a year earlier. Management lifted full-year revenue guidance to $123–126 million and cut the expected adjusted EBITDA loss to $12–15 million. The central tension is concentration. Most of the upside came from Butterfly Embedded, a high-margin licensing and co-development business, while the core ultrasound franchise grew only modestly.
The revenue mix shows this clearly. Software and other services revenue jumped to $17.0 million from $6.9 million. Product revenue edged up to just $15.6 million from $14.6 million. U.S. revenue grew 71%, driven primarily by Embedded partnerships including the Midjourney co-development deal. Embedded revenue reached $11.1 million, up from $10.8 million in Q2 and $5.7 million in Q1, and well above the earlier $7–8 million-per-quarter framework.
That mix also explains the record 73% gross margin. The GAAP comparison against a negative 17.5% margin is distorted by last year's $17.4 million inventory write-down. The cleaner read is adjusted gross margin, which has climbed steadily from 67% to 69%, 71% and now 73%. The quality of that progression deserves some scrutiny, however. Management acknowledged that part of the Q3 gain came from a one-time IEEPA tariff refund. Operating expenses rose 19% to $37.4 million, so the improvement in the operating loss came from gross profit, not cost discipline. Adjusted EBITDA loss narrowed to $1.2 million from $8.1 million a year ago.
The call did preserve a credible growth story beyond Embedded:
- **Core growth improved** to 5% from 2% in Q2, and U.S. health system revenue grew 15%.
- **Enterprise deals accelerated.** Butterfly closed five seven-figure and ten six-figure TCV deals, up from six enterprise deals in Q2, and the Compass AI pipeline is now roughly 6x its size at launch.
- **Federal access opened.** FedRAMP authorization arrived as promised, putting larger federal and VA opportunities in play.
- **New revenue streams are close.** Home & Community Care completed its approvals, with scanning in November and first revenue expected in Q4.
- **Embedded is broadening.** Three new brain-computer interface partners signed on, and Mendaera became the first partner to launch a commercial product on Butterfly technology.
Bears still have legitimate ammunition:
- **Device momentum slowed.** Probe unit growth fell to 5% from 23% in Q2, and iQ+ units declined 9%.
- **International weakened again.** Revenue fell 5% to $5.1 million after a 14% drop in Q2. Deals slipped into Q4 again, prompting a strategy overhaul.
- **Q4 guidance implies stalling growth.** The $31–34 million range implies only about 3% growth at the midpoint as Midjourney-related revenue anniversaries, and the implied $3–6 million adjusted EBITDA loss is worse than Q3's.
- **Dilution risk is back on the table.** Management filed a new $150 million shelf and a $150 million at-the-market program, describing them as housekeeping.
- **Cash and working capital need watching.** Cash fell to $122.3 million from $150.5 million at year-end, though quarterly burn dropped to $2.4 million. Current deferred revenue declined to $15.9 million from $26.9 million, which is also worth monitoring.
Investor sentiment improved meaningfully into the report, rising from -0.31 to -0.11, though it remains on the negative side of neutral. The stock's path has been volatile. Shares hit a 52-week high of $10.21 on October 6, then slid to $6.58 by October 23. They closed the pre-report session at $7.81, up 9.7% from the open after the July report and nearly 30% above the 200-day moving average of $6.01, but still 23.5% below that recent peak. The market evidently priced in a strong quarter before taking much of it back. The Earnings Whispers trend readings are mixed, with momentum positive and AVWAP negative, which fits that round trip.
The bottom line is that Butterfly continues to execute well on its operating plan. Margins are at records, profitability is near breakeven on an adjusted basis, and guidance keeps rising. But the quarter's strength depends heavily on lumpy Embedded licensing, and the Q4 outlook shows how quickly growth flattens without new milestones. Core devices and international remain soft, and the new ATM adds dilution risk. Investors will need evidence that enterprise deals, Home & Community Care and next year's P5.1 probe can carry growth once Embedded comparisons get tougher.
Read our earnings preview for Butterfly Network, Inc.: https://www.earningswhispers.com/article/BFLY/21037
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 12 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-05 | |
| Oct-01 | |
| Sep-08 | |
| Sep-01 | |
| Aug-11 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 |
