Axalta Misses Its Own Guide And Cuts The Year As European Refinish And Cost Inflation Overwhelm A Record Mobility Quarter
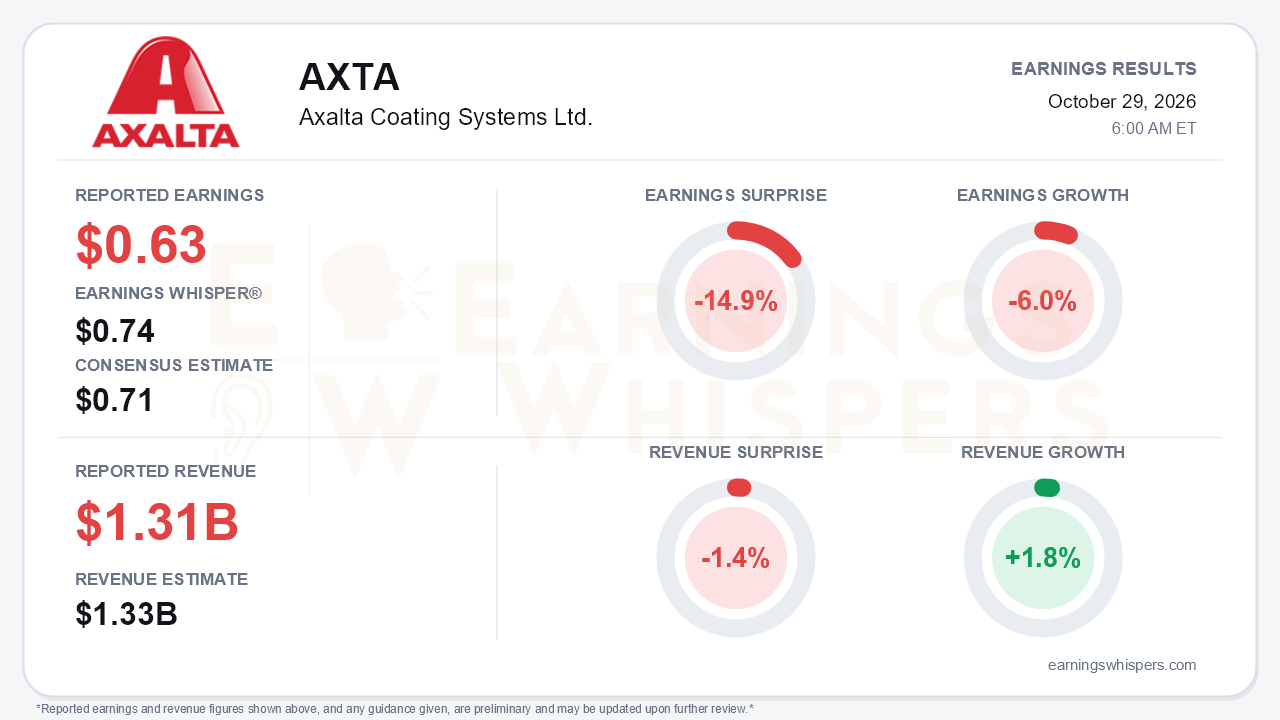
Axalta Coating Systems delivered its first real stumble of 2026. Adjusted EPS of $0.63 fell 14.9% short of the $0.71 consensus and well below the $0.74 Earnings Whisper number. Revenue of $1.311 billion missed the $1.33 billion consensus by 1.4%. Earnings declined 6.0% year over year while revenue grew a modest 1.8%. Measured against management's own targets, the miss was just as clear: Adjusted EBITDA of $282 million came in under the $295-305 million guided after the second quarter, and EPS trailed the roughly $0.70 management had pointed to. The bigger story is the outlook. For the first time this year, Axalta cut full-year guidance for Adjusted EBITDA, EPS and free cash flow, and its new targets sit below Street expectations. That is the central tension: a company with a strengthening balance sheet and a pending transformational merger just reset its near-term earnings power lower.
The deterioration from the second quarter is stark. In Q2, Axalta posted record Adjusted EBITDA of $305 million, a 22.7% margin and $0.72 in EPS. One quarter later, EBITDA fell 4% year over year and the margin slipped to 21.5% from 22.8%. GAAP results were weaker still. Diluted EPS dropped to $0.44 from $0.51, partly because merger and acquisition costs rose to $19 million from $5 million. Those costs are excluded from adjusted figures, but the adjusted decline was operational. Lower Performance Coatings volumes and higher raw material and freight costs drove it, partly offset by lower interest expense and reduced operating expenses.
The damage was concentrated in Performance Coatings. Segment EBITDA fell 11% to $188 million, and the margin compressed to 23.0% from 25.5% a year ago and 25.1% in Q2. Refinish sales declined 2% after growing 6% in the prior quarter. European refinish volumes fell by double digits, and consolidated refinish volumes were down mid-single digits. Industrial grew only about 1%, with Asia flattening and North America still weighed down by higher interest rates. Management's tone shifted noticeably. Earlier calls emphasized records and beating expectations; this one leaned on defending the miss and noting that Europe is still up 5% year to date.
Mobility Coatings moved in the opposite direction and kept the quarter from being worse. Segment sales reached a record $493 million, up 7%, and EBITDA rose 13% to $94 million. The margin improved to 19.0%, up from 18.4% in Q2 and 17.5% in Q1. Commercial Vehicle was the standout, with sales jumping 24% to $119 million after a 7% gain in Q2. Management expects North American Class 8 builds to rise from about 270,000 to roughly 300,000 in 2027. Refinish also has a pipeline story. Axalta has added about 2,600 net body shops through September, ahead of its typical pace of roughly 2,500 per year, and conversion of the 830 MSO shops won in Q2 should accelerate in Q4 and the first half of 2027.
Those tailwinds come with near-term costs. Q4 carries about $8 million of MSO onboarding investment, freight is up more than 15% on diesel prices, and raw-material inflation is exiting the year at high single digits versus low single digits in Q2. European indirect distributors have also paused Q4 restocking. The revised guidance reflects all of this:
- Q4 sales now roughly flat, versus +3% previously;
- full-year EBITDA of $1.10-1.11 billion, versus $1.14-1.17 billion;
- EPS of about $2.45, versus $2.55-2.70;
- free cash flow of about $450 million, down from more than $500 million and including roughly $80 million of merger costs.
The exit rate on costs is the bigger concern for 2027 margins than the Q4 numbers themselves.
The merger provides a separate catalyst. The combined company will be named Axonzo and trade as AXZ after an expected early-2027 close. Clearance has been obtained in about two-thirds of jurisdictions, and remedies have been identified. Management held the $600 million cost-synergy target as a floor despite roughly $500 million of remedy-related sales leaving. The balance sheet also gives Axalta room to absorb a soft patch. Net leverage fell to a record-low 2.1x, gross debt dropped below $3 billion, and year-to-date free cash flow rose 25% to $220 million.
Investor sentiment improved meaningfully heading into the report, rising from -0.22 to roughly neutral at -0.02. Expectations were less pessimistic than three months ago but not euphoric. The stock has gone essentially nowhere, at $34.64 versus a $34.76 open after the July report. That flat result hides a full round trip: shares hit a 52-week high of $38.61 in early August, slid to $31.20 by October 1, and entered earnings 7.3% above the 200-day moving average and mid-range. With sequential growth trends negative, the guidance cut gives bears legitimate ammunition. Merger-driven buyers may be more willing to look through it.
The bottom line is that Axalta's quarter was a genuine miss, not a timing quirk. Performance Coatings margins are compressing under European refinish weakness and accelerating cost inflation, and the full-year outlook was cut. Mobility strength, body-shop wins and a record-low leverage ratio keep the medium-term story credible. Still, the burden now shifts to proving that 2027 cost pressure can be offset before the Axonzo combination closes.
Read our earnings preview for Axalta Coating Systems Ltd.: https://www.earningswhispers.com/article/AXTA/21030
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| 5 hours | |
| Oct-21 | |
| Oct-21 |
Akzo Nobel in Talks to Shed European Refinishing Unit for Axalta Merger Nod
AXTA
The Wall Street Journal
|
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-09 | |
| Oct-05 | |
| Oct-05 | |
| Oct-04 | |
| Sep-16 | |
| Sep-08 | |
| Aug-31 |
