CRH Misses And Cuts Its Outlook, Then Leans On Arcosa, Velocity And A $6 Billion Buyback To Change The Subject
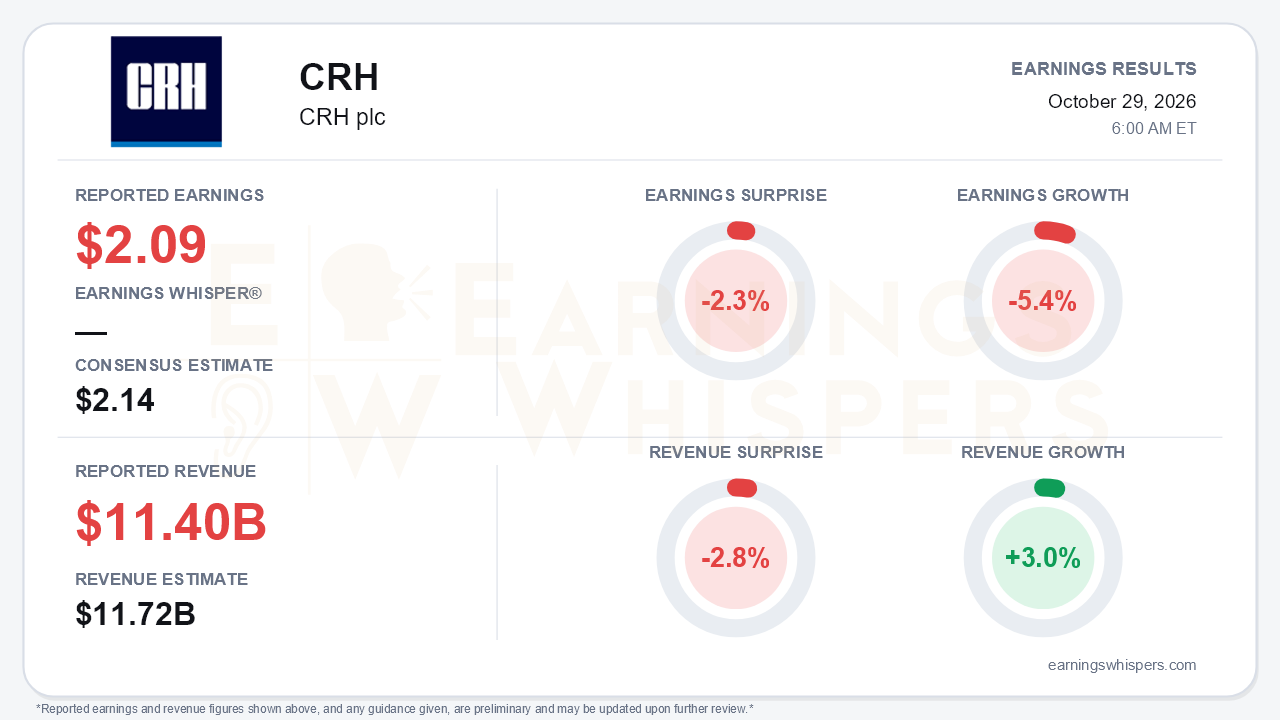
CRH's third quarter was the first clear break in a story built on steady margin expansion. Earnings of $2.09 per share on a pre-impairment basis missed the $2.14 consensus by 2.3% and fell 5.4% from a year ago. Revenue of $11.396 billion rose 3.0% but missed the $11.72 billion consensus by 2.8%. GAAP diluted EPS was weaker still at $1.86, pulled down by a $178 million impairment tied to the Philippines and losses from equity method investments. More consequential than the miss was the guidance. CRH lowered its full-year Adjusted EBITDA range to $7.8-$8.0 billion from $8.1-$8.5 billion, a range it had held since the fourth-quarter 2025 report. Net income guidance fell to $3.1-$3.3 billion from $3.9-$4.1 billion. Management also announced a cluster of strategic offsets: Arcosa closed early, the Velocity cost program, a higher 2030 margin ambition and a $6 billion buyback. The central tension is whether those long-dated levers outweigh a near-term earnings base that is clearly eroding.
The quality of the quarter deserves scrutiny. Adjusted EBITDA was flat at $2.7 billion and the margin slipped 80 basis points to 23.5%. That followed margin gains of 30 basis points in Q2 and 70 basis points in Q1. CRH also revised its Adjusted EBITDA definition this quarter to exclude transformation and integration costs, which kept $49 million of Velocity charges out of the headline metric.
The organic picture is weaker than the consolidated figures suggest:
- **Americas Materials Solutions:** organic EBITDA fell $49 million.
- **Americas Building Solutions:** organic EBITDA fell $80 million.
- **International Solutions:** organic EBITDA added $34 million, not enough to offset the Americas declines.
Acquisitions are carrying the growth. Revenue growth has also decelerated sharply, from 9% in Q1 to 6% in Q2 and 3% now. In addition, the full-year guidance cut absorbs a fourth-quarter contribution from Arcosa, so the underlying reduction to the legacy business is deeper than the headline range implies.
The segment detail shows where the pressure sits:
- **Americas Materials Solutions:** EBITDA growth slowed to 1% from 12% in Q2, and the segment margin fell 130 basis points. Aggregates remain the anchor, with pricing up 5% and volumes up 2%, but cement pricing fell 2% after a 1% decline in Q2.
- **Americas Building Solutions:** EBITDA fell 18%, worse than Q2's 8% decline. Part of that reflects lapping a prior-year land-sale gain, but Outdoor Living revenue dropped 15% on weak residential demand.
- **Inflation:** diesel is up roughly 40% from July lows, and management assumed elevated energy costs persist through Q4.
- **Residential timing:** management pushed its expected residential recovery to mid-2028 at best, from the back end of 2027 previously.
- **Bidding and backlogs:** these are now described as in line with last year rather than up.
- **Margin language:** the promised '13th consecutive year of margin expansion' was no longer reiterated.
The forward catalysts are real, but they are back-end loaded. Arcosa closed in late October rather than in Q1 2027, with $60 million of year-one synergies and $175 million run-rate by year three. Its Engineered Structures business is guided to double-digit growth for three to four years on grid and data center demand. Velocity targets roughly $400 million of run-rate benefits by the end of 2028, about 40% of it in 2027, against roughly $400 million of one-time costs. Those benefits support a 2030 Adjusted EBITDA margin target now pegged at about 24%, the top of the prior range. The 2027 framing is constructive, calling for high-single-digit aggregates pricing, positive price-cost spread and margin expansion. Still, bears have legitimate ammunition:
- Leverage rises after an $8.5 billion deal financed with a term loan and bridge facility.
- Net debt already stood at $15.0 billion before the close.
- Highway reauthorization remains stuck under a continuing resolution.
- Velocity costs will weigh on GAAP earnings through 2027.
- The new Adjusted Diluted EPS guide of $5.37-$5.59 is not directly comparable with the prior diluted EPS range of $5.60-$6.05, which complicates tracking the reset.
The market had already priced in much of the damage. Shares sat at $86.54 the day before the report, down 15.2% from the open after the July release and 17.2% below the 200-day moving average of $104.57. The stock hit a 52-week low of $78.62 on October 14 and has since rebounded about 10%. It remains roughly 15% below its August high of $102.28. Investor sentiment swung from slightly negative (-0.02) to moderately positive (+0.31) heading into the print. That suggests investors were leaning toward a recovery just as management delivered a cut, and the report tests that improved posture. The Earnings Whispers trend signals remain more negative than positive, with price and AVWAP readings still weak.
The bottom line is that CRH missed, decelerated and reduced its outlook for the first time this year, with energy inflation and a deeper housing slump eroding organic profitability. Management responded with an early Arcosa close, a credible-sounding efficiency program and a $6 billion buyback, preserving a plausible 2027-2030 margin story. Investors are now being asked to look past a weaker 2026 base toward benefits that arrive later. With shares well below long-term trend and sentiment having turned hopeful before the report, the setup hinges on whether cost inflation stabilizes and aggregates pricing holds firm into 2027.
Read our earnings preview for CRH plc: https://www.earningswhispers.com/article/CRH/21052
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-15 | |
| Oct-07 | |
| Sep-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
