Climb Global Solutions Beats As Growth Inflects Sharply Higher, But Billings-Driven Mix Dilutes Gross Margin
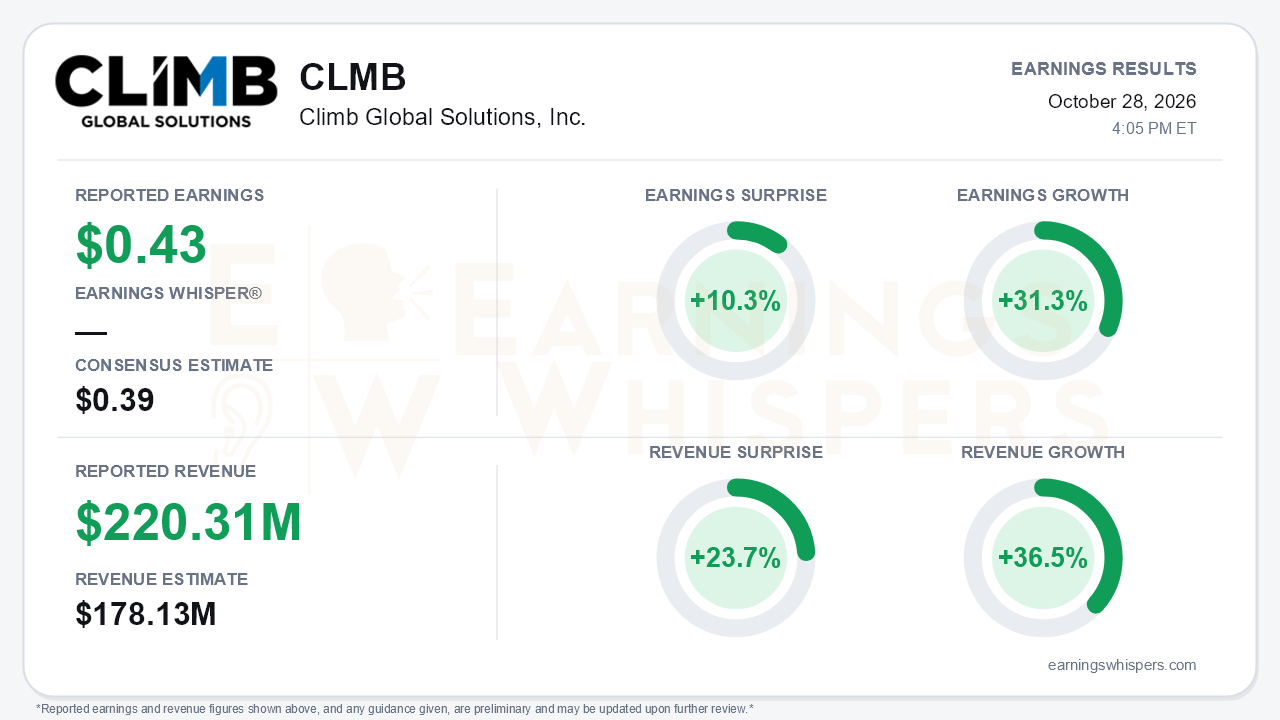
Climb Global Solutions delivered the kind of quarter that changes the conversation. The IT channel distributor earned $0.43 per share in the third quarter, beating the $0.39 consensus by 10.3%. Revenue of $220.31 million topped the $178.13 million estimate by a striking 23.7%. Earnings grew 31.3% year over year and revenue grew 36.5%, a sharp acceleration from the 9% net sales growth reported in the second quarter. Gross billings rose 40% to a record $706.4 million, after gains of 14% in Q1 and 17% in Q2. That is the headline: after a first half weighed down by investment spending and flat profitability, organic volume growth and operating leverage arrived together.
The quality of the beat holds up better than many top-line surprises, with one caveat. Supplied EPS growth and GAAP results tell slightly different stories. GAAP diluted EPS climbed from $0.25 to $0.43, but the year-ago GAAP figure was depressed by an $860,000 contingent-consideration charge and $594,000 in acquisition costs. On an adjusted basis, the prior-year comparison was $0.33, which fits the more modest 31.3% growth figure. A $498,000 foreign-currency gain also helped pretax income this quarter. Even so, operating improvement drove the quarter. Adjusted EBITDA rose 35% to $14.7 million after being flat at $11.3 million in Q2. Effective margin, which measures adjusted EBITDA as a share of gross profit, reached 44.6%, up from 37.5% in Q2 and 29.9% in Q1. SG&A fell to 63.2% of gross profit, versus 68.5% and 76.7% in the prior two quarters. The cost discipline management flagged in Q2 showed up.
The central tension sits between volume and margin. Gross profit grew 28% to $33.0 million, well behind 40% billings growth and 37% sales growth. Each dollar moving through the channel is therefore earning less at the gross line. Climb more than compensated through SG&A leverage this quarter. But a distributor cannot shrink overhead ratios indefinitely, and IT, ERP and marketplace investments continue to flow through SG&A. Management also guided full-year effective margin only to its historical low-40% range. Through nine months, that margin stands at 37.9%, below the 39.6% of a year ago. In other words, Q3 restored the year to normal rather than lifting it to a new structural level.
On the call, management characterized the growth as mostly organic and driven by existing vendors, with no one-time items. Nineteen of the top 20 vendors grew sequentially. Several vendor trends support the story:
- Darktrace is running at roughly a $100 million annualized rate.
- Fortinet is tracking to budget.
- Sophos is reaccelerating after its SecureWorks integration.
October is tracking the Q3 trajectory, and management expects record full-year results. Still, executives called repeating Q3's growth rate "a tough one," and Climb provides no formal numeric guidance. One timing risk deserves attention: vendors are pushing renewals 90 to 120 days early, which could have pulled some activity forward.
The forward catalysts are more expansive than before. The post-quarter NeoVAD acquisition adds a French reseller network with majority-exclusive vendor lines and low double-digit gross margins. Four existing vendors asked to enter France through NeoVAD within a week of the announcement. A new "Challenger Vendor" strategy targets larger vendors moving away from direct sales or from competitors. Management cited one with $200 million of unmanaged business. A proprietary cloud marketplace is slated for announcements in Q1 2027. The M&A pipeline includes four to five active targets, with an aim of two to three deals a year. The risks are integration, since NeoVAD is the second European deal of 2026 after Interworks, and the lack of a disclosed revenue contribution. The balance sheet gives Climb room to pursue these plans: $66.9 million in cash and no debt. Part of the cash build, however, reflected the timing of receivables and payables.
The market setup is more constructive than investor sentiment suggests. Shares have gained 18.3% since the open following the July report and sit about 29% above the 200-day moving average of $25.68. Price and AVWAP trend readings are positive. Sentiment remains negative but improved modestly, moving from -0.33 to -0.25. Investors have rewarded the stock while staying skeptical of the story, which leaves room for opinion to catch up if growth persists. It also means the bar has risen after a quarter management itself says will be hard to repeat.
The bottom line is that Climb produced a genuine inflection: accelerating organic billings, restored operating leverage and a broader set of growth vectors through Europe, larger vendors and a marketplace. Bears have legitimate ammunition in gross-margin dilution, conservative full-year margin framing and management's own caution about sustaining Q3's pace. The next test is whether Climb can sustain double-digit organic growth while absorbing NeoVAD without giving back the margin gains.
Read our earnings preview for Climb Global Solutions, Inc.: https://www.earningswhispers.com/article/CLMB/21049
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Aug-05 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jun-25 | |
| Jun-17 |
