DFIN Clears The Bar With Room To Spare, But Q4 Guidance And Stalling Software Lines Temper A Record Quarter
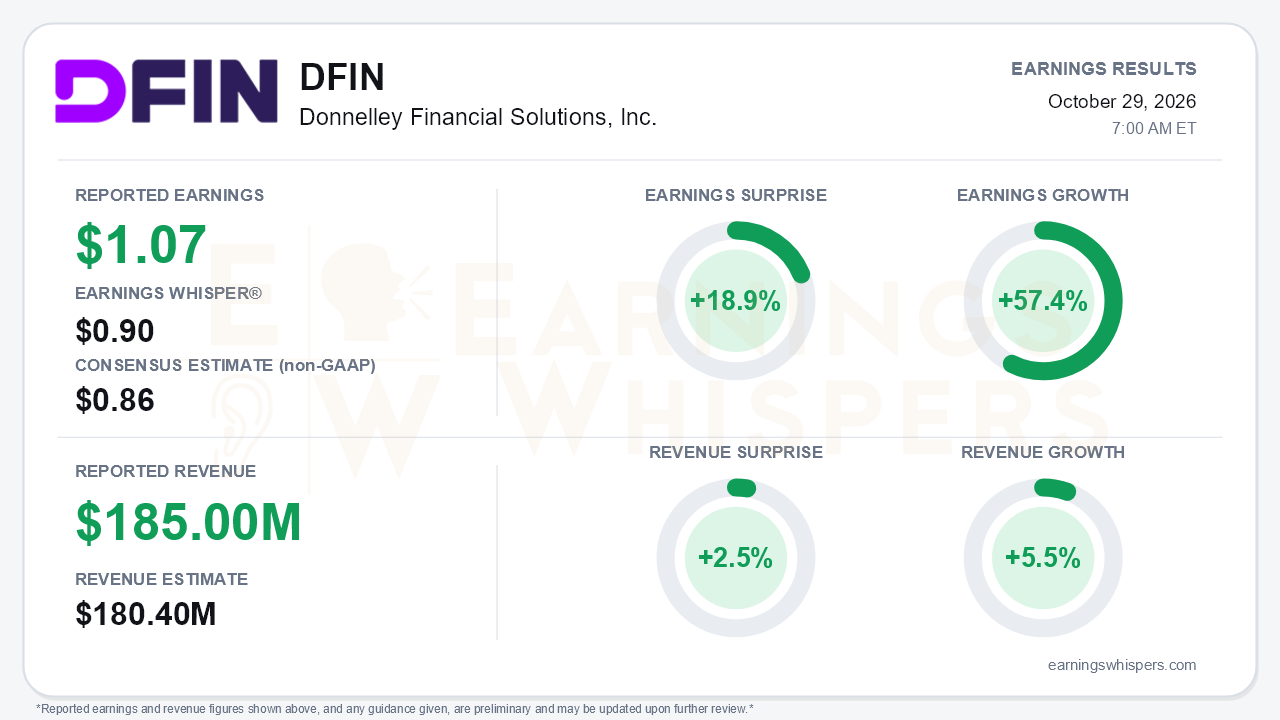
Donnelley Financial Solutions delivered a clean beat in the third quarter. Adjusted earnings of $1.07 per share topped the $0.86 consensus by 18.9% and cleared the $0.90 Earnings Whisper number. Earnings grew 57.4% year over year. Revenue of $185.0 million rose 5.5% and beat the $180.4 million consensus by 2.5%. On a GAAP basis, DFIN earned $0.85 per diluted share, compared with a $1.49 loss a year ago that was driven by an $82.8 million non-cash pension settlement charge. Revenue growth accelerated meaningfully from 2.2% in Q1 and 2.8% in Q2, and sales landed at the top of management's $175 million to $185 million range. The central tension is that the strongest quarter of the year came alongside a fourth-quarter outlook implying roughly 3% growth and flat margins, while two of the three core software franchises lost momentum.
The quality of the beat holds up better on margins than on mix. Adjusted EBITDA rose 9.9% to $54.4 million, and the 29.4% margin beat the 26% to 28% guide by a comfortable distance. Non-GAAP gross margin expanded 210 basis points to 64.8%. Cash generation was the standout. Free cash flow reached $85.8 million, up $26.6 million year over year, which pulled net leverage down to 0.4x from 0.7x in Q2. Beneath that, the drivers deserve scrutiny. Software sales grew 5.0%, slightly slower than the company overall, so the software mix held flat at 51.5% rather than rising. Print and distribution grew 9.4%. Investment Companies software sales declined 1.9%. Capital Markets software segment margin fell roughly 490 basis points to 30.0% as selling expense and incentive compensation rose. Most of the margin expansion came from the Capital Markets compliance segment, where margin jumped to 40.7% from 34.3% on higher transactional volume. That is a more cyclical source of profit than the SaaS story DFIN is selling. A 2.4 million share drop in diluted share count from last year's buybacks also flattered per-share results, although repurchases slowed to just $6.9 million in the quarter.
ActiveDisclosure remains the growth engine. It grew about 24%, its fifth consecutive quarter above 20%, and it now exceeds $100 million in trailing revenue, so all three of DFIN's software offerings are above that threshold. Growth eased from 29% in Q2, however, and IPO S-1 work migrating onto the platform accounted for slightly more than half of the quarter's growth, up from about one-third in Q2. That makes the platform's momentum more dependent on deal flow than headline subscription language implies. The other two franchises weakened:
- **Venue** declined about 1% on EMEA softness, after rising 7% in Q1 and 1% in Q2.
- **ArcSuite** slipped about 2%, with services down roughly 15%.
Management's tone was nonetheless more expansive. It framed the 10-year anniversary as a launch point for a "next chapter" and discussed accelerating the services-to-SaaS shift in 2027.
The forward picture is where bears have legitimate ammunition. Fourth-quarter guidance of $175 million to $180 million and a 26% to 27% adjusted EBITDA margin point to modest growth with no year-over-year margin expansion. The $50 million capital markets transactional assumption is up only about $1 million from last year, compared with roughly $6 million of growth implied in the Q3 guide. Transactional revenue of $45.7 million rose for a fourth straight quarter, but management acknowledged that deal volume moderated from first-half levels, particularly priced IPOs. On the catalyst side, ArcFlex has been repositioned as a module within ActiveDisclosure, with a ramp expected in 2027. The SEC's proposed e-delivery rule cuts both ways: it could shift demand toward software but materially erode print revenue, with the impact expected around 2028.
The market setup is more complicated than the surprise implies. Investor sentiment turned decisively more negative heading into the report, falling from a mildly positive 0.10 to -0.28. Price action told a different story. The stock trades about 12% above its 200-day moving average and has recovered roughly 27% from the $41.69 low set right after the July report. It also set a 52-week high of $56.33 on October 23 before settling about 5.7% below that level. Price, momentum and AVWAP trend readings are positive. In short, the stock entered earnings with strong recent gains even as investors grew more skeptical, a combination that leaves little cushion for a tepid outlook.
The bottom line is that DFIN executed well in Q3, with accelerating revenue, a decisive margin beat, record trailing cash flow and a fortress balance sheet. The in-line Q4 guide, the dependence of ActiveDisclosure growth on IPO activity, and stalls at Venue and ArcSuite suggest the quarter's strength leaned on transactional tailwinds. Investors will need evidence that the software engine can sustain growth when deal markets cool.
Read our earnings preview for Donnelley Financial Solutions, Inc.: https://www.earningswhispers.com/article/DFIN/21058
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Sep-14 | |
| Sep-08 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jun-17 | |
| Jun-10 | |
| May-14 | |
| May-11 |
