Flowserve's Margin-Driven Beat And Record Backlog Collide With A Third Straight Sales Cut
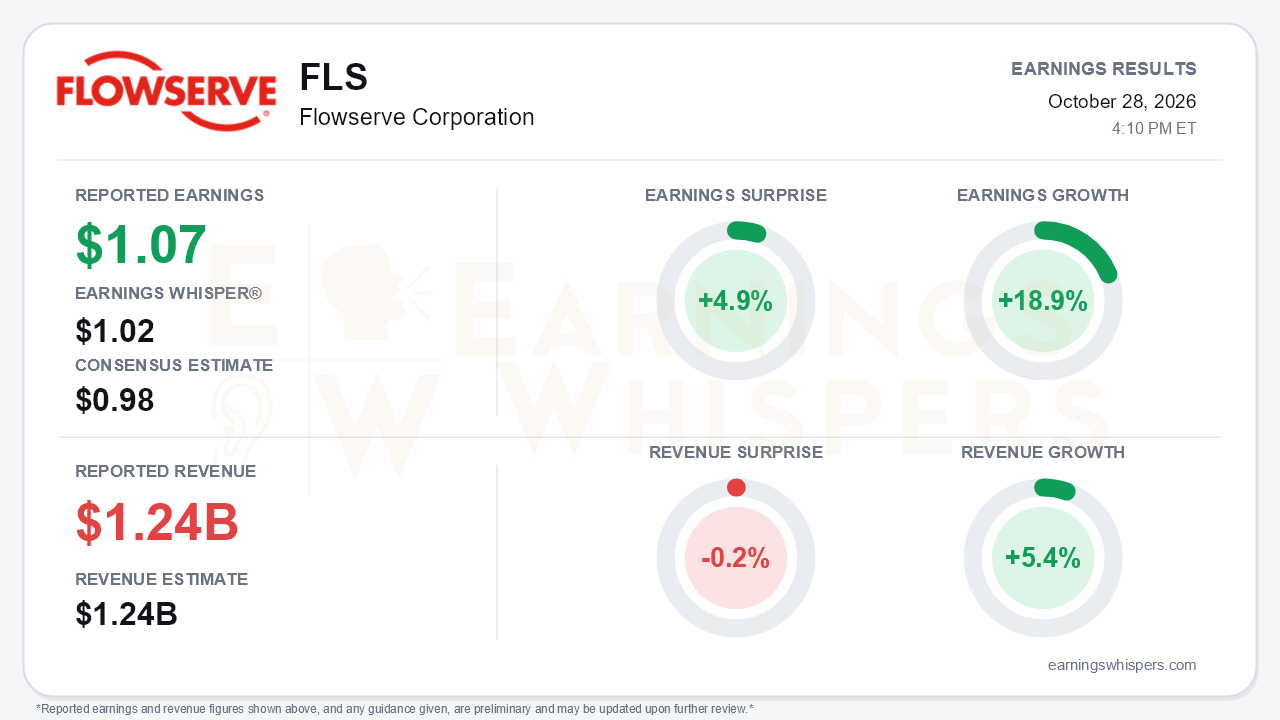
Flowserve delivered the kind of quarter that rewards patience on profitability while testing patience on growth. Adjusted earnings of $1.07 per share beat the $0.98 consensus by 4.9% and cleared the $1.02 Earnings Whisper number. Earnings grew 18.9% year over year, a sharp acceleration from the roughly 4% adjusted growth posted in the second quarter. Revenue of $1.238 billion rose 5.4% but missed consensus by 0.2%. Management raised the low end of full-year adjusted EPS guidance to $4.10-$4.20 and lifted the backlog to a record $3.5 billion, while cutting the organic sales outlook again. That is the central tension. Flowserve is booking more and earning more per dollar of sales, but it keeps struggling to turn orders into revenue on schedule.
The quality of the top line deserves scrutiny. Reported sales growth of 5.4% was entirely acquired. Organic sales fell 1.2%, and acquisitions and divestitures added 670 basis points, largely from Trillium Valves and the consolidation of FAMCO. The earnings beat, by contrast, was operational. Adjusted operating margin reached 16.5%, up 170 basis points year over year and 120 basis points sequentially. The Pumps Division led the way, with adjusted operating margin expanding 220 basis points to 21.8%. Flow Control was weaker. Its adjusted margin was flat at 16.3%, with about 100 basis points of Middle East drag. Organic bookings in that segment rose only 0.8%, so nearly all of its 12.6% bookings growth came from acquisitions. A roughly 2.5% lower diluted share count also helped per-share results. GAAP EPS fell 51.5% to $0.81, but that comparison is distorted by last year's $266 million Chart Industries termination fee. The current quarter's GAAP figure also includes a $16 million gain on the PMV divestiture and a $23 million Italian tax valuation allowance release, both excluded from adjusted results.
The call reinforced that demand is not the problem. Bookings rose 14%, or 8% organically, to $1.38 billion, for a 1.12 book-to-bill. That follows second-quarter bookings growth of 26%. Aftermarket bookings hit a record $728 million, original equipment orders rose 17%, energy bookings climbed 40%, and power grew 23%. Nuclear bookings topped $115 million. The weak spots were narrower but real. General Industries bookings fell 8%. North American refiners running at high utilization are deferring maintenance and turnarounds, which pressures book-and-ship aftermarket revenue. The Middle East cost about $40 million of sales in the quarter, modestly worse than expected, and management said conditions deteriorated further in October in areas with a larger installed base.
The guidance history is where bears have legitimate ammunition. Full-year organic sales guidance has now been cut at every call. It started at +1% to +3%, moved to -1% to +2%, then to roughly -1%, and now sits at -2.5% to -1.5%. Total sales growth has shrunk from 5-7% to 2-3%. Free cash flow conversion was trimmed to about 80% from about 90%. Year-to-date operating cash flow of $230 million is less than half the prior-year level, reflecting delayed Middle East shipments and slower collections. Long-term debt has also risen to $2.05 billion after more than $500 million of acquisition spending. On the positive side, management now expects full-year adjusted margin expansion of about 150 basis points, up from about 100. The buyback authorization rose to $500 million, and the Middle East rebuild opportunity is now seen above the earlier ~$50 million estimate. Management also pointed to data center liquid cooling, Trillium synergies and a potential 2027 catch-up in deferred refining maintenance as further upside. The call guided to mid-single-digit organic growth in the fourth quarter. That is a demanding target given that the release itself flags Middle East pressure on fourth-quarter sales.
Investors were already skeptical heading into the print. Earnings Whispers sentiment stayed negative and weakened modestly, slipping from -0.21 to -0.29. Shares sat at $71.81, about 2.2% below the open following the July report and 5.9% under the 200-day moving average of $76.31. Price and AVWAP trend readings both remain negative. The market has not been paying for margin progress while the revenue line keeps getting marked down.
The bottom line is that Flowserve's operating model is clearly improving, and a record backlog gives the long-term growth story credibility. Even so, this report repeated a pattern of higher EPS on lower sales expectations and weaker cash conversion. Until backlog converts and the Middle East stabilizes, the beat is more likely to be judged by the fourth-quarter revenue ramp than by the margin line.
Read our earnings preview for Flowserve Corporation: https://www.earningswhispers.com/article/FLS/20935
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-13 | |
| Sep-25 | |
| Sep-14 | |
| Aug-27 | |
| Aug-24 | |
| Aug-05 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jun-30 |
