Fiverr Beats And Raises On Services And Cost Cuts, But A Faster Marketplace Slide And A 2027 Margin Warning Dominate The Story
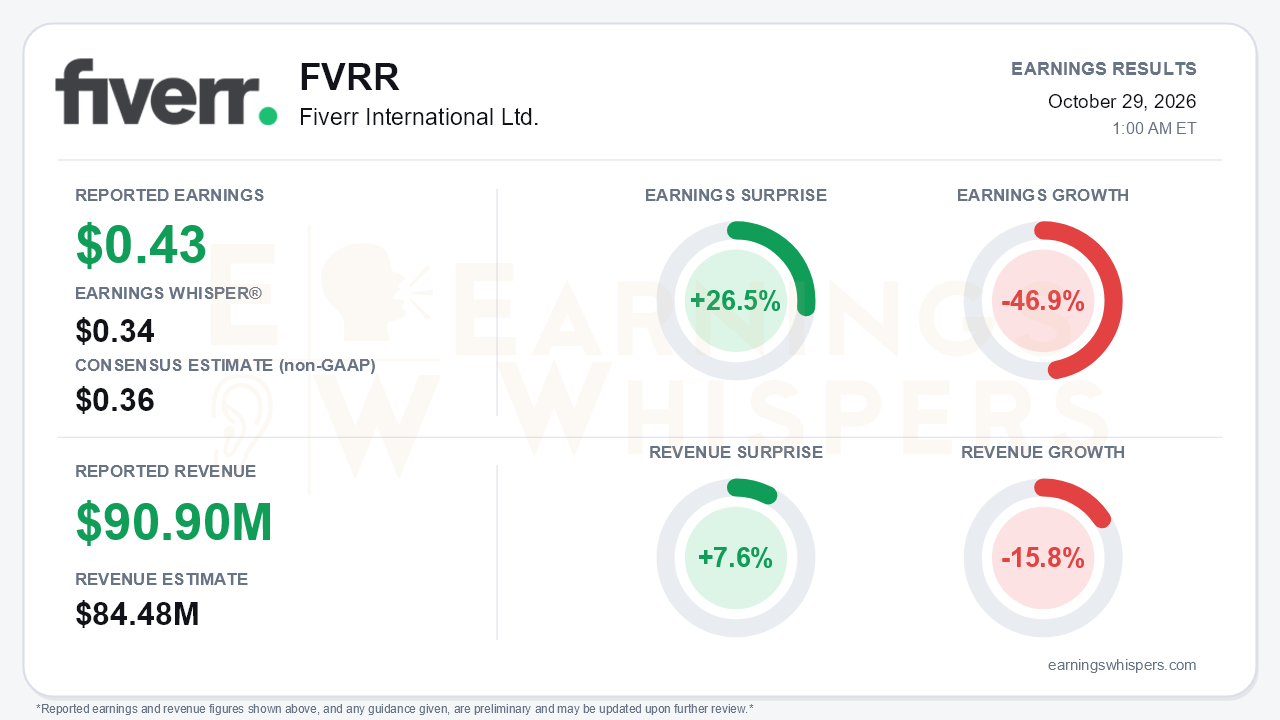
Fiverr International delivered a clear headline beat for the third quarter. Non-GAAP earnings of $0.43 per share topped the $0.36 consensus by 26.5% and cleared the $0.34 Earnings Whisper number. Revenue of $90.9 million beat the $84.48 million consensus by 7.6%. Management also raised full-year 2026 guidance. Yet earnings fell 46.9% year over year and revenue fell 15.8%, and the revenue decline widened for a third straight quarter, from -1.6% in Q1 to -10% in Q2 to -15.8% now. That is the central tension. The beat came from the parts of the business Fiverr can control, while the core marketplace is deteriorating faster than it was three months ago.
The quality of the beat deserves scrutiny. Services revenue rose 3.4% to $35.5 million, a sharp reversal from the double-digit decline management had warned of on the Q2 call. Much of that lift came from an AutoDS e-commerce partnership campaign that launched in late August and is expected to run through Q4. Cost discipline did the rest. GAAP operating expenses fell to $74.5 million from $88.0 million a year ago, with R&D down 28% and G&A down 23%. Share-based compensation dropped to $6.7 million from $11.9 million. Even so, the company posted a small GAAP operating loss of $0.7 million. GAAP EPS fell to $0.03 from $0.15, helped little by financial income that shrank to $3.0 million from $6.8 million. The underlying profitability trend is plainly down:
- Adjusted EBITDA margin slid to 16.0% from 17.9% in Q2, 21.4% in Q1 and 24.7% in Q4 2025.
- Non-GAAP diluted EPS has stepped down each quarter, from $0.86 to $0.62 to $0.50 to $0.43.
- Free cash flow fell to $9.4 million from $13.6 million in Q2 and $29.1 million a year ago.
Beneath the headline, the marketplace story got worse. Marketplace revenue fell 24.7% to $55.4 million, a much steeper drop than the 15.5% decline in Q2. Annual active buyers fell to 2.4 million, down from 2.7 million in Q2, 2.9 million in Q1 and 3.3 million a year earlier. Fiverr is still extracting more from the buyers it keeps. Spend per buyer rose to $373, up 12.9%, and the take rate edged up to 28.2%. But spend-per-buyer growth slowed from 15.6% in Q2, and management expects it to keep slowing. Even the upmarket push showed strain. The $1,000-plus share of completed-project value ticked up to 16%, but $1,000-plus growth in Programming & Tech and Graphics & Design slowed to the mid-teens from 34% and 25% in Q2. Management blamed SEO-driven top-of-funnel disruption.
The forward commentary is where the investment setup changed most. Full-year revenue guidance rose to $374–$380 million from $356–$372 million, and adjusted EBITDA guidance rose to $61–$65 million from $52–$62 million. That still sits below the original $380–$420 million revenue range. Implied Q4 guidance of $80–$86 million in revenue (down 20% to 25%) and $6–$10 million in EBITDA is a sharp step down from Q3. More consequentially, management now expects a steeper marketplace traffic decline through 2027 as discovery shifts from search to AI. It also flagged downward pressure on 2027 adjusted EBITDA margin despite lower expected operating expenses. CEO Micha Kaufman described SEO as nearly dead and AI agents as brand-agnostic. That candor has value, but it also concedes risk to Fiverr's direct customer relationships.
The call did preserve a credible, if early, AI-channel narrative:
- Fiverr is now live inside Claude and ChatGPT via MCP and public APIs, with Gemini targeted next.
- AI-sourced GMV from first-time buyers rose roughly 64% sequentially.
- The new Mira AI headhunter is producing five times the median order value and about 25% lower cancellations on first-time matches.
These are promising signals off a small base, and none yet offsets the traffic erosion. Other items add uncertainty. The Chief Business Officer departed, leaving the CEO and CFO running operations in the interim. M&A is off the table, and buybacks went undiscussed despite $316.2 million in cash and investments.
The market entered the report treating Fiverr skeptically. Shares closed at $8.08, down 13.9% since the open after the July report and 25.1% below the $10.79 200-day moving average. The stock sat less than 1% above a fresh 52-week low of $8.01 set the day before earnings. Momentum and AVWAP trend readings remain negative. Investor sentiment was essentially unchanged at -0.22, barely less negative than after the prior report. A beat-and-raise against that backdrop can spark relief, but the 2027 warning gives bears legitimate ammunition.
The bottom line is that Fiverr's third quarter was a tactical win built on a single services campaign and aggressive cost cuts, while the marketplace that defines the franchise is shrinking faster. The raised 2026 outlook is welcome, but the steeper projected traffic decline and 2027 margin pressure are now the more important numbers to track.
Read our earnings preview for Fiverr International Ltd.: https://www.earningswhispers.com/article/FVRR/21074
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 15 hours | |
| 15 hours | |
| Oct-23 | |
| Oct-21 | |
| Oct-09 | |
| Sep-23 | |
| Sep-21 | |
| Aug-13 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-08 |
