Silicon Motion Beats And Raises, Lifts Margin Ambitions, But Consumer Softness And A Cash-Hungry Ramp Complicate The Setup
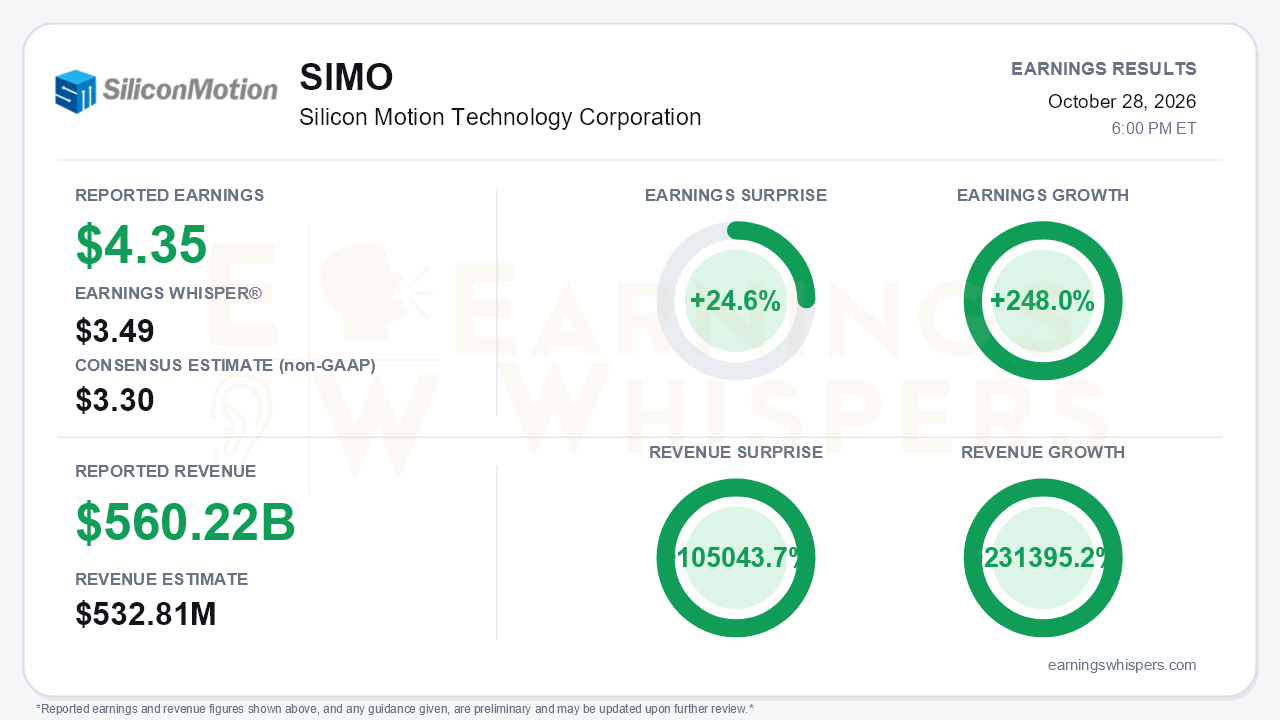
Silicon Motion delivered a decisive beat-and-raise in the third quarter. Non-GAAP earnings of $4.35 per ADS cleared the $3.30 consensus by 24.6% and topped the $3.49 Earnings Whisper number. Earnings grew 248.0% year over year. Revenue of $560.2 million exceeded the $532.81 million consensus and management's own $519 million to $541 million guide. Sales rose 24% sequentially and 131% from a year ago, the fourth straight record quarter. The bigger development is the earnings power behind it. Non-GAAP gross margin reached 53.7% against a 50% to 51% guide. Operating margin hit 32.1%, well above the 27.5% to 28.5% target and up from 23.1% in the second quarter. Management also offered a first look at 2027: revenue growth of at least 40% with gross margin in the low-to-mid 50s, which effectively retires the 48% to 50% long-term target it held just one quarter ago.
The quality of the beat deserves some scrutiny, though not because the operating results were soft. GAAP EPS fell to $1.91 from $3.99 in the second quarter. The main cause was a $78.0 million investment loss that reversed a $74.7 million gain the prior quarter, so this is noise rather than an operating problem. Two other issues are more substantive. First, stock-based compensation jumped to $17.3 million from $3.4 million. The fourth-quarter outlook excludes $34.6 million to $35.6 million of stock compensation and dispute costs, which leaves GAAP operating margin guidance of 29.9% to 31.4% against 36% to 37% on a non-GAAP basis. Second, the growth is consuming cash. Operating cash flow was negative $256 million as inventory climbed to $870.9 million and receivables rose to $443.5 million. The $1.15 billion zero-coupon convertible, upsized from $800 million, lifted cash to $953.6 million and repaid the bank loan. That funds the ramp but adds potential dilution.
The call showed a company changing its revenue mix quickly. The solutions business, made up of Ferri automotive/edge AI and enterprise boot drives, grew 75% to 80% sequentially. It now accounts for more than 40% of revenue, up from about 30% in the second quarter and 4% a year ago, and management expects a roughly even split with controllers in 2027. Automotive is carrying better-than-expected margins, and backlog reportedly rose significantly within three months. SSD controllers rose 20% to 25% sequentially as MonTitan enterprise controllers began to scale, with all seven customers on track to ramp. Management's thesis is that NAND makers are prioritizing high-capacity enterprise SSDs and leaving segments such as automotive, boot drives and mobile to merchant suppliers. In management's account, enterprise and Ferri customers are favoring supply assurance over price.
The consumer side tells a different story, and bears have legitimate ammunition. eMMC/UFS sales fell 10% to 15% sequentially and are now expected to be flat near term. One quarter earlier, management had called for strong growth in 2026. Smartphone OEMs are cutting specifications as memory costs rise, and client SSD controllers are guided flat to slightly down in the fourth quarter as PC units decline. Growth is also moderating. Fourth-quarter guidance of $588 million to $616 million implies 5% to 10% sequential growth and 111% to 121% year-over-year growth, below the 15% to 20% sequential pace guided for the second and third quarters. As solutions grow, so does exposure to NAND pricing. Management cited inventory near $800 million, while the balance sheet already shows $871 million. The Singapore arbitration also remains unresolved.
On the catalyst side, the near-CPU DRAM boot drive opportunity carries an estimated $10 billion-plus addressable market by 2030 and is expected to ramp in the second half of 2027. Management also reported new Tier 1 networking boot drive wins, a tape-out of the 4nm PCIe Gen6 MonTitan with sampling in the first quarter of 2027, and secured 2027 capacity at TSMC and in test, assembly and substrates. The annual dividend rises 15% to $2.30 per ADS.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive heading into the report but weakened considerably, falling from 0.53 to 0.17. Shares entered earnings at $219.61, down 15.5% from the opening price after the July report and only about 3% above the 200-day moving average of $213.17. Price trend readings were neutral and AVWAP negative, consistent with a stock that had been losing ground despite record results. Investors appeared to be pricing in decelerating growth, consumer weakness and convertible dilution rather than margin upside.
The bottom line is that Silicon Motion's mix shift toward automotive, boot drive and enterprise storage is producing margins and visibility that justify a higher earnings baseline, and the 2027 framework extends that story. The tension lies in slowing sequential growth, weakening consumer controller lines, a widening GAAP/non-GAAP gap and a working-capital build funded by convertible debt. Those concerns had already pulled sentiment and the share price lower before the report.
Read our earnings preview for Silicon Motion Technology Corporation: https://www.earningswhispers.com/article/SIMO/20988
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-16 | |
| Oct-08 | |
| Sep-09 | |
| Sep-08 | |
| Sep-03 | |
| Aug-13 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 |
