Insperity's Margin Recovery Reaches Its Inflection, But A Whisper Miss, Shrinking Worksite Count And Trimmed Guidance Ceiling Temper The Win
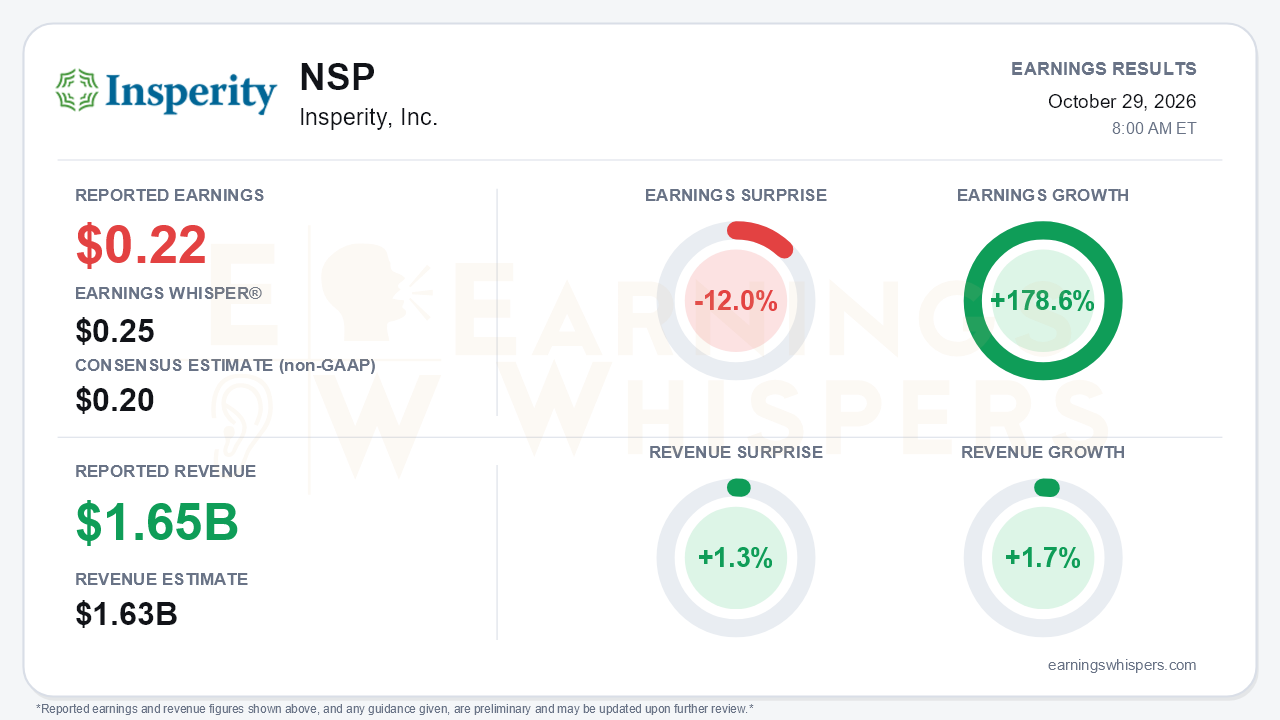
Insperity's third quarter delivered the margin turn the company has been promising, but not quite the quarter investors were looking for. Adjusted EPS of $0.22 beat the $0.20 consensus but fell short of the $0.25 Earnings Whisper number, a 12.0% miss against the expectation that mattered most. Revenue of $1.651 billion topped the $1.63 billion consensus by 1.3%. Earnings swung from an adjusted loss of $0.20 a year ago to a profit, which Earnings Whispers calculates as 178.6% growth. Revenue rose just 1.7%. That is the central tension: profitability is clearly rebuilding, but the top line is barely moving and the unit base is still shrinking.
The quality of the improvement rests almost entirely on price and cost, not volume. Average paid worksite employees fell 2% to 307,265. Revenue per WSEE rose 4% on higher pricing, and gross profit per WSEE jumped 8% to $225, the first year-over-year gain since the 2025 declines began. That is a sharp reversal from -1% in Q2 and -2% in Q1. Total gross profit grew 6% to $207 million after falling 3% in each of the prior two quarters. Benefits cost per covered employee rose 3.7%, down from 5.2% in Q2 and roughly 9% through 2025. Operating expenses fell 5% to $209 million on reduced corporate staffing, though advertising rose. GAAP results remain thin. The company posted a $1 million net loss, or $(0.02) per diluted share, and Q4 GAAP EPS guidance spans $(0.14) to $0.21.
The call reinforced the margin narrative but did little to resolve the growth question. Paid WSEEs declined 1.8% year over year, steeper than the 1.1% drop in Q2 and 1.0% in Q1. Q4 is guided down 1.4% to 2.0% with flat sequential growth. Management acknowledged that pricing discipline and client selection continue to weigh on new sales and retention, while noting that departing clients have been far less profitable than those retained. Leading indicators offered some encouragement:
- Business profiles rose every month in Q3 even with fewer sales reps, and lead flow improved.
- Mid-market prospects are signing HR 360 with plans to upgrade to HR Scale.
- The new HR 360 AI Agent gave management a more confident growth message, as CEO Paul Sarvadi argued AI could strengthen demand among small and midsize businesses.
Guidance was the weakest part of the report. Full-year adjusted EBITDA was narrowed to $194-$214 million from $185-$225 million, leaving the midpoint essentially flat at about $204 million. Adjusted EPS moved to $1.93-$2.28 from $1.88-$2.43, a modestly lower midpoint. Raising the low end while cutting the high end signals more confidence that the recovery will hold, but less room for upside. Bears also have legitimate ammunition on cost. Favorable prior-year workers' comp reserve releases shrank again amid rising claim severity. Management also said the 2026 benefits tailwinds from the UnitedHealthcare contract and plan design turn neutral in 2027, while healthcare trend stays elevated. HR Scale disclosure grew vaguer, shifting to "several thousand in implementation" from the roughly 8,000 sold WSEEs cited in Q2. Management also flagged a wide range of year-end sales and retention outcomes, plus election-related uncertainty, which together will set the January 2027 starting point.
The balance sheet deserves attention too. Adjusted cash improved to $119 million from $95 million at the end of Q2, and buybacks resumed at $6 million. However, credit facility borrowings stand at $420 million, up from $369 million in long-term debt at year-end. Year-to-date dividends of $69 million exceed GAAP net income of $36 million, and stockholders' equity is only $44 million.
Investor sentiment improved meaningfully heading into the report, moving from -0.15 to +0.03. That is a shift from mild skepticism to roughly neutral rather than outright enthusiasm. Price action tells a similar story. Shares opened at $55.57 after the July report, essentially the inter-earnings high, then slid to a $45.66 low on October 5 before rebounding about 13% to $51.65. The stock still sits 7.1% below that post-report open but remains roughly 31% above its 200-day moving average. Earnings Whispers momentum and AVWAP trend readings are positive, consistent with the recovery off the October low.
The bottom line is that Insperity proved the margin recovery is real: gross profit per worksite employee turned decisively positive and cost discipline is holding. But the whisper miss, an accelerating decline in worksite employees, and a guidance range trimmed at the top show that the story still depends on price rather than growth. With 2027 benefits tailwinds fading and comp costs hardening, the next leg requires unit growth to re-emerge. The leading indicators hint at that, but this quarter's results do not yet show it.
Read our earnings preview for Insperity, Inc.: https://www.earningswhispers.com/article/NSP/21110
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-13 | |
| Oct-06 | |
| Sep-23 | |
| Aug-20 | |
| Jul-30 | |
| Jul-29 | |
| Jul-28 | |
| Jul-02 | |
| Jun-11 |
