Ligand's Royalty Engine Drives A Clean EPS Beat And Second Guidance Raise, But Held Revenue Outlook And A Heavier Balance Sheet Temper The Story
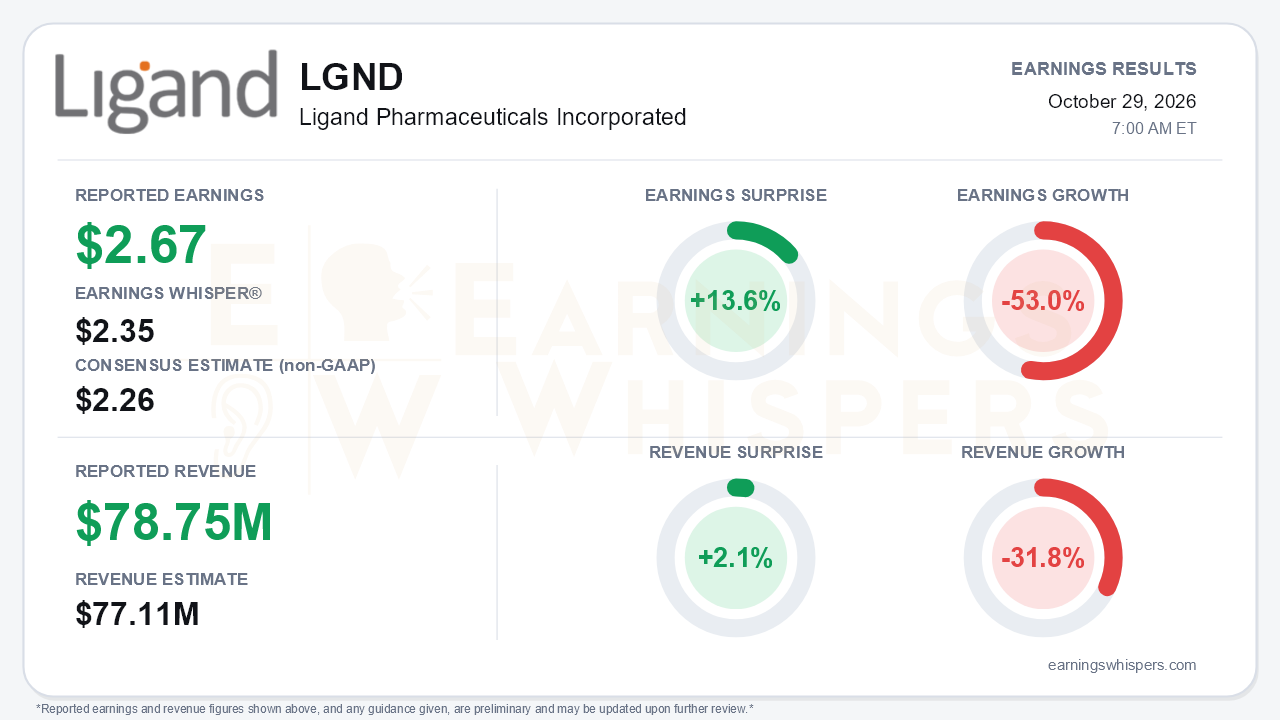
Ligand Pharmaceuticals delivered adjusted earnings of $2.67 per share for the third quarter, beating the $2.26 consensus by 13.6% and clearing the $2.35 Earnings Whisper number. Revenue of $78.75 million topped the $77.11 million consensus by 2.1%. The year-over-year comparisons look poor at first glance. Earnings fell 53.0% and revenue declined 31.8%, but both figures are distorted by last year's $53.1 million of Pelthos divestiture income. The underlying story is much stronger. Royalty revenue rose 51% to $70.3 million, total revenues and income grew 26% excluding Pelthos, and management raised full-year adjusted EPS guidance for the second time this year. The central tension is that the earnings outlook is rising while the revenue outlook is not.
The quality of the beat holds up well on the royalty line, though GAAP results deserve scrutiny. XOMA contributed $12.3 million in roughly 11 weeks after the deal closed on July 14. Even so, the legacy portfolio grew 25% to $58.1 million, so the quarter did not depend on acquired assets alone. Filspari was the standout, with royalties up 85% to $16.8 million following its April FSGS approval, making it Ligand's largest asset ahead of Kyprolis. Captisol sales were weaker, falling to $7.9 million from $10.7 million on order timing. Below the line, results were messy. G&A expense jumped to $72.6 million from $28.4 million, driven by $23.9 million of transaction and integration costs and $29.0 million of share-based compensation, which includes $10.8 million tied to cash-settling XOMA equity awards. A $35.7 million mark-to-market loss on the Pelthos stake pushed Ligand to a GAAP net loss of $1.43 per share, compared with GAAP income of $5.68 a year ago. A $6.6 million credit-loss provision on financial royalty assets is also excluded from adjusted results and is worth monitoring.
The call preserved a credible growth story, but the trajectory is not uniformly accelerating. Royalty growth of 51% is slightly slower than the 56% posted in the first quarter, even with an acquisition added to the base. Management also acknowledged that some royalty figures, including Filspari, are based on consensus estimates because partners report on a different schedule, which leaves room for later true-ups. The bigger issue is guidance. Royalty revenue guidance of $225 million to $250 million and total revenue guidance of $270 million to $310 million were only reaffirmed, as they have been since the first quarter. That implies an unusually wide fourth-quarter royalty range of roughly $64 million to $89 million. The CFO attributed the caution to uncertainty around milestone and Captisol timing. Adjusted EPS guidance, by contrast, is now $9.50 to $9.75, up from $9.00 to $9.50 and from $8.00 to $9.00 at the start of the year. Management also said XOMA cost synergies are running ahead of the roughly $5 million target.
The catalyst calendar is dense. Palvella's Qtorin rapamycin NDA received priority review with a February 28, 2027 PDUFA date. Rezolute expects ersodetug tumor HI data in mid-December, and management reiterated up to seven pivotal readouts through 2027. Capital deployment remains active, with the $23 million Ryjunea royalty and an AvenCell financing of up to $47 million. Management reported 115 confidentiality agreements signed, compared with about 69 last year. Bears still have legitimate ammunition:
- Cash and investments fell to $447.4 million from $733.5 million at year-end.
- Convertible notes rose to $1.13 billion.
- The volixibat PSC filing has slipped to the first half of 2027.
- Ryjunea faces U.S. regulatory skepticism and competition from compounded atropine.
- Much of the 2027 slate carries binary clinical risk.
Investor sentiment remains negative but improved into the report, moving from -0.23 to -0.14. That is a modest shift, not a reversal. The stock has been treated far better than sentiment suggests. Shares closed at $318.78 before the release, up 4.1% since the open following the August report. That price is 26.9% above the 200-day moving average and just 0.4% below the inter-earnings high of $319.90, set the day before earnings. The stock has also recovered 17.7% from its September 15 low. The Earnings Whispers trend signals are mostly positive, with sequential growth and momentum improving, while the price trend is neutral. With the stock entering the print at the top of its range, the market setup is more complicated than the surprise implies, because much of the good news may already be reflected in the price.
The bottom line is that Ligand's royalty engine is performing, with organic growth of 25%, a breakout quarter for Filspari, and a second EPS guidance raise all supporting the aggregation thesis. Unchanged revenue guidance, a leveraged post-XOMA balance sheet, and estimate-based royalty accounting leave the December 8 investor day, and its update to the prior 23% royalty-receipts growth target, as the next real test.
Read our earnings preview for Ligand Pharmaceuticals Incorporated: https://www.earningswhispers.com/article/LGND/21094
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 11 hours | |
| 12 hours | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Sep-25 | |
| Sep-24 | |
| Sep-22 | |
| Sep-22 | |
| Aug-26 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 |
