Laureate Education Beats On Strong Mexico Intake, But FX And Calendar Timing Inflate The Quarter As Full-Year Guidance Stays Flat
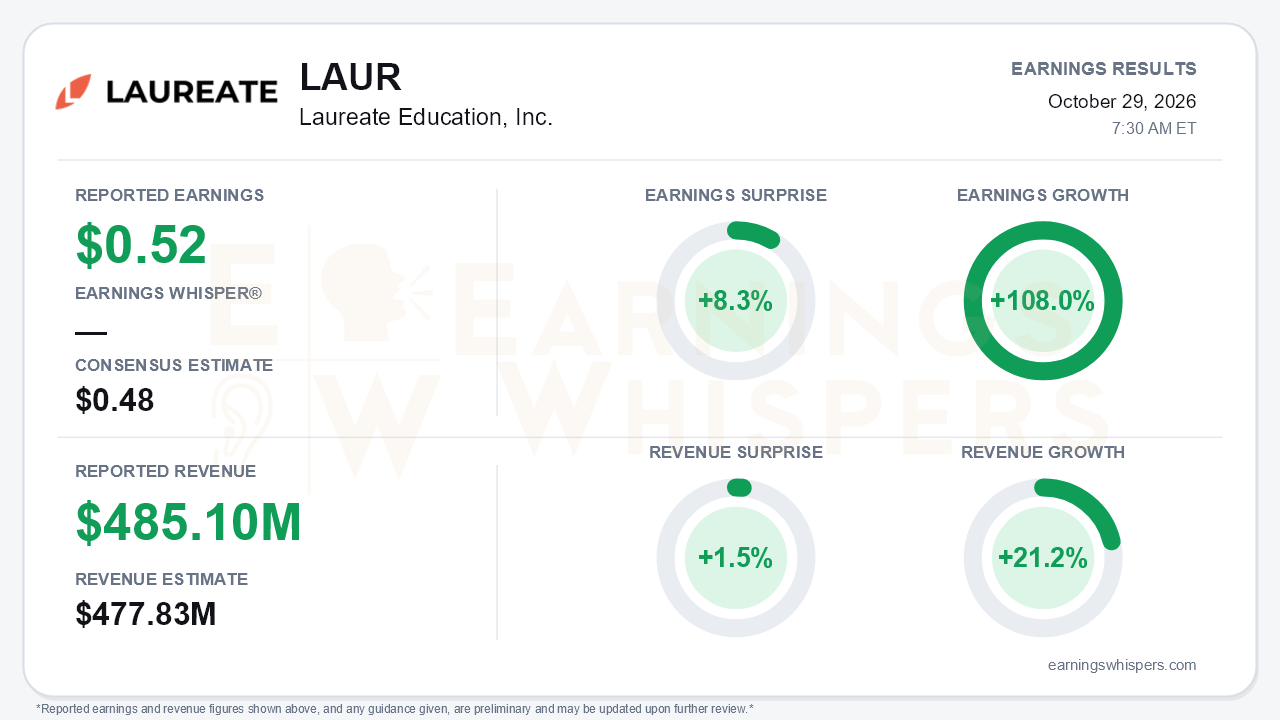
Laureate Education (NASDAQ: LAUR) delivered a clean headline beat for the third quarter. Adjusted earnings came in at $0.52 per share against a $0.48 consensus, an 8.3% surprise and 108.0% growth year over year. Revenue of $485.1 million topped the $477.83 million estimate by 1.5% and grew 21.2%. The quality of the beat deserves scrutiny, though. Much of the upside came from currency and calendar effects that management expects to unwind, and full-year guidance was reaffirmed rather than raised. That is the central tension: the underlying enrollment engine is improving, while the reported numbers overstate how much.
Start with what flattered the print. Reported revenue rose 21%, but constant-currency growth was 14%. That 14% figure includes roughly $29 million of favorable intra-year academic calendar timing from 2026 semester start dates. Adjusted EBITDA jumped 55% to $146.8 million, but about $26 million of that came from the same timing benefit. Laureate says both effects will reverse in the fourth quarter. Stripping out currency and timing, Q3 revenue grew about 6% and EBITDA about 14%. Those are respectable, but they are not the numbers in the headline.
The comparison with the company's own guidance is just as revealing. The revenue beat against the $471-476 million guide was entirely currency-driven. The EBITDA beat against the $134-137 million range was roughly half FX and half expense timing, with about $5 million of costs pushed into Q4. GAAP diluted EPS of $0.73 was further inflated by a $25.4 million discrete tax benefit from resolving a legacy tax contingency, which adjusted results correctly exclude. Buybacks also helped the per-share figures. Diluted share count fell to 138.0 million from 148.2 million a year earlier, giving a meaningful assist to per-share growth.
Beneath those distortions, the operating story genuinely improved. Mexico's primary intake new enrollments rose 8%. That compares with 4% in the first-quarter secondary intake and 2% in last year's primary intake. The new Puebla campus contributed about three points and is running ahead of plan. Peru's secondary intake grew 9%, supported by fully online offerings aimed at working adults. Mexico's timing-adjusted, constant-currency EBITDA rose 12% in Q3, lifting year-to-date growth to +3% from -2% at midyear. That supports management's case for a second-half margin weighting. Management reiterated its 30-50 basis points of annual margin expansion and described the Mexican macro backdrop as improving, after calling it soft earlier in the year. Year-to-date new enrollment growth still eased slightly, to 9% from 10% at June.
The forward picture is where bears have legitimate ammunition. After Q2's guidance raise, the outlook was left unchanged:
- revenue of $1.92-1.93 billion;
- adjusted EBITDA of $593-599 million;
- adjusted EPS of $2.04-2.10.
The implied Q4 guide of $546-556 million in revenue and $198-204 million in EBITDA sits below prior implied levels. That reflects post-quarter weakness in the peso and sol, plus the shifted expenses. Management also acknowledged several pressures:
- higher attrition and price-mix dilution from the growing fully online mix, expected to persist into 2027;
- intensifying online competition in Peru, with reports of price cutting;
- a potential El Niño disruption from November through February;
- higher second-half capex for land acquisition.
On the other side, capital returns remain a real support. Laureate added another $150 million to its repurchase authorization, bringing pro forma capacity to about $225 million. That follows $256 million of buybacks through September. Net debt shrank to $14.3 million from $61 million at Q2. Management also plans to detail an accelerated campus pipeline on the Q4 call, with more openings slated for 2028 on land already secured.
The market had not been rewarding the momentum before the report. Shares closed at $36.36 the day before earnings, 7.6% below the open following the July report. They sat 11.2% under the $40.93 52-week high set on that post-report day, only 3.1% above the September low, and just 2.2% above the 200-day moving average. Investor sentiment improved modestly, rising to 0.25 from 0.19, so expectations leaned positive without being stretched. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Laureate's quarter showed better enrollment fundamentals, especially in Mexico, than the stock's recent slide implies. However, the headline beat was largely manufactured by currency, calendar timing, and expense shifts. With guidance merely held, online-driven mix pressure building, and Q4 set to absorb the timing reversal, the investment case rests on intake strength, margin execution, and aggressive buybacks rather than on upward estimate revisions.
Read our earnings preview for Laureate Education, Inc.: https://www.earningswhispers.com/article/LAUR/21093
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 11 hours | |
| 11 hours | |
| Oct-21 | |
| Sep-29 | |
| Aug-05 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jun-30 | |
| May-21 | |
| Apr-30 | |
| Apr-30 | |
| Mar-24 | |
| Mar-10 |
