KBR Beats On Earnings As STS Surge Offsets NASA-Driven Erosion At Mission Technology Ahead Of Spin
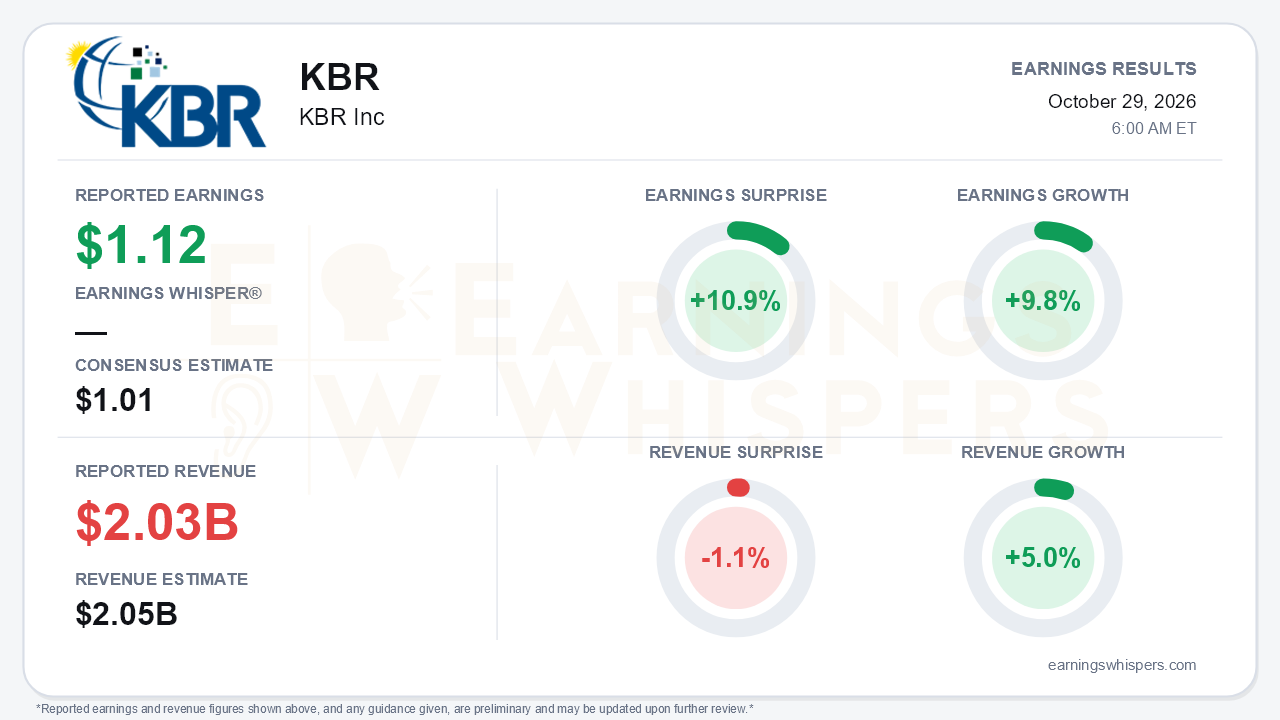
KBR delivered adjusted earnings of $1.12 per share for the third quarter, beating the $1.01 consensus by 10.9% and growing 9.8% from a year ago. Revenue of $2.028 billion rose 5.0% but missed the $2.05 billion consensus by 1.1%. Management reaffirmed full-year guidance for the third straight call. The headline is a solid profit beat, but the quarter is really a tale of two businesses heading in opposite directions just weeks before they separate. Sustainable Technology Solutions is accelerating sharply. Mission Technology Solutions, the future Trinzic, is shrinking on NASA insourcing and slower U.S. awards.
The quality of the beat deserves scrutiny. GAAP operating income fell 3% to $186 million. Spin-off costs rose to $24 million from $4 million, and SG&A moved higher. GAAP diluted EPS of $1.06 rose 18%, but it was helped by a sharply lower tax provision ($18 million versus $34 million) tied to a discrete tax benefit. Management appropriately stripped the related $0.12 of interest income out of adjusted EPS. The 12% adjusted EBITDA growth to $268 million also needs a footnote. Starting this year, KBR adds back its share of joint-venture interest, taxes and D&A, which contributed $17 million this quarter. That add-back was not applied to the prior-year base. Fewer shares outstanding (126 million versus 128 million) also helped per-share results. Even so, underlying growth did improve. Adjusted EPS growth of 9.8% outpaced the 4% year-to-date rate, and consolidated revenue growth of 5% compares with 2% in the second quarter and a decline in the first.
STS is the engine. Segment revenue jumped 26% to $762 million, up from 10% growth in the second quarter and a slight decline in the first, as earlier bookings converted. Backlog reached a record $5.8 billion, up from $4.2 billion at the end of fiscal 2025. New wins included the SABIC ammonia technology award (KBR's second large ammonia win this year), Aramco's Marjan field, ADNOC program management, Diriyah Gate and a first-of-its-kind SAF license in Kazakhstan. The segment's margin did slip to 19.3% from 21.2%. Excluding Plaquemines LNG, however, the call put the margin at 13.9%, up 80 basis points sequentially. MTS moved the other way. Revenue fell 5% after growing 2% in the second quarter. Reported book-to-bill dropped to 0.6x after KBR de-booked remaining NASA out-year work, and it was only 0.8x excluding NASA. Proposals awaiting decision fell to $9.9 billion from $16 billion in the first quarter. MTS margins of 11.5% rose 110 basis points, but management indicated early favorable contract closeouts flattered the year-to-date figure and expects normalization in the fourth quarter.
The forward risks are concrete. The reaffirmed $980 million to $1.04 billion EBITDA guide implies fourth-quarter EBITDA of roughly $203 million to $263 million against $268 million in the third quarter, consistent with the step-down management flagged. Plaquemines LNG equity income, about $115 million through the third quarter, declines into 2027. Management also warned that first-half 2027 MTS comparisons will be difficult. Cash is a softer spot. Operating cash flow fell 14% in the quarter, receivables rose $218 million year to date, and Middle East collection delays could push $25 million to $50 million past year-end. Buybacks are paused ahead of the spin. On the catalyst side, the $8 billion Antarctic contract was secured after the protest but is not yet in backlog. The Firefly counter-drone system was selected for a Pentagon pilot. Separate Investor Days on November 11 and 12 should define each company's standalone outlook.
The market setup is more complicated than the surprise implies. Shares closed at $40.14 before the report. That is up 15.1% since the open after the July release, 7.8% above the 200-day moving average and less than 1% below the inter-earnings high of $40.52 set the day before earnings. The stock had rallied nearly 25% off the $32.14 low struck on the prior report day. Price and AVWAP trend readings are positive. Investor sentiment, meanwhile, remained firmly negative and edged slightly lower, from -0.64 to -0.67. Holders are clearly skeptical even as the stock climbed. A revenue miss and reaffirmed rather than raised guidance give that skepticism something to point to, while the price already reflects considerable spin optimism.
The bottom line is that KBR's earnings beat was real but leaned on tax, share count and a more generous EBITDA definition. Beneath it, STS momentum is genuinely improving while MTS bookings and pipeline are deteriorating. With the stock entering the report near its quarterly high and the Investor Days approaching, the next leg likely depends less on this quarter than on whether management can show a credible standalone growth path for Trinzic and durable margins for KBR once LNG income fades.
Read our earnings preview for KBR Inc: https://www.earningswhispers.com/article/KBR/21091
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| 13 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-14 | |
| Oct-06 | |
| Oct-05 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-28 | |
| Sep-24 | |
| Sep-09 | |
| Sep-09 |
