Ranpak Narrows Its Loss On Margin And Cost Discipline, But Slowing Growth And A Merely Reaffirmed Outlook Keep The Burden Of Proof High
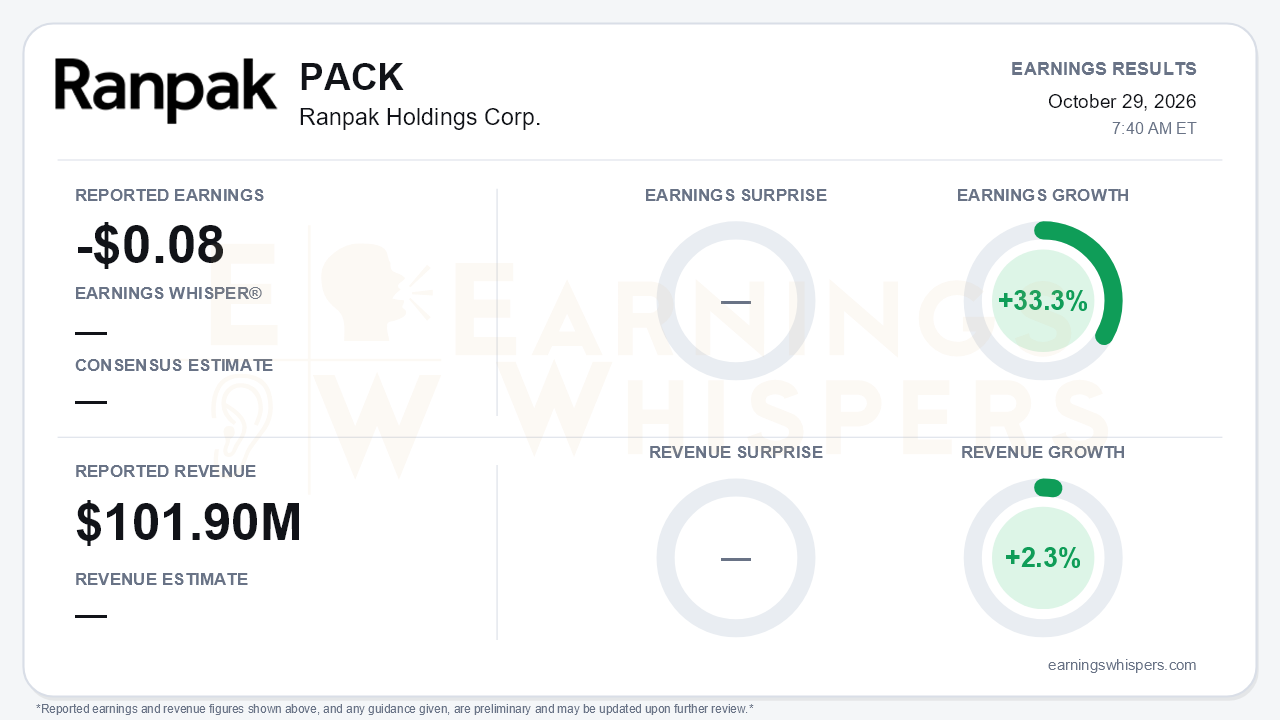
Ranpak Holdings (NYSE: PACK) delivered a quarter of better execution on weaker growth. The company reported a third-quarter loss of $0.08 per share, compared with a $0.12 loss a year earlier, an earnings improvement of 33.3%. Revenue rose 2.3% to $101.9 million, or 3.4% in constant currency. No consensus figures were available to measure a beat or miss, so the report has to be judged on its trajectory. That is the central tension: margins, costs and cash all moved in the right direction, while the top line slowed sharply in a macro backdrop management itself described as markedly more volatile.
The profit improvement looks real rather than cosmetic. Gross margin expanded 110 basis points year over year to 35.6% and jumped 280 basis points from the second quarter, driven by North America. SG&A fell to $25.7 million from $29.6 million, and operating results moved from a $5.7 million loss to roughly breakeven. Adjusted EBITDA rose 5.1% to $22.5 million, up from $19.1 million in Q2 and $18.9 million in Q1. Cash generation was the clearest improvement. Year-to-date operating cash flow reached $24.8 million versus $3.6 million a year ago, quarter-end cash climbed above $10 million sequentially to $53.4 million, and net leverage eased to 4.3x from 4.7x in Q1. Investors should still keep the GAAP picture in view, since the company remains loss-making with $402.8 million of term debt and $8.7 million of quarterly interest expense.
Beneath the headline, growth decelerated on almost every front. Constant-currency revenue growth slowed to 3.4% from 12.2% in Q2. Automation, the centerpiece of the diversification story, grew 23.5% in constant currency (26.9% excluding warrants), down from triple-digit rates in each of the first two quarters. Paper consumable volumes fell 2.5%, reversing Q2's 2.4% gain, and the decline was cushioned only by a 3.5% price/mix contribution. Europe/Asia was the weak spot, with volumes down 4.9% as the channel digested a Q2 surcharge pre-buy and APAC demand stayed soft. Region revenue grew just 0.5% in constant currency after 15.4% in Q2. The PPS installed base also shrank 1.9% to 142.8 thousand machines. North America offered the bright spot: the distribution channel returned to growth, volumes rose 1.8%, and regional margins improved more than 290 basis points.
The forward picture contains genuine catalysts alongside fresh risks. Automation turned adjusted-EBITDA positive in Q3. Management reaffirmed its roughly $60 million automation revenue target for 2026 and expects the business to be profitable in 2027. A new global partnership with ElementLogic, cold-chain capacity arriving in early 2027, and APAC local paper sourcing that is about 90% complete all support the medium-term case. The risks, however, are nearer at hand:
- Dutch natural gas above EUR 90/MWh is lifting European paper costs, and management expects European margin pressure in Q4.
- Currency has turned from a tailwind into an expected 2% headwind.
- Deliberate pruning of warrant-linked enterprise consumables trims the top line.
That makes the outlook the crux. Management said only that it continues to expect to meet prior guidance of $415-445 million in revenue and $83.5-95 million in adjusted EBITDA. Earlier language about surpassing that range was not repeated, and neither was the $800 million 2030 target. With $60.5 million of adjusted EBITDA through nine months, even the low end implies Q4 adjusted EBITDA of roughly $23 million. That would be above Q3's level, delivered against the very headwinds management flagged. Bears have legitimate ammunition here.
The market had already priced in considerable doubt. Shares fell 30% from the $5.40 open after the July report to $3.78 ahead of this release. That left them 26.8% below the 200-day moving average and 35.5% below the August 4 inter-earnings high of $5.86, though 15.6% above the October 14 low of $3.27. Investor sentiment improved meaningfully, from -0.24 to -0.10, but remains negative. Earnings Whispers trend readings are mostly negative on price and AVWAP, with momentum the lone positive.
The bottom line is that Ranpak showed it can expand margins, cut costs and generate cash even as demand softens. The quarter nonetheless offered little evidence that growth is re-accelerating. A reaffirmed outlook that requires a stronger fourth quarter in a deteriorating European cost environment keeps the burden of proof on management, and the stock's depressed position suggests investors will want to see Q4 delivery before giving the execution story full credit.
Read our earnings preview for Ranpak Holdings Corp.: https://www.earningswhispers.com/article/PACK/21313
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-22 | |
| Jul-30 | |
| Jul-30 | |
| Jul-22 | |
| Apr-30 | |
| Apr-22 | |
| Mar-06 | |
| Mar-06 | |
| Mar-05 | |
| Mar-05 | |
| Feb-26 | |
| Jan-13 |
