Omnicell's Margin-Driven Beat And Third Profit Raise Mask A Top Line Still Waiting On Titan XT
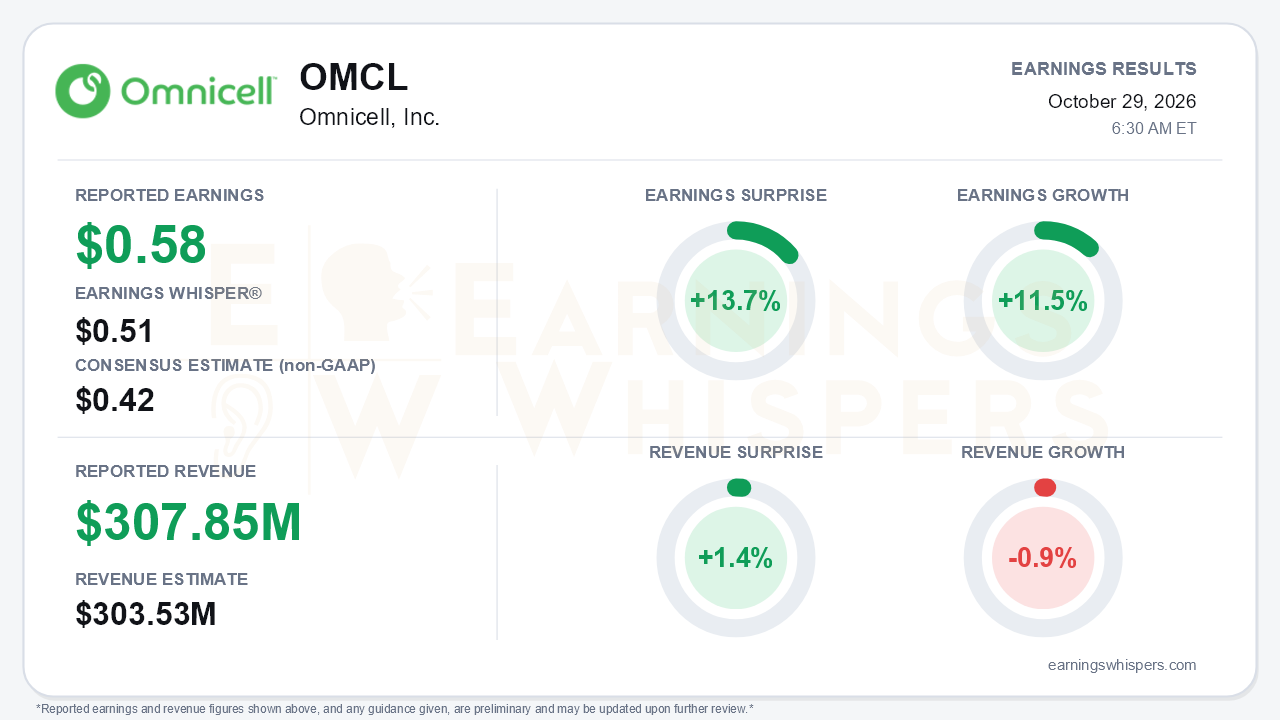
Omnicell delivered another quarter in which profitability did the heavy lifting. Non-GAAP earnings of $0.58 per share cleared the $0.42 consensus by 13.7% and topped the $0.51 Earnings Whisper number. Earnings grew 11.5% year over year even as revenue slipped 0.9% to $307.85 million, which still beat the $303.53 million consensus by 1.4%. Management then raised full-year non-GAAP EBITDA and EPS guidance for the third consecutive call while trimming revenue, product revenue and ARR expectations. That is the central tension: Omnicell is executing on margins, but the hardware refresh cycle that underpins the long-term story has not yet appeared in the revenue line.
The quality of the beat deserves scrutiny, and it holds up better on the service side than on the product side. Product revenue fell to $173.1 million from $177.5 million, and non-GAAP product gross margin compressed to 43.8% from 45.8%. Memory chip costs, which management estimated at roughly $6 million for the second half with about half landing in Q3, contributed to that pressure. Service carried the quarter. Service revenue rose modestly to $134.8 million, but non-GAAP service gross margin jumped to 47.6% from 42.1% as cost of service revenue fell nearly 10%. Non-GAAP operating expenses edged down to $108.2 million, lifting non-GAAP EBITDA to $44.9 million, or a 14.6% margin versus 13.2% a year ago. That result was well above the $32-37 million guide. On a GAAP basis, net income doubled to $0.24 per share from $0.12, so the improvement is not purely an adjustment story. Management acknowledged, however, that some Q3 expense timing shifted into Q4, which flatters the quarter at the expense of the next.
The guidance trajectory tells the story more clearly than any single quarter:
- **Rising:** Full-year EBITDA guidance has climbed every call, from $145-160 million at the start of the year to $187-193 million now. EPS guidance has moved from $1.65-1.85 to $2.48-2.56.
- **Drifting lower:** Total revenue guidance has narrowed to $1.225-1.231 billion, near the low end of the original range. Product revenue was cut to $684-687 million from $690-700 million. Year-end ARR guidance has slid from $680-700 million originally to $660-670 million, with the 340B program now cited as a modest headwind.
- **Weak exit:** Q4 guidance of $295-301 million in revenue and $30-36 million in EBITDA implies sequential declines on both lines.
Product bookings guidance stayed at a wide $425-560 million after being cut at Q2. It remains back-end weighted, with no Q3 bookings figure disclosed, leaving an unusually large swing riding on the fourth quarter.
The call preserved a credible growth story, even if it remains largely prospective. Management said first Titan XT hardware shipments were days away and on schedule. It also said the pipeline grew modestly and matured, with competitive evaluations advancing into contracting and deployment planning. Customers reportedly responded favorably to OmniSphere subscription pricing, though general availability is still slated for the first half of 2027. Management clarified that the more than $2.5 billion replacement opportunity covers installed-base hardware only, excluding OmniSphere monetization and competitive share gains. Leasing has emerged as a meaningful lever, with roughly 30% of the market leasing and much of that demand coming from competitor customers. The trade-offs are real, however. Leases dilute upfront gross margin, and competitive conversions take 9-12 months to reach revenue, which lowers in-year conversion of bookings. Bears have legitimate ammunition in the flat demand signals and persistent memory costs.
The balance sheet gives management room to wait. Cash rose to $315 million against $169 million in convertible notes, and the $350 million revolver is undrawn. Q3 free cash flow of $19.9 million improved from $14.0 million a year ago, but it fell well short of the $56 million generated in Q2, which included a tariff refund.
The market setup reflects that ambivalence. Investor sentiment remained negative heading into the report but improved modestly, from -0.13 to -0.09. Shares closed at $35.95 the day before earnings, essentially unchanged (+1.2%) from the open following the July report. The stock sat 8.4% below its 200-day moving average of $39.24, roughly in the middle of an inter-earnings range between $31.98 in late September and $38.00 in early August. Trend readings were mixed, with momentum negative while AVWAP was positive. That picture describes a stock that has recovered from its September low but has not been rewarded for repeated profit raises.
The bottom line is that Omnicell continues to prove it can manufacture earnings leverage from a flat revenue base, and the third straight EBITDA and EPS raise is a genuine accomplishment. But margin expansion driven by cost discipline and expense timing has a ceiling, and the Q4 guide already implies a step down. Investors still need evidence that Titan XT shipments, competitive wins and OmniSphere can turn into bookings and revenue growth. Until the top line inflects and the wide bookings range resolves, the market is likely to keep discounting the profit story.
Read our earnings preview for Omnicell, Inc.: https://www.earningswhispers.com/article/OMCL/21112
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| 12 hours | |
| Oct-21 | |
| Oct-08 | |
| Sep-03 | |
| Aug-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-13 | |
| Jun-02 | |
| May-04 | |
| Apr-29 | |
| Apr-29 |
