Darling Ingredients Edges Consensus But Misses The Whisper As DGD Margins Compress; Balance Sheet Repair Carries The Quarter
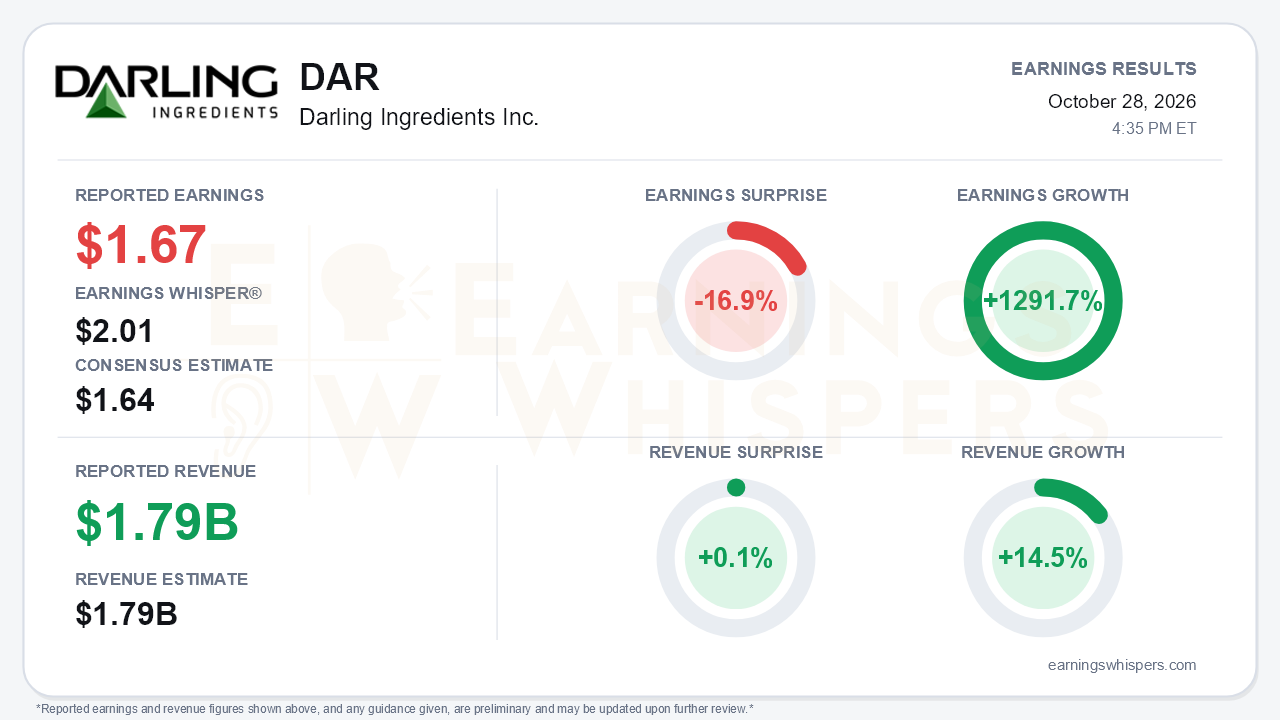
Darling Ingredients (NYSE: DAR) reported third-quarter earnings of $1.67 per share on revenue of $1.791 billion. That narrowly topped the $1.64 consensus but fell well short of the $2.01 Earnings Whisper number, a 16.9% miss against the bar investors were actually watching. Revenue was essentially in line, 0.1% above the $1.79 billion consensus, and grew 14.5% year over year. Earnings grew 1291.7% from the $0.12 earned a year ago, when Diamond Green Diesel (DGD) was losing money. The year-over-year comparison is spectacular. The sequential picture is not, and that is the central tension: Darling's earnings power stepped down sharply from the second quarter even as its balance sheet improved faster than at any point this year.
The quality of the headline beat deserves scrutiny. GAAP net income of $267.0 million included a $63.5 million gain on the sale of businesses, tied to the closed European casings divestiture and most of the grease trap assets. That gain is worth roughly $0.40 per share before taxes. Strip it out and the consensus beat looks more like a shortfall. Combined adjusted EBITDA of $514.3 million more than doubled from $244.9 million a year ago, but it fell from about $742 million in the second quarter. Darling's share of DGD EBITDA dropped to $204 million from $389 million as margins slid to $1.30 per gallon from $2.23. Volumes were 315 million gallons, short of the 335 million guided, because a third-party hydrogen outage in the Gulf cost roughly 20 million gallons. Hedge losses, a lower production-tax-credit mix and a fall in D4 RIN prices from about $2.45 to below $2 squeezed margin capture further.
The core ingredients business was steadier but still disappointed. Core adjusted EBITDA of about $310 million declined from $353 million in the second quarter and missed the company's own $325 to $340 million guide. Management attributed the gap to roughly $15 million of deferred profit and lower-of-cost-or-market timing plus higher incentive accruals. It argued core would have been near $340 million without those items, though the accrual pressure is not expected to reverse. Year over year, Feed was the clear bright spot, with segment adjusted EBITDA rising to $247.7 million from $174.0 million on strong protein demand tied to fish meal tightness and poultry growth. Food was nearly flat at $73.8 million, held back by Brazilian tariffs and customer destocking. Corporate costs rose to $35.2 million from $22.3 million.
Guidance offers support but limited upside. Full-year combined adjusted EBITDA is set at $2.2 to $2.3 billion. The press release describes this as reaffirmed, while the call framed it as the first full-year combined guide that includes DGD. In either case, management called it conservative. Against roughly $1.66 billion earned through nine months, the range implies a fourth quarter above the third, driven by an expected reversal of hedge losses, the PTC capture shortfall and timing items, plus a 325 million gallon DGD volume target and firmer fat prices. The implied core outlook of $320 to $340 million is flat, not growing. Management also moved away from core-only guidance, citing accounting volatility, which makes the business harder to track.
The balance sheet is where the story improved. DGD distributed $171 million in cash, $33 million in dividends and $138 million in PTC sales. Net debt fell about $420 million, double the second quarter's reduction, and leverage dropped to 1.7x from 2.3x. Darling repurchased $75.9 million in stock and is targeting net debt at or below $3.0 billion by year-end and about $2.5 billion by early 2027. At that point the board is debating a dividend versus larger buybacks. The NextCognia collagen launch and a Tessenderlo collagen joint venture targeted for the first quarter of 2027 add longer-dated catalysts. Bears still have legitimate ammunition:
- 50% Canadian and 37.5% Brazilian tariffs are disrupting fat and collagen flows.
- RIN prices weakened during the quarter.
- Timing of the 2028-and-beyond renewable volume obligations remains uncertain, along with midterm election risk.
Investors were not positioned optimistically. Earnings Whispers sentiment stayed negative and deteriorated further, moving from -0.14 to -0.25. Shares sat at $55.46, down 8.1% since the open after the July report and about 4.7% below the 200-day moving average of $58.21. The AVWAP trend remains negative, while the price trend is only neutral.
The bottom line is that Darling delivered a noisy, sequentially weaker quarter that missed the whisper by a wide margin, and a one-time divestiture gain flattered the reported EPS. What the company did convincingly was convert DGD cash and asset sales into rapid deleveraging and a credible path to larger capital returns. Whether the stock can recover its 200-day average likely depends on management proving that third-quarter margin compression was timing rather than trend, starting with a fourth quarter that lands within its full-year guide.
Read our earnings preview for Darling Ingredients Inc.: https://www.earningswhispers.com/article/DAR/21057
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-05 | |
| Oct-01 | |
| Aug-11 | |
| Aug-11 | |
| Aug-05 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 |
