Churchill Downs Matches On EPS As Buybacks And Asset Sales Outrun A Softening Virginia Engine
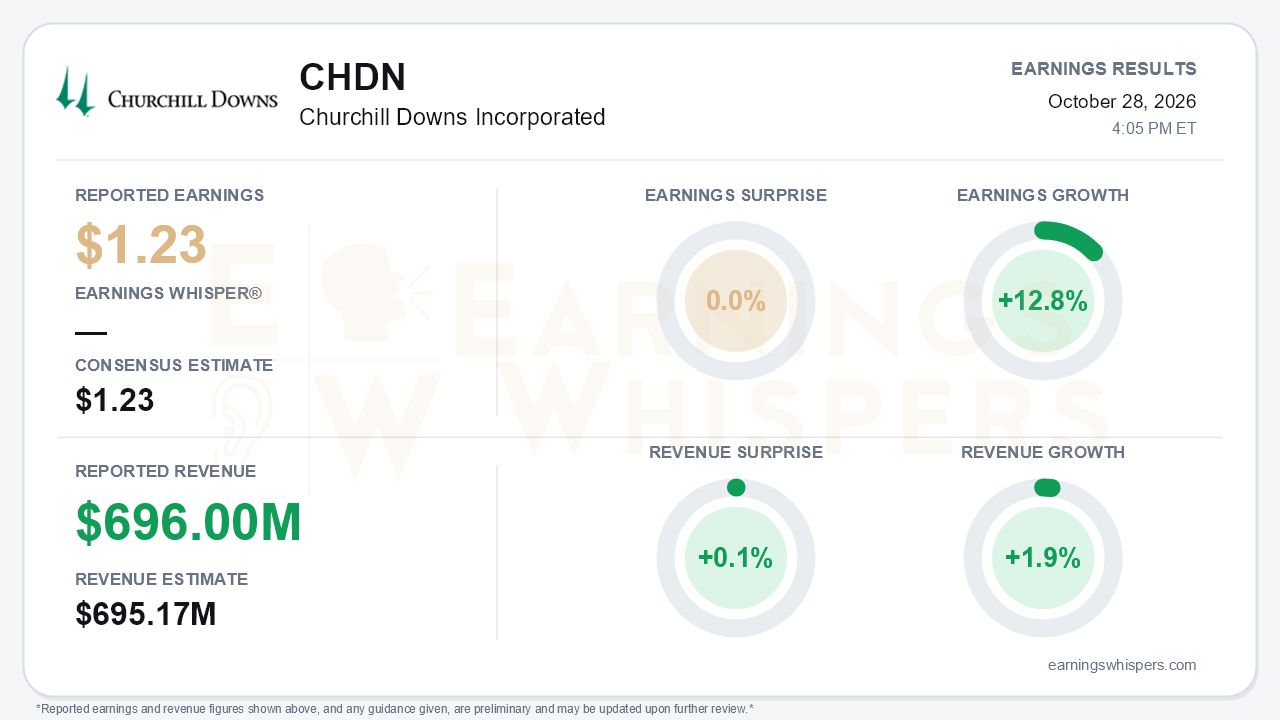
Churchill Downs delivered a third quarter that matched expectations rather than beat them. Adjusted earnings of $1.23 per share were exactly in line with the $1.23 consensus and grew 12.8% from a year ago. Revenue of $696.0 million edged past the $695.17 million estimate by 0.1% and rose 1.9%. GAAP diluted EPS more than doubled to $1.15 from $0.54, but that comparison is flattered by a $35 million after-tax impairment of the Chasers' gaming rights in the prior-year quarter. The central tension is that per-share earnings grew at a double-digit pace while the operating business barely moved. Adjusted EBITDA rose just $2 million, or 1%, to a record $264 million, and only 2% after excluding last year's insurance recovery.
The quality of the earnings growth deserves scrutiny. Much of the gap between 1% EBITDA growth and 12.8% EPS growth came from below the operating line. Net interest expense fell to $69 million from $75 million after the refinancing. Equity income from unconsolidated affiliates rose, led by Rivers Des Plaines and Miami Valley Gaming. The diluted share count also slipped to 70 million from 71 million. By the company's own bridge, results of operations contributed only about $3 million after tax to the $9 million increase in adjusted net income. That is respectable financial engineering, not an operating acceleration.
Beneath the headline, the segments are moving in opposite directions.
- **Kentucky:** Kentucky HRM venues remain the growth engine. Revenue rose $11 million, and adjusted EBITDA climbed 10%, matching Q2's pace but down from 17% in Q1.
- **Virginia:** Virginia is the clear soft spot and is worsening. EBITDA growth slid from +6% in Q1 to +1% in Q2, then fell $6 million year over year in Q3 even excluding the insurance comparison. Central Virginia alone dropped $10 million, hit by competition from the Petersburg casino and roughly $5 million of new tax on live racing days under the structure effective July 1.
- **Live and Historical Racing:** As a result, segment EBITDA declined to $111 million from $116 million despite higher revenue.
- **Gaming:** Gaming EBITDA rose about 4%, and management described consumer trends as improving both year over year and sequentially.
- **Margins:** Same-store casino margins were flat.
- **Wagering:** Wagering Services added $2 million of EBITDA on stronger horse racing. TwinSpires handle increased to $485 million from $472 million.
The call did more to shift the narrative than the numbers did. Management moved from launching a strategic review to executing it. Regional gaming asset sales, structured as individual or small-group deals, are now expected to be executed by year-end, with leverage guided below 3.0x after closing. The new Thoroughbred Championship Series with NYRA adds a league-style format with a $5 million bonus pool, beginning with the 2027 Kentucky Oaks and Derby. Derby 153 ticket sales are pacing about 25% ahead, with roughly 40% of inventory already sold, and Visa signed on as a multi-year sponsor. Virginia's longer-term response is also taking shape: Henry County approved relocating and expanding Collinsville to 150 HRMs, and with the Pulaski and Amherst referendums the three expansions would add 415 machines. Management also raised its expectations for Rockingham Grand ahead of its mid-2027 opening.
Capital return is the other lever being pulled hard. The board authorized a new $750 million buyback, which includes the remaining prior authority, and raised the dividend 7% for a 16th consecutive increase. The company repurchased $48 million of stock in the quarter and another $76 million from October 1 to 27. Nine-month free cash flow of $603 million supports that pace.
The cost is a heavier balance sheet in the interim. Leverage ticked up to 3.8x from 3.7x, and the year-end guide moved to 3.8x-3.9x from 3.6x-3.8x, which management attributed to buybacks. That makes timely execution of the asset sales more consequential, particularly with management acknowledging an M&A market weighed down by rates and consumer uncertainty. Project capex for 2026 was trimmed to $160-180 million on timing, but 2027 project spending is guided at $200-250 million.
Investors have not been rewarding the story. Earnings Whispers sentiment, already negative, deteriorated meaningfully to -0.39 from -0.19 heading into the report. Shares at $81.95 are down 4.1% since the open following the July report and sit 7.3% below the 200-day moving average of $88.39. Price and AVWAP trend readings both remain negative, consistent with a stock that has been drifting lower despite record quarterly results.
The bottom line is that Churchill Downs delivered an in-line quarter in which per-share growth leaned on lower interest costs, equity income and a shrinking share count rather than operating momentum. Kentucky and the Derby franchise remain healthy, but Virginia's deterioration is real and is now compounded by new taxes. The investment case increasingly rests on management converting the strategic review into completed asset sales, deleveraging toward 3.0x, and getting the new HRM capacity and the championship series running. Skeptical sentiment and a sub-200-day share price show that investors want proof of execution before giving credit for those plans.
Read our earnings preview for Churchill Downs Incorporated: https://www.earningswhispers.com/article/CHDN/20913
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-09 | |
| Sep-28 | |
| Sep-21 | |
| Sep-17 | |
| Sep-14 | |
| Aug-06 | |
| Aug-04 |
