Builders FirstSource Beats On A Tax Benefit, Not Operations, As Guidance Holds But Margins And Leverage Keep Worsening
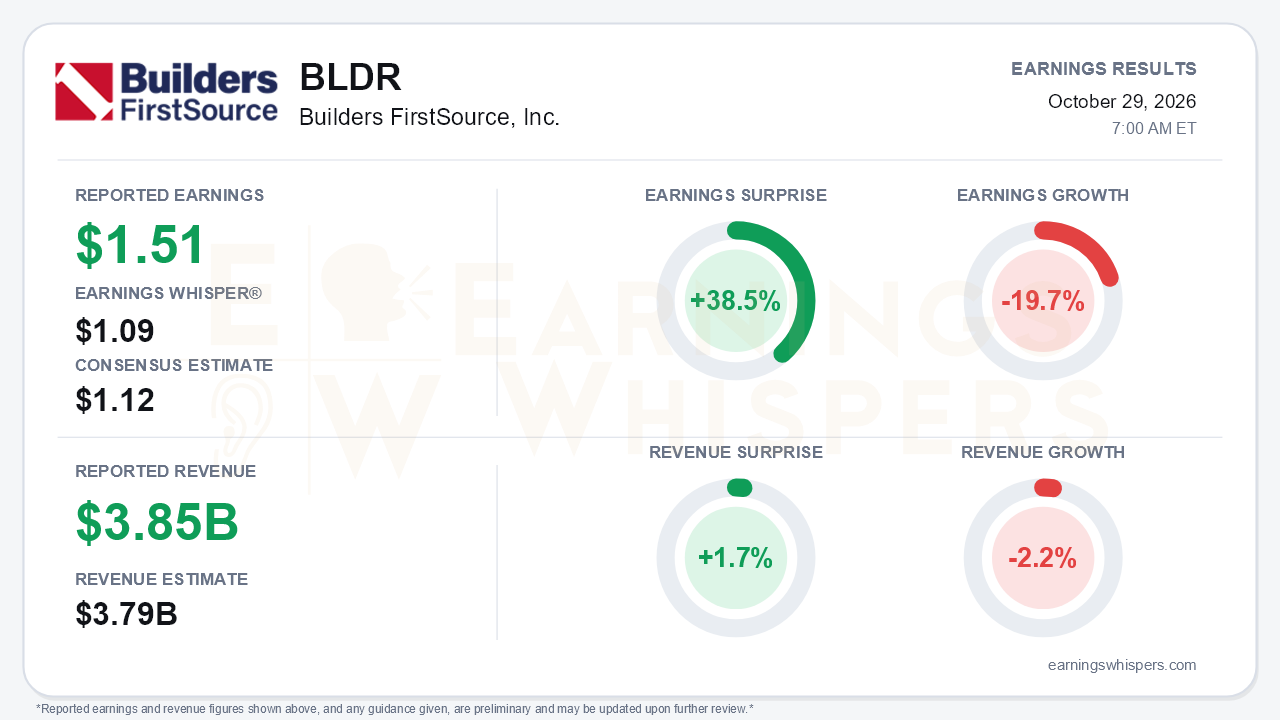
Builders FirstSource (NYSE: BLDR) reported third-quarter adjusted earnings of $1.51 per share, well above the $1.12 consensus and the $1.09 Earnings Whisper number, a 38.5% surprise. Revenue of $3.854 billion fell 2.2% year over year but beat the $3.79 billion consensus by 1.7%. Earnings fell 19.7% from a year ago. The release puts the adjusted EPS decline at 24.5%, against a $2.00 prior-year figure, and the call noted a recast adjusted EPS definition, so the two growth figures likely rest on different prior-year bases. Either way, profits are still shrinking. The size of the EPS beat also overstates what happened in the business. Operationally, this was an in-line quarter. CFO Pete Beckmann said results "met our expectations," and adjusted EBITDA of $311.1 million landed inside the $275 million to $325 million range management had guided.
The quality of the beat deserves scrutiny. GAAP pre-tax income was only $26.8 million, yet the company booked a $33.6 million income tax benefit, which it attributed to losses at certain subsidiaries. That benefit flowed straight into adjusted net income, which the release says was down 26.9% "partially offset by" the tax benefit, and it accounts for much of the gap between the print and the Street. Underneath the tax line, the numbers kept deteriorating:
- **Gross margin** compressed 260 basis points year over year to 27.8%. It has now slid for a fourth straight quarter, from 29.8% in Q4 FY25 to 28.3%, 28.1%, and now 27.8%.
- **Adjusted EBITDA margin** fell to 8.1% from 11.0% a year ago and 8.5% in Q2.
- **Core organic sales** dropped 3.9%, with Single Family down 6.2%.
- **Product mix** weakened. Lumber and sheet goods, up 4.7%, was the only growing category, while higher-value products fell 5.2% and windows, doors and millwork fell 7.3%.
- **Free cash flow** collapsed to $76.0 million from $464.9 million.
The call offered genuine, if modest, improvements. After cutting full-year guidance three straight times, management narrowed the 2026 outlook to $14.2 billion to $14.6 billion in sales and $1.075 billion to $1.125 billion in adjusted EBITDA, holding the Q2 midpoints. For perspective, the EBITDA range began the year at $1.3 billion to $1.7 billion. Other positives:
- Management said share commentary shifted from "maintained" to "gained," notably in lumber through bundling.
- Competitive gross-margin pricing reportedly stabilized after late Q2.
- Cost actions remain on track for $115 million in 2026 savings and a $140 million run rate.
- M&A picked back up, with ICG and Gleckler & Sons acquired for $91 million in the quarter versus $14 million in Q2.
- The company made venture investments in AI construction-software platforms DIG and Scaffold.
The call preserved a credible strategic story, but not a cyclical one. The forward signals were sobering. Mortgage rates are back above 7%. Fall demand was described as weak, and builders are expected to slow starts further, with roughly a three-month lag before that reaches BLDR's volumes. Management guided fourth-quarter gross margin down slightly from Q3. Early 2027 scenarios, which management framed as scenarios rather than guidance, imply an adjusted EBITDA margin in the low-6% range at the midpoint. Those scenarios assume steep decrementals, some price bleed in builder negotiations, and no new cost actions. Fuel costs have doubled year over year, and multifamily, including build-to-rent, remains muted. Productivity savings also slowed to $23 million from $28 million in Q2, and the $60 million to $70 million full-year target implies only a modest fourth-quarter contribution after $57 million year to date.
The balance sheet is where bears have the most legitimate ammunition. Net debt to LTM adjusted EBITDA rose to 4.1x, up from 3.6x in Q2, 3.2x in Q1, and 2.7x at the end of FY25. Net debt stands at $4.6 billion, against just $55 million of cash. The free cash flow guide was narrowed to $400 million to $450 million, trimming the midpoint. Leverage is climbing because EBITDA is shrinking, not because of aggressive borrowing. Even so, rising leverage limits buyback firepower, despite $500 million remaining on the authorization, at a point when the shares are cheaper than the program's $81.26 average repurchase price.
Investor sentiment remains negative but improved modestly, moving from -0.44 after the prior report to -0.38 heading into this one. That suggests expectations were low and slightly less pessimistic, not that a recovery was being priced in. The stock tells the same story:
- Shares closed at $55.88 before the report, down 15.8% from the $66.40 open after the July release.
- That price sits roughly 31% below the 200-day moving average of $81.04.
- The stock set a 52-week low of $49.67 on October 14 and has since rebounded about 12.5%.
- It remains about 27% below the August 7 inter-earnings high of $76.80.
The Earnings Whispers trend signals are uniformly negative, with price, sequential growth, momentum, and AVWAP all deteriorating.
The bottom line is that BLDR delivered a large headline beat, but the surprise came mostly from below the operating line. The operating business performed as guided while margins, cash flow, and leverage all moved the wrong way again. Holding guidance midpoints and regaining share are real positives. However, the 2027 framework and rate backdrop suggest the earnings trough is not yet visible. The November 17 Investor Day now carries the burden of showing a path back to margin expansion.
Read our earnings preview for Builders FirstSource, Inc.: https://www.earningswhispers.com/article/BLDR/21039
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 6 hours | |
| 6 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-28 | |
| Sep-22 | |
| Sep-21 |
